Benchmarks / How customers hear about you at BFCM
How “How Did You Hear About Us?” Answers Change During BFCM
After checkout, Fairing’s post-purchase survey asks customers “How did you hear about us?” We compared what customers answered during Black Friday Cyber Monday (BFCM) 2025 with what they answered in a typical month before the holiday rush, across 800+ Shopify and ecommerce brands, to help you plan for BFCM 2026.
By Bryan Romeike · Published October 2026 · How we measured
BFCM budgets get set, and judged, on attribution reports. Many of those reports favor what drove the conversion over what drove the intent. So we looked for BFCM trends in what customers say brought them to you, to help you plan your BFCM 2026 acquisition. The biggest shift, more customers crediting word of mouth, showed up in each of the last three years.
This is the companion to our Black Friday and Cyber Monday benchmarks, which covers BFCM order volume, timing and pacing.
Key takeaways
More than 1 in 5 first-time BFCM customers credited a friend or family member, up from about 1 in 6 in October (15.8% to 22.0% at the typical brand). It rose by about the same amount in each of the last three years.
About two-thirds of those customers arrived with no UTM tag. Read a BFCM jump in direct traffic as partly word of mouth. (Section 1, Section 3)
About 1 in 9 paid-search-tagged dollars came from customers who named search, down from about 1 in 6 in October. On paid social, 27% of tagged dollars came from customers who named something else, up from 18%.
Before your BFCM ROAS shapes 2026 budgets, check Performance Max and your own brand campaigns against what customers say. (Section 3)
BFCM 2024 friends-and-family buyers reordered less over 12 months than the brand’s other BFCM first-time buyers (13.6% vs 15.5%) and spent about 18% less after their first order.
Set referral rewards and CAC targets on 12-month value. (Section 1)
The share of customers naming an influencer held steady, but only about a third of them used a code at BFCM, down from more than half in October.
Give creators discount links that apply their code, and make creator codes stack with your sitewide offer. (Section 4)
Social answers per day ran 3.3 times their October pace, slower than the 3.8 times for all answers, so social’s share fell from 37.8% to 33.7%.
Flag social only if its pace falls well behind your all-answers pace. (Section 2)
How to read this page
The question. Every figure comes from one post-purchase survey question, “How did you hear about us?” (HDYHAU; see our HDYHAU attribution survey best practices). Shares are of customers who answered.
Word of mouth: customers who answered “friends or family”.
Social: Facebook, Instagram, TikTok, Pinterest, Reddit, X and other social apps, ads and organic together. YouTube, creators and podcasts are counted separately.
Three windows:
October (Oct 1 to 31, 2025): the normal-month baseline.
The season (Nov 1 to Dec 20, 2025): the daily chart in section 1.
BFCM (Nov 27 to Dec 1, 2025): Thanksgiving through Cyber Monday, the same five days every year.
Typical brand: the median brand, half above and half below.
Why the median? Every brand counts once, so the biggest brands don’t set the number (the pooled 1 in 4 does that). Small brands also swing a lot, which would drag an average around.
Points: percentage points. A change from October compares each brand with its own October. When a line names another group, such as other BFCM first-time buyers, it compares groups in the same window.
UTM tag: the tracking label on the last link a customer clicked before buying.
On this page
Part 1 · The shift
Part 2 · What your tracking misses
3. Your UTM tags and your customers disagree all year, and the gap widens at BFCM
4. Fewer BFCM orders carry a checkout code, so a code report sees less of BFCM
Part 3 · What to do
1. More customers credit friends and family at BFCM, three years running, and the share peaks in December
The takeaway: Word of mouth jumps at BFCM. At the typical brand, the share of first-time customers who said a friend or family member sent them rose from 15.8% in October to 22.0% over BFCM, and by about the same amount in 2023, 2024 and 2025. It starts climbing in early November and peaks on Dec 8 to 10. Plan for it, and start before Black Friday.
At the typical brand, word of mouth went from 15.8% of answers in October to 22.0% over BFCM 2025 (Nov 27 to Dec 1). Measured brand by brand against each brand’s own October, the median brand gained 4.6 points, and 85% of brands gained. (That’s the middle of each brand’s own change, which is why it’s smaller than 22.0 minus 15.8.) It stayed high after Cyber Monday: in mid-December (Dec 11 to 20), 24.6% of survey answers at the typical brand named friends or family, about 7 points above the brand’s own October, at most brands. Almost all of these answers (about 96%) come from first orders, so these shares describe first-time customers. They leave out most returning customers, who make up part of BFCM revenue.
No other answer moved as much, and these customers are more likely than others to arrive with no UTM tag (section 3).
The lift is bigger among first-time customers. Their word-of-mouth share rose 5.1 points at the typical brand, against 2.7 points for returning customers, and it rose at most brands in both groups. We re-ran it for small, mid-size and large brands, every product category we checked, brands whose survey didn’t change and other subsets, and the rise held each time (see About the data). So expect the biggest lift among new customers, the ones your BFCM acquisition spend is chasing.
Isn’t this just fewer people answering?
No. At BFCM, about 2 points fewer first-time customers answer the question at the typical brand. That explains only a small part of the rise, about 0.3 of the 4.6 points. Even if every customer who skipped the question had named another channel, the typical brand’s friends-and-family share would still be clearly up. Friends-and-family answers also grew about 30% faster than orders, so other customers didn’t just go quiet, and the lift was about 4.6 points at brands whose answer rate held steady. Read the rise as a real shift in who credits friends and family.
The rise isn’t coming from referral programs. At brands with a visible referral program*, the friends-and-family share rose about as much as at brands without one, once you compare brands of similar size and category. Orders on a referral link or referral code were under 1 in 100 answered orders, even at those brands, and that share didn’t grow at BFCM. Almost all the customers who credited friends and family arrived without one. We could only see programs that tag their links or issue referral codes. If you run one, count its own referral-link orders to see what it adds.
When does word of mouth peak around BFCM?
After BFCM. The friends-and-family share starts rising in early November. In the days before Thanksgiving (Nov 24 to 26), it’s about 4 points above the brand’s own October. It peaks on Dec 8 to 10, more than a week after Cyber Monday and the height of gift shopping, so some of the peak may be gift buyers naming the person who asked for the product (see the gifts note below). This daily view uses large brands (1,000+ October answers), the only ones with enough answers to read day by day.
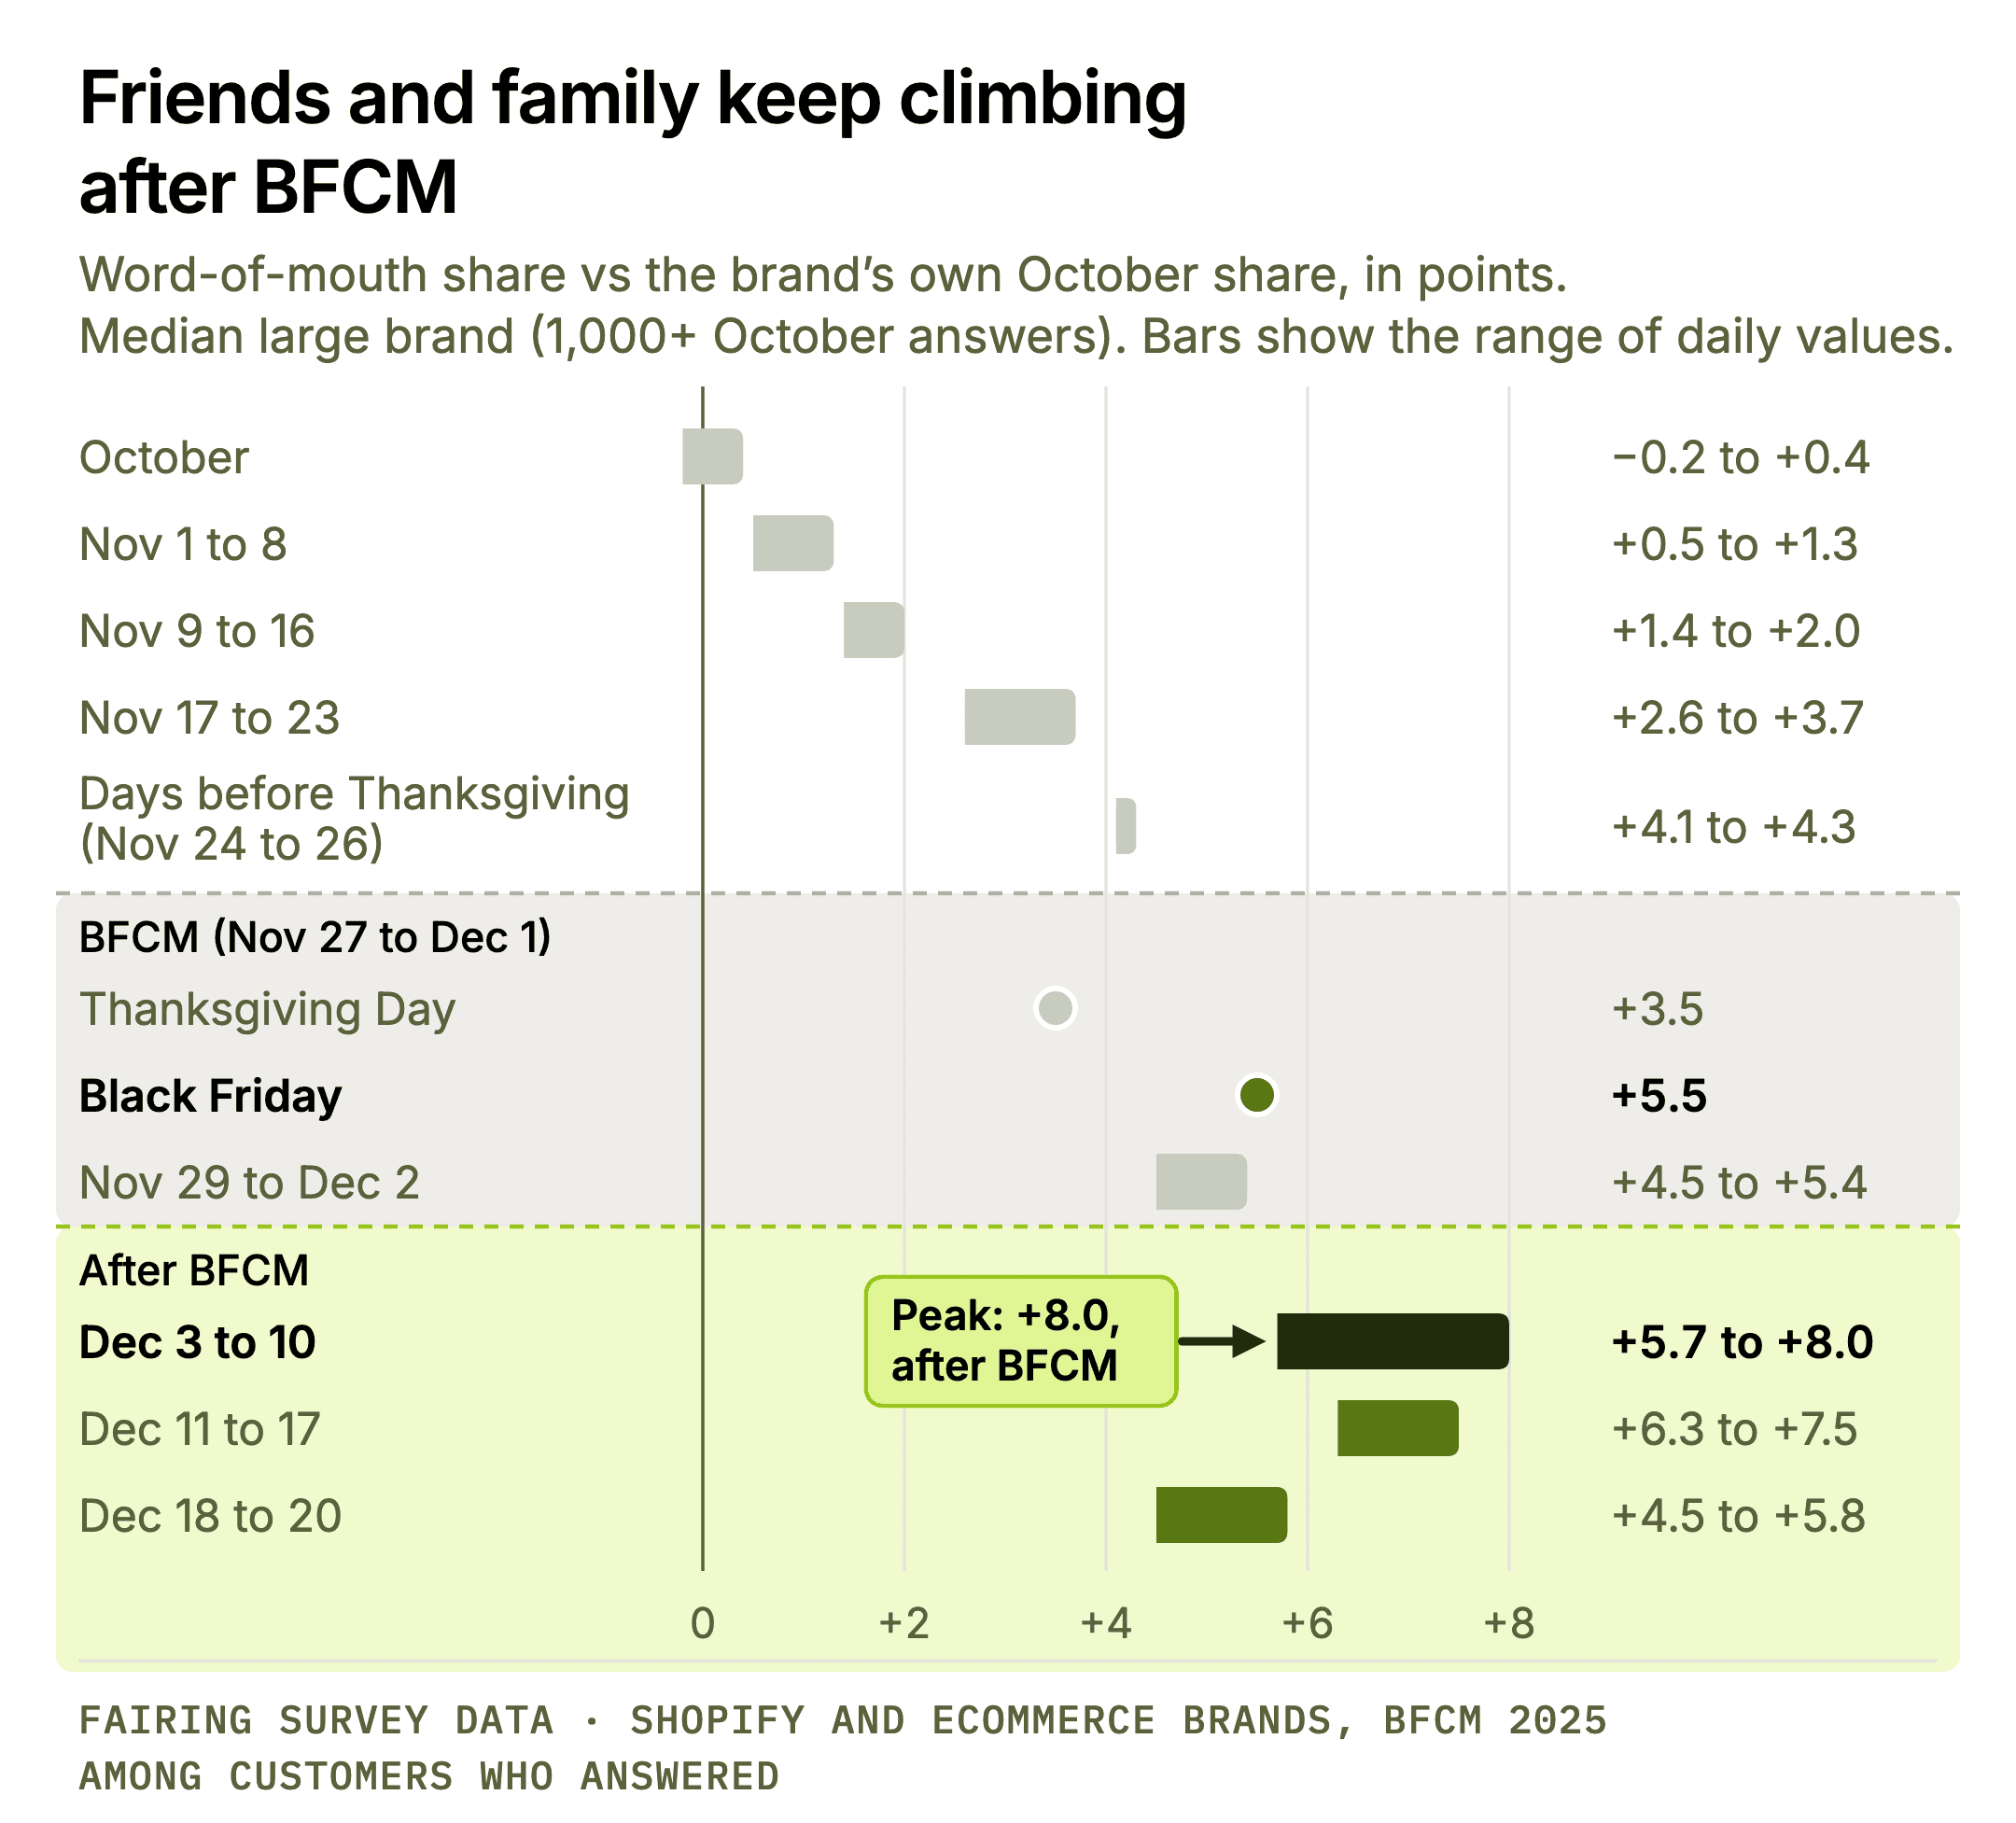
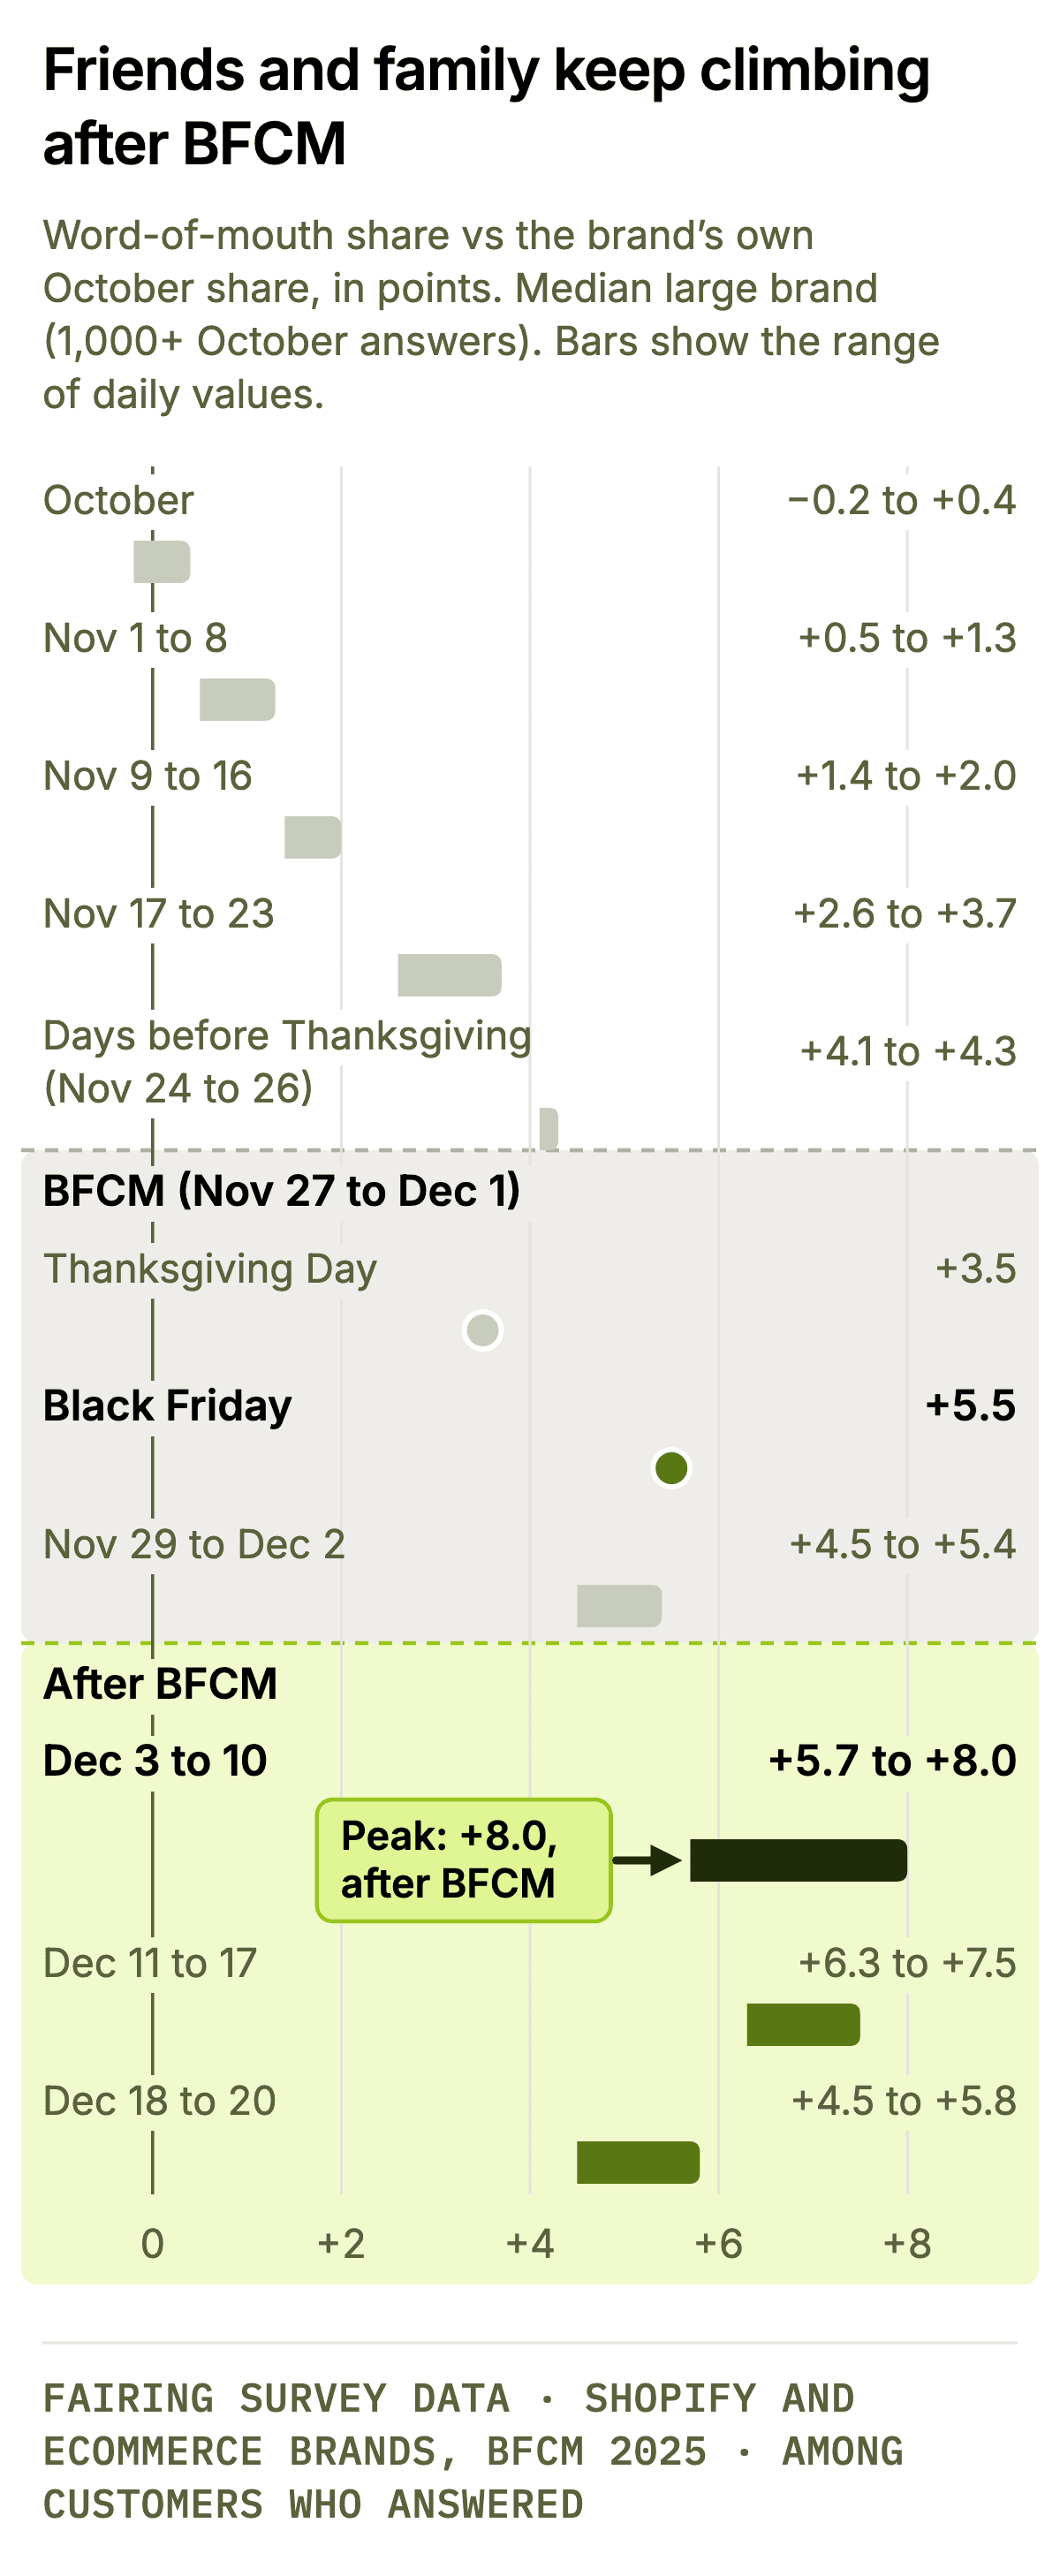
The chart in plain numbers: the typical large brand’s friends-and-family share, in points above its own October share. +5.5 means 5.5 points higher than that brand’s October share.
| Period | Points above October |
|---|---|
| October weeks | -0.2 to +0.4 |
| Nov 1 to 8 | +0.5 to +1.3 |
| Nov 9 to 16 | +1.4 to +2.0 |
| Nov 17 to 23 | +2.6 to +3.7 |
| Days before Thanksgiving (Nov 24 to 26) | +4.1 to +4.3 |
| Thanksgiving Day | +3.5 |
| Black Friday | +5.5 |
| Nov 29 to Dec 2 | +4.5 to +5.4 |
| Dec 3 to 10 | +5.7 to +8.0 (peak Dec 8 to 10) |
| Dec 11 to 17 | +6.3 to +7.5 |
| Dec 18 to 20 | +4.5 to +5.8 |
Word of mouth builds before the order spike and stays up after it. On Black Friday, the share is only about a point higher than in the days before Thanksgiving, even though these brands’ daily orders more than double. So a referral or gifting campaign that runs only over Black Friday weekend misses both the build and the peak. For the order-volume side of the same weeks, see our Black Friday and Cyber Monday benchmarks.
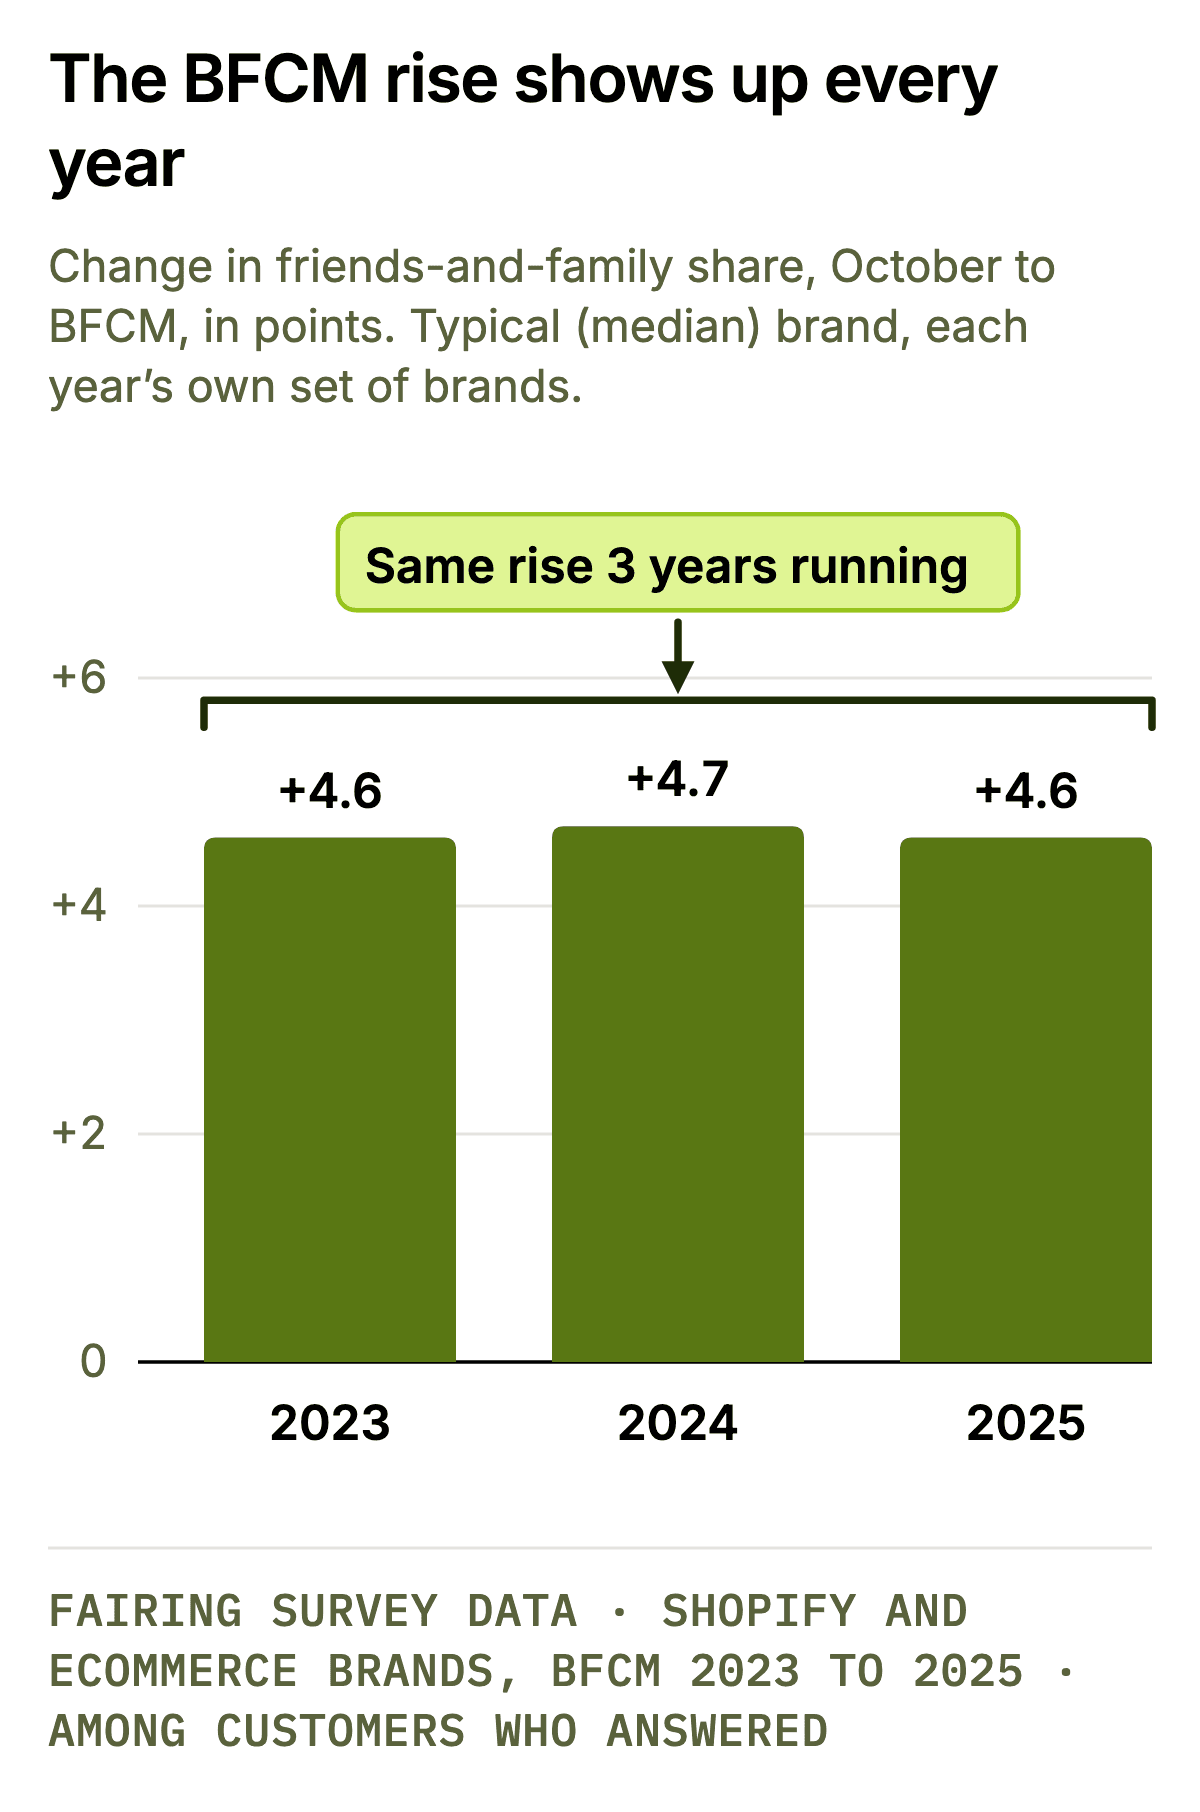
Does the BFCM word-of-mouth rise repeat every year?
Yes, at almost exactly the same size. The typical brand’s friends-and-family share rose over its own October by:
4.6 points in 2023
4.7 points in 2024
4.6 points in 2025
Each year uses that year’s brands, so it’s the same pattern in three groups of brands, not the same brands tracked over time. Treat the lift as something to plan for at BFCM 2026, and measure your own against your own October.

Which categories see the biggest word-of-mouth rise at BFCM?
All of them, apparel most. The friends-and-family share rose in every product category. Of the four with enough brands to list, apparel and accessories rose most (8.0 points over its own October) and food and drug least (2.4 points). Housewares and home (4.0) and health and beauty (3.9) sat a little below the typical brand’s 4.6. Brands pick their own category, so these labels are self-reported. Size your BFCM word-of-mouth plan to your category: apparel brands should plan for a bigger lift than food and drug brands.
| Category | Friends-and-family share, points above own October | Brands where it rose |
|---|---|---|
| Apparel and accessories | +8.0 | 91% |
| Housewares and home | +4.0 | 81% |
| Health and beauty | +3.9 | 87% |
| Food and drug | +2.4 | 75% |
Every other category rose too, but with fewer brands in each, the estimates are too uncertain to list.
Gifts and holiday answers may explain some of the word-of-mouth lift
Someone buying a present that a friend or relative asked for may answer “friends or family”. The category pattern fits that, with apparel rising most. It doesn’t look like a discount effect. On a brand’s big non-holiday sale days (orders at least double its usual), the friends-and-family share didn’t rise: it slipped about 1.4 points below the brand’s own usual share. Gifting holidays without big sales (Mother’s Day, Father’s Day, Valentine’s Day) moved it by less than half a point. So the lift looks like a season-wide holiday effect, not a sale effect. Returning customers’ word-of-mouth share also rose (2.7 points at the typical brand), even though how a returning customer first heard about you doesn’t change at the holidays. So part of the rise may reflect how people answer at the holidays, as well as who finds you. We can’t separate more friend-led discovery from more gift-request buying. The data shows that more BFCM customers credit friends and family. It doesn’t show that word of mouth caused more people to find your brand.
Are word-of-mouth customers worth more?
About the same on order value, lower on repeat buying. At the typical brand, BFCM orders from customers who named friends or family were 2.5% smaller in value than the brand’s other BFCM orders. So word of mouth’s share of answered BFCM revenue is about its share of answered orders, a little over 1 in 5. These customers were also slightly less likely to use a checkout code: about 7% less likely than the brand’s other customers (a relative difference, not points).
Don’t assume a BFCM referral is worth more
BFCM friends-and-family buyers came back less often over 12 months and spent less after their first order. For BFCM 2024 first-time buyers, the typical brand’s friends-and-family buyers reordered within 12 months 13.6% vs 15.5% of the time for the brand’s other BFCM first-time buyers, about 1.6 points lower, and lower at about 7 in 10 brands. They also spent about 5% less per customer over the year, counting the first order, and about 18% less after it, compared with the brand’s other BFCM first-time buyers. October 2024’s friends-and-family buyers reordered like the brand’s other October first-time buyers (19.5% vs 19.1%), so the gap is specific to BFCM. After their first order, October’s friends-and-family buyers spent about the same as everyone else. Gift buying may be one reason: someone who was asked for the product may never have planned to become a customer. The gap is smaller at 90 days (BFCM 2025, friends-and-family vs other first-time buyers: 7.1% vs 7.8%). So don’t assume a BFCM referral is worth more. Plan on lower repeat value for them, and judge BFCM acquisition on 12-month value.
What this means for BFCM 2026: More of your BFCM customers will likely say a friend or family member sent them, from early November through mid-December.
Make sure your survey offers “friends or family” as an answer.
If you run a referral or gifting campaign, have it live for that whole window. The rise happens with or without one, so judge the campaign on its own referral-link orders (section 5).
Expect your attribution reports to under-credit these customers (section 3), but don’t assume they’re worth more: plan on lower repeat value for BFCM referrals (about 18% less revenue after the first order than other BFCM first-time buyers), and judge BFCM acquisition on 12-month value.
2. Social and search grow at BFCM, just slower than word of mouth
The takeaway: Expect social and search to grow at BFCM, just not at the pace of word of mouth. Friends and family grow fastest, so every other channel’s share slips even as its customers grow. If you judge a social campaign by its share of answers, you’re measuring against a baseline BFCM was always going to lower. Judge it on answers per day and on your own incrementality tests.
Social is still the biggest answer at BFCM. At the typical brand, social platforms went from 37.8% of survey answers in October to 33.7% at BFCM, still ahead of friends and family (22.0%). Search went from 8.5% to 7.2%.
But social still grew. Answers per day at BFCM, against each brand’s own October pace:
Social platforms: 3.3 times
All answers: 3.8 times
Friends and family: 5.1 times
So a falling share can still mean more customers. Judge paid social and search on your own incrementality tests, not on their share of survey answers.
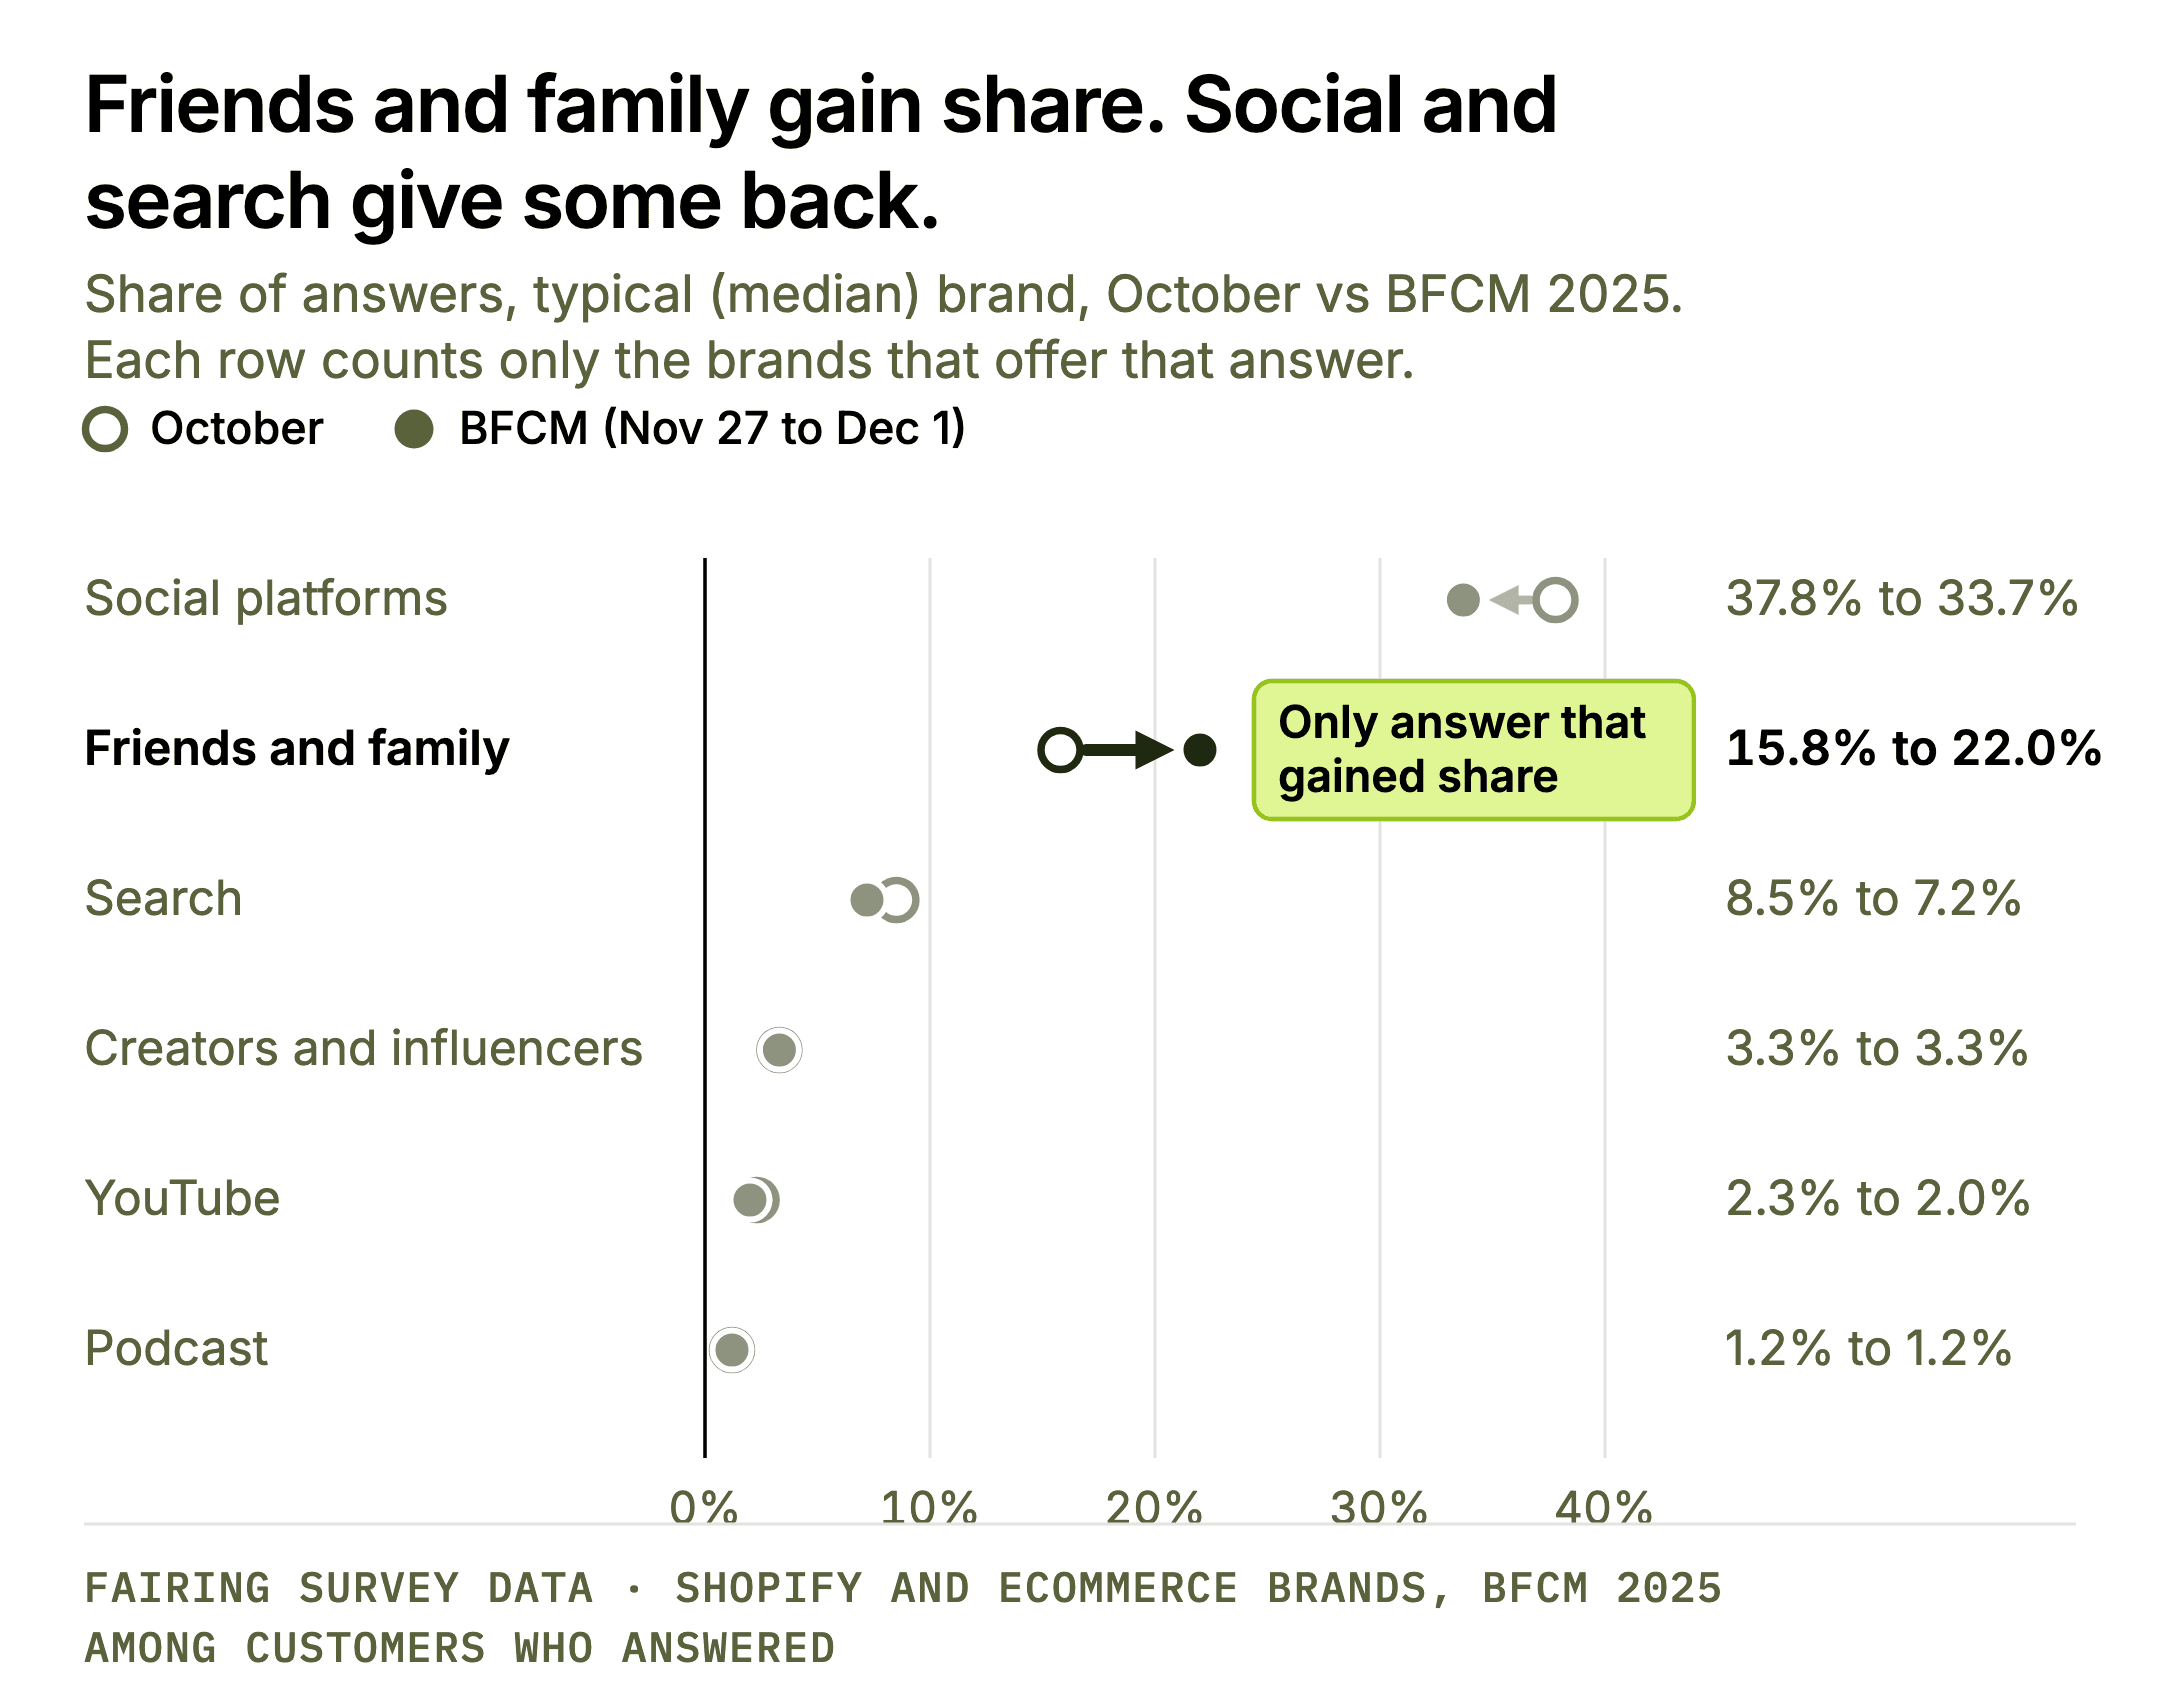
Share of survey answers naming each channel, typical brand
| Customers who named | October | BFCM |
|---|---|---|
| Friends and family | 15.8% | 22.0% |
| Social platforms | 37.8% | 33.7% |
| Search | 8.5% | 7.2% |
| Creators and influencers | 3.3% | 3.3% |
| YouTube | 2.3% | 2.0% |
| Podcast | 1.2% | 1.2% |
Brands whose survey doesn’t offer an option are left out of that row. “Social platforms” is one group (Facebook, Instagram, TikTok, Pinterest, Reddit, X and other social apps, ads and organic together). That’s the method we used for this analysis, and a more detailed platform-level breakdown is coming. We show YouTube on its own because brands list it as its own answer. You could count it as social.
Every channel in this table grew per day. Only friends and family grew faster than the total. Every other channel in the table grew a little slower than all answers at the same brands, so its share slipped. Social’s share rose at only 32% of brands and search’s at 29%: at most brands, both lost share but still gained answers per day.
| Channel | Answers per day, BFCM vs October | All answers, same brands | Brands where share rose |
|---|---|---|---|
| Friends and family | 5.1x | 3.8x | 85% |
| Social platforms | 3.3x | 3.8x | 32% |
| Search | 3.0x | 3.7x | 29% |
| Creators and influencers | 3.6x | 3.9x | 44% |
| YouTube | 3.2x | 3.6x | 40% |
| Podcast | 3.1x | 3.5x | 36% |
Typical brand, among brands whose survey lists each answer. Each row is compared with all answers at those same brands. Influencers, YouTube and podcast are small shares, so slower growth moved their typical share by only 0.1 to 0.2 points.
Do influencer, podcast and YouTube answers surge at BFCM?
No. They hold steady. At the typical brand, the influencer, podcast and YouTube shares of survey answers each stayed within 0.2 points of their own October. Their answers per day grew 3.1 to 3.6 times, a little slower than all answers at the same brands. So plan influencers, podcasts and YouTube to grow with your total BFCM orders, not ahead of them.
Your own last year is your best pacing check
Pace BFCM against yourself, not a benchmark. In our Black Friday and Cyber Monday benchmarks, each brand’s Black Friday order lift tracked its own the year before closely: a correlation of 0.75 (2023 to 2024) and 0.83 (2024 to 2025), where 1.0 would mean the same ranking every year. So set order targets from your own last BFCM, and use last year’s survey answers by channel to plan where those orders will come from: a brand’s BFCM word-of-mouth share was close to its own share the year before (a correlation of 0.86 to 0.88 in our data).
What this means for BFCM 2026:
Expect your social and search share to slip. Social’s share rose at only 32% of brands and search’s at only 29%. For social, that’s almost all word of mouth growing faster. Search slipped a little even setting word of mouth aside.
Judge social on answers per day against your own October pace, and on incrementality tests, not on share. Keep paid social and search running through BFCM.
Set pacing targets from your own last year, not from our numbers.
3. Your UTM tags and your customers disagree all year, and the gap widens at BFCM
The takeaway: At BFCM, most revenue your reports tag to paid search, and more than a quarter of the revenue tagged to paid social, came from customers who say they heard about you somewhere else. At the typical brand, the share of paid-search-tagged dollars from customers who named search fell from about 1 in 6 in October to about 1 in 9 at BFCM. Before your BFCM ROAS shapes 2026 budgets, check Performance Max, your own brand campaigns and non-brand search separately against what your customers say.
The survey and the tag answer different questions. The survey asks how a customer first heard about you. That’s self-reported attribution (the idea behind an attribution survey). A UTM tag records the last link the customer clicked before buying. Both can be true at once: a customer can hear about you from a friend, then click a search ad. So a mismatch doesn’t measure what an ad added (its incrementality). It shows where your reports and your customers tell different stories. The tags come from the landing page Shopify records on each order, the same UTM data most store reports use. Some untagged orders started with a tagged click on an earlier visit.
What counts as paid search and paid social here
Paid search is an order whose UTM tag points to a Google or Bing ad click: a Google, Bing, Microsoft or Yahoo source with a search-type medium (cpc, ppc, paid, sem, shopping or search), or Google’s automatic click ID. Google adds that click ID to every Google Ads click, so this group also includes Shopping, Performance Max and YouTube ads, not only search ads.
Explicitly tagged search is the subset where the brand’s own UTM tag says search (for example medium “cpc” on a Google source), not just Google’s automatic click ID. At the typical brand most paid-search orders carry only the click ID.
Paid social is an order whose UTM tag names a social platform (Facebook or Meta, Instagram, TikTok, Snapchat, Pinterest, Reddit or AppLovin) and a paid medium (paid, cpc, ppc, cpm, ads or native).
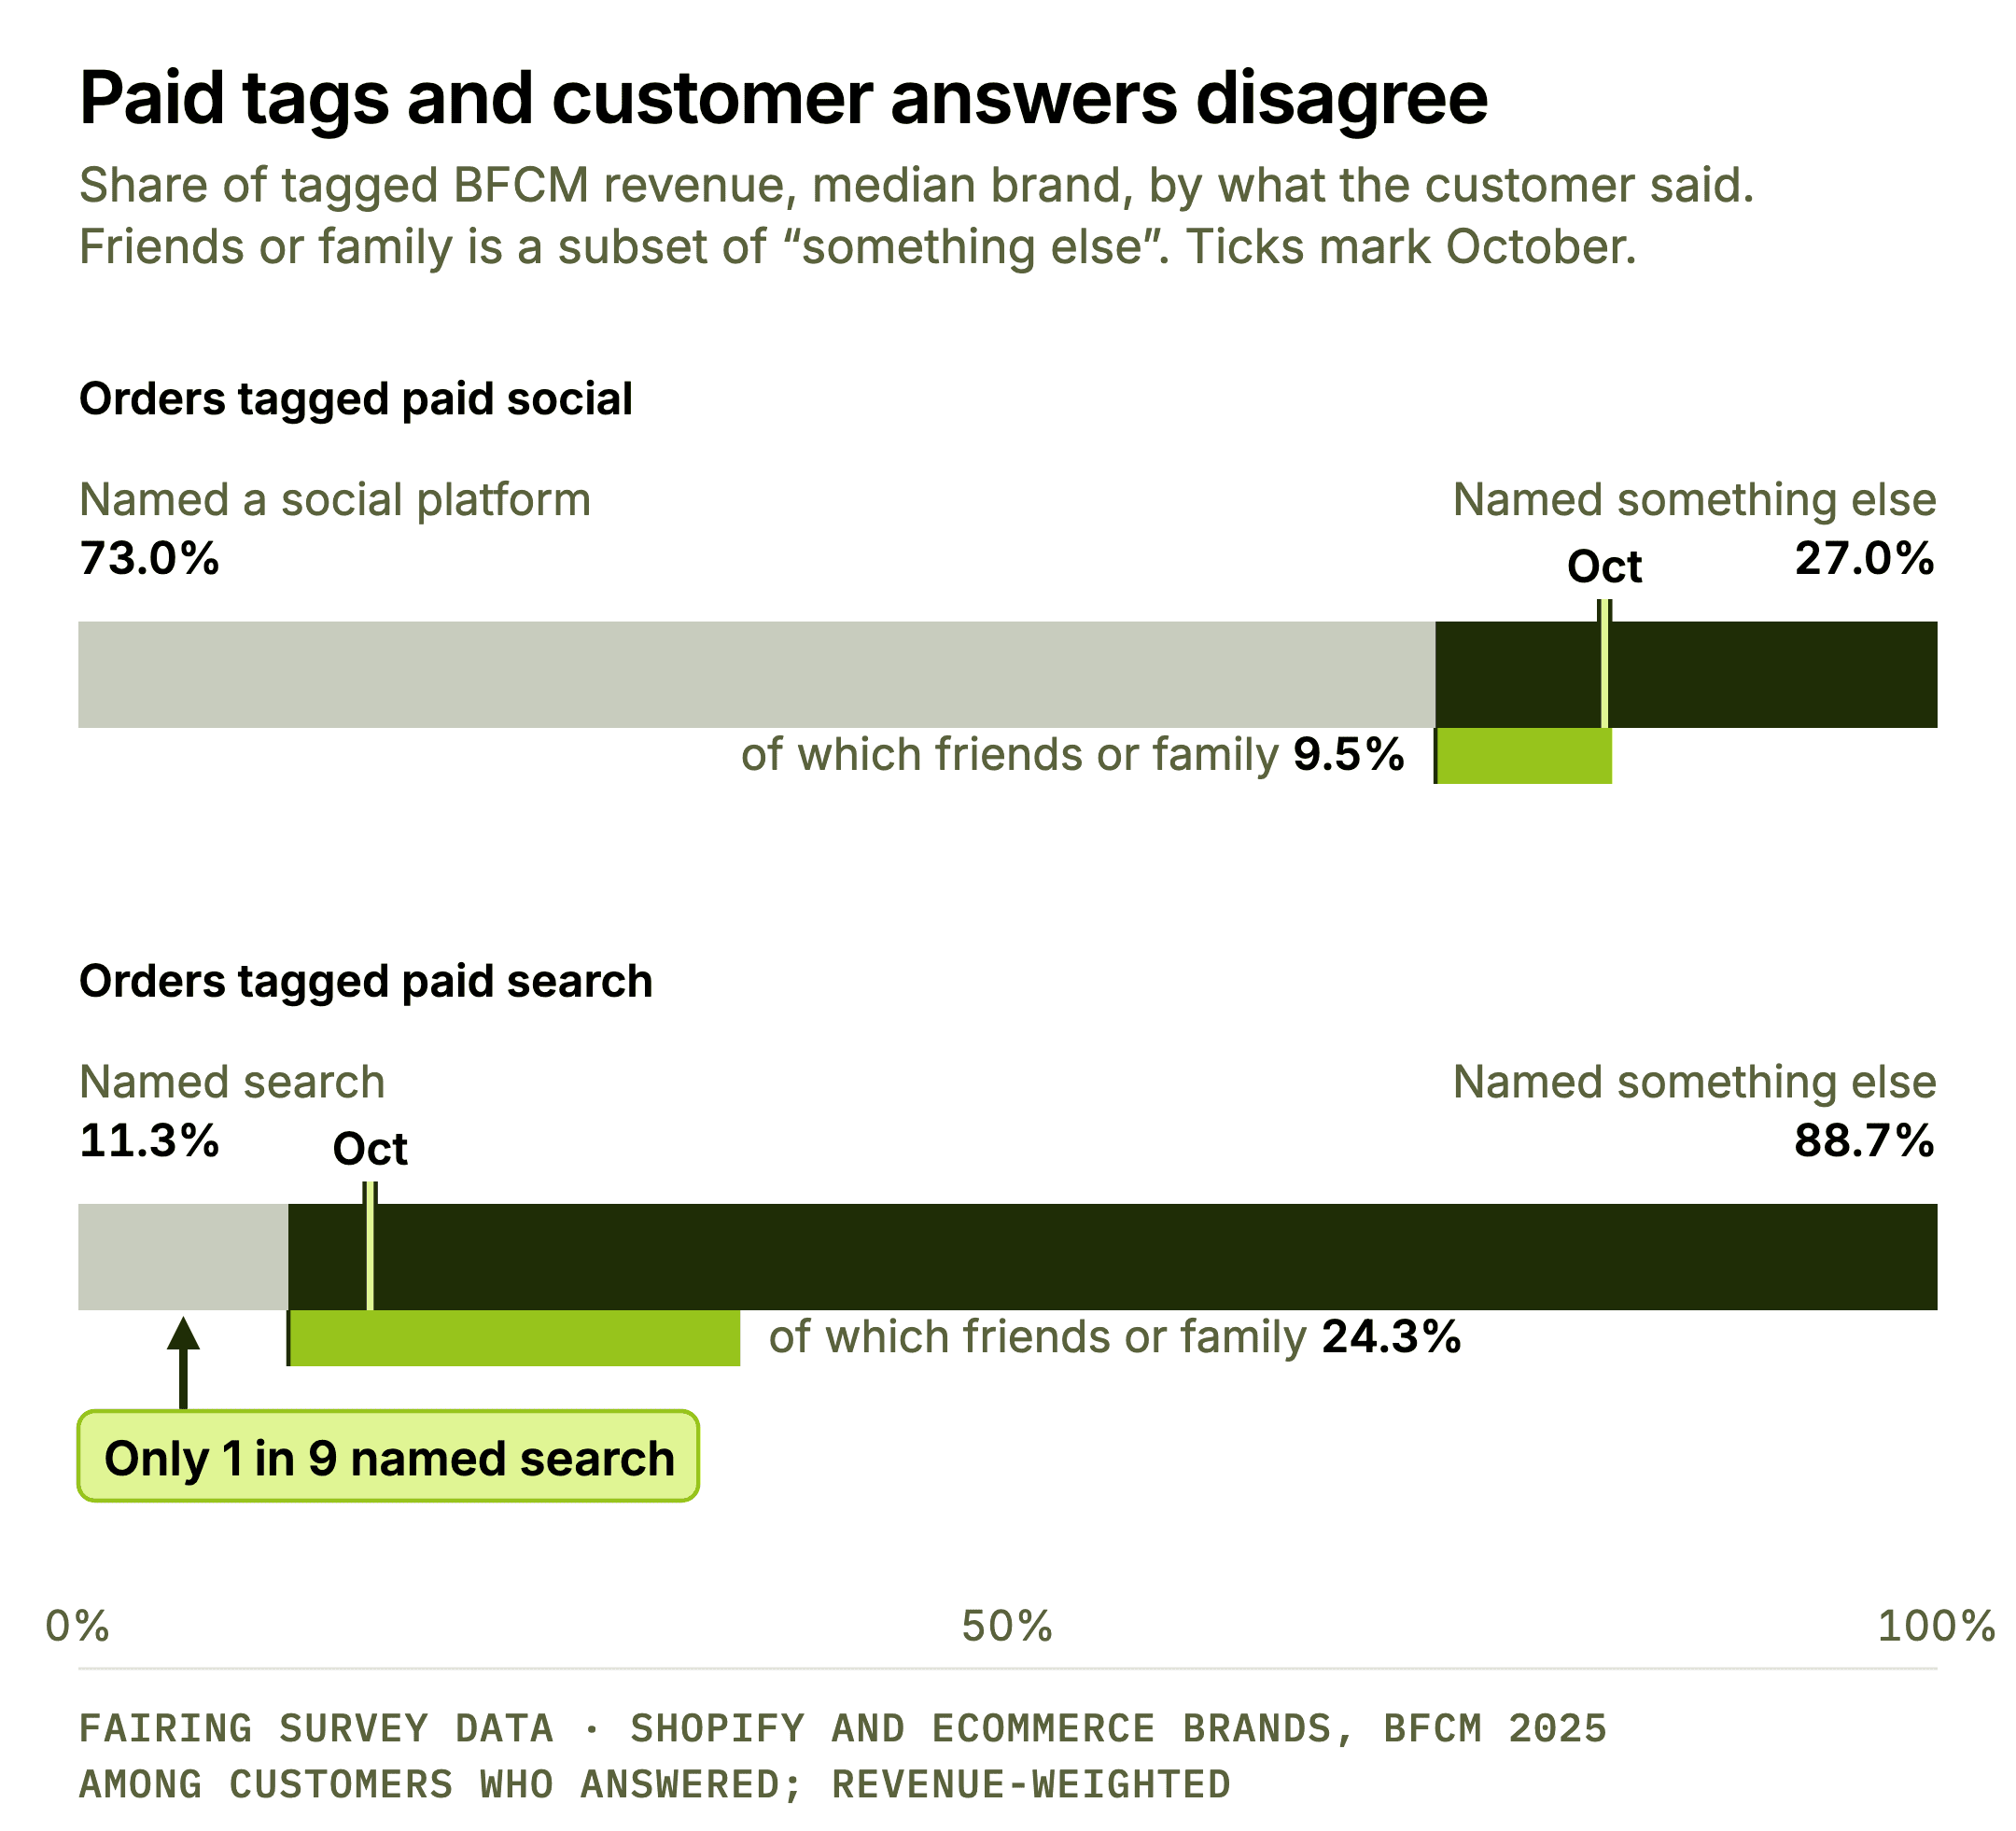

The chart in plain numbers: share of BFCM revenue from UTM-tagged orders, by what the customer named, typical brand.
Paid-social-tagged orders: 73.0% from customers who named a social platform, 27.0% from customers who named something else (including 9.5% who named friends or family).
Paid-search-tagged orders: 11.3% named search, 88.7% something else (including 24.3% friends or family).
What do paid-social UTM tags miss at BFCM?
More than a quarter of paid-social-tagged revenue, at the typical brand. At BFCM, 27% of revenue from paid-social-tagged orders came from customers who named something other than a social platform. In October it was 18%. The share naming friends or family rose from 4.7% in October to 9.5% at BFCM. Brands vary widely: at BFCM, half fall between 17% and 42%. So measure your own before you discount paid social’s reported revenue. An answer that disagrees with the tag doesn’t prove the ad did nothing.
What do paid-search UTM tags miss at BFCM?
Most of it, and more than in October, at the typical brand. The share of paid-search-tagged dollars from customers who said they found the brand through search fell from about 1 in 6 in October to about 1 in 9 at BFCM. Even on explicitly tagged search alone, it fell from about 1 in 6 to about 1 in 8, so the gap isn’t only Google’s click ID catching non-search ads. The share naming a friend or family member rose from 17.6% in October to 24.3% at BFCM. Most customers who arrived on a paid-search click said they first heard about the brand somewhere else, from social or a friend or family member about twice as often as from search. That’s consistent with paid search catching the last click of customers who already knew the name. We can’t separate branded from non-branded search, or search ads from Shopping, Performance Max and YouTube placements, which share the same Google click tag, so we aren’t saying search took credit it didn’t earn. If you run branded search, non-branded search and Performance Max as separate campaigns, run the check in the box below on each.
Do word-of-mouth customers show up in UTM tracking?
Mostly not. At the typical brand:
About two-thirds of customers who named friends or family arrived with no UTM tag, so your store’s UTM report can’t tie their orders to any campaign.
About 1 in 5 arrived on a paid-tagged link, mostly paid search: about 1 in 7 of all friends-and-family customers came on a paid-search click. So paid search gets the last-click credit for some customers who say a friend sent them.
Untagged orders aren’t all word of mouth. Of orders with no UTM tag, 29% named a social platform and about a quarter named friends and family.
Direct orders (no UTM tag and no referring site, what most reports call direct traffic) named friends or family 7 points more often than the same brand’s other orders at BFCM. In October the gap was 4 points. It held at 83% of brands. That fits: someone who hears your name and types it in leaves no tag.
So a BFCM jump in direct or untagged traffic is partly word of mouth.
Do email and text tags catch email and text customers?
Often not. At the typical brand, about half of the customers who said an email or text brought them in had no email or SMS tag on their order. October looked the same, so this gap runs all year. So your email and SMS reports likely miss about half the customers who credit those channels. The data can’t say why. Start by checking that every Klaviyo flow and campaign link, and every SMS link, carries a UTM source and medium, and that your SMS tool’s link shortener keeps them. This covers brands where at least 30 customers named email or text.
A year-round gap that widens at BFCM
These gaps exist all year, and they widen at BFCM. In October, about 1 in 6 paid-search-tagged dollars came from customers who named search, and 18% of paid-social-tagged revenue named something other than social. Two things don’t change: about half of email and text customers have no email tag in both months, and about 1 in 6 to 1 in 7 word-of-mouth customers arrive on a paid-search click. What grows at BFCM is the group behind it: more of your revenue comes from customers who credit friends and family, behind a tag that credits something else.
How to compare your tags with your answers
Use the Fairing MCP, which lets you ask questions of your Fairing data from an AI tool such as Claude or ChatGPT, to pull every answered order for Oct 1 to 31 and for Thanksgiving to Cyber Monday, with the UTM source and medium on each order.
Group orders by UTM tag: paid social, paid search, email or SMS, no tag.
In each group, find the share of orders and revenue from customers who named a different channel than the tag. Leave vague answers (“online”, “saw an ad”) out of the mismatch.
Compare the two windows. The October gap is your year-round gap. The change at BFCM is the holiday effect.
Read a mismatch as “the click isn’t where they found you”, not as wasted spend.
What this means for BFCM 2026: At BFCM, last-click reports hand paid media more credit than in October for customers who say they found you another way. Check that credit against your survey answers before you judge or split BFCM budgets.
Don’t move budget on last-click tags alone.
Before you set the split, compare each paid tag with what those customers said, in October and at BFCM.
Read the October gap as your year-round gap, and the change at BFCM as the holiday effect.
4. Fewer BFCM orders carry a checkout code, so a code report sees less of BFCM
The takeaway: At the typical brand, about 37% of answered orders carried a checkout code in October and about 18% at BFCM, which fits brands switching to sitewide offers that apply without a code. Only about a third of customers who named an influencer used a code at BFCM, down from more than half in October, so influencer code reports miss the most then. Podcast and CTV code reports likely miss customers the same way. Keep the codes live, and let the survey answer credit the customers who skip them.
Fewer BFCM orders carried a checkout code. At the typical brand, about 37% of answered orders had a checkout code in October and about 18% over BFCM. Brands split:
At more than a quarter of brands, under 5% of BFCM orders carried a checkout code.
At nearly 4 in 10, the share of orders with a code rose.
That fits some brands switching to sitewide offers that apply without a code. Automatic discounts don’t show up as codes, so we can’t confirm it.
Codes catch some influencer customers, and fewer at BFCM. Year-round, orders with a discount code named an influencer about 0.8 points more often than orders without one, at 66% of brands that offer an influencer answer. But at BFCM, most customers who named an influencer checked out without a code. About a third used one at the typical brand, down from more than half in October. So at BFCM, an influencer code report misses most of the customers who credit influencers.
What this means for influencer reporting
Influencer customers didn’t go away at BFCM. At the typical brand, about 3.3% of customers named a creator or influencer in October, and the same at BFCM. What changed is how they checked out: about 36% used a code at BFCM, down from about 57% in October. So a report built on influencer codes undercounts creators most at BFCM, while the share of customers crediting them holds steady. At BFCM, judge creators on what customers say as well as on code redemptions.
At BFCM, orders without a code leaned toward friends and family. At the typical brand, 23.6% of orders without a code named friends or family, against 20.0% of orders with one. Compared inside each brand, the gap was about 2 points. In October there was no gap: 15.9% without a code, 15.8% with one. Read the BFCM gap as a direction, not a precise size.
| Share naming friends or family | Orders with a code | Orders without a code |
|---|---|---|
| BFCM | 20.0% | 23.6% |
| October | 15.8% | 15.9% |
Two limits. First, “code” here means a code typed at checkout. Automatic discounts count as no code, and the BFCM no-code group includes sitewide-sale shoppers and gift buyers. Second, this shows that orders without a code lean toward friends and family. It doesn’t show that codes miss word-of-mouth customers.
What this means for BFCM 2026: If your podcast, influencer or CTV campaigns run on promo codes, BFCM is when that report misses the most: most customers who credit an influencer check out without a code. A post-purchase survey asks every buyer, code or no code, so it credits these channels where the code report goes quiet.
Don’t compare creator code redemptions between October and BFCM. Fewer orders carry a code at BFCM, so redemptions fall even when the share of customers crediting creators holds steady.
Keep influencer codes live.
Add a way in that needs no typing: a creator-specific discount link (it applies the code for the customer, so it still shows up in your code report) or a referral link.
Make sure creator codes stack with, or beat, your sitewide BFCM offer, or creator customers will skip them.
Judge these channels on what customers say as well as on code redemptions. See how to measure influencer sales beyond codes.
For how discount code use shifts across the BFCM weeks, see the discount code section of our Black Friday and Cyber Monday benchmarks.
5. How to plan BFCM 2026: check your tags, start word of mouth early, make creator codes easy to use
The takeaway: Before you set your BFCM 2026 budget, compare your UTM tags with your survey answers, give influencers a discount link that applies their code, and if you run a referral campaign, have it live by early November (Nov 1).
Word of mouth builds from early November, and your tags often credit those orders to another channel or to no campaign at all. Start with the checklist, then the three moves behind it.
Do this before November
Check that your survey lists “friends or family” as an option. Brands without the option can’t see this shift, and our numbers only count brands that offer it.
Get your “How did you hear about us?” question live now, so you have normal weeks to compare BFCM against.
Add a checkout-experience question now, to get a baseline. On our Black Friday and Cyber Monday benchmarks, when asked, about 9% of buyers say something went wrong between finding you and paying. A question like that needs weeks of normal data under it, so a BFCM spike stands out. The setup is in our BFCM CRO checklist for catching checkout bugs before code freeze.
Run the five steps in section 3 on your survey answers from last October and last BFCM. The gap you find is yours, not ours.
Check that every email flow, campaign and SMS link carries a UTM source and medium, and that your link shortener keeps them. At the typical brand, about half of the customers who credit email or text have no email or SMS tag on their order.
If you run a referral offer, a shareable post-purchase moment or a gifting message, have it live by early November (Nov 1).
Next to your influencer codes, add a creator-specific discount link that applies the code for the customer, so it still shows up in your code report. Make sure creator codes stack with, or beat, your sitewide BFCM offer.
From early November, check your word-of-mouth share against your own October share every Monday. Most brands see it climb whether or not they run a campaign (at large brands, about 1.4 to 2.0 points above October by Nov 9 to 16), so compare against that climb, not against zero. To see what your referral offer adds, track its own referral-link orders. Keep the campaign live through mid-December, and read your last-click reports knowing they under-credit word-of-mouth orders.
Compare your own tags with your own answers before you set your BFCM budget split. Use the Fairing MCP to pull last October’s and last BFCM’s answers with the UTM source and medium on each order. For each paid tag, check what share of orders and revenue named a different source (the steps are in section 3).
Why: don’t cut your paid-social numbers by our 27%. It’s a typical-brand figure with a wide spread (half of brands fall between 17% and 42%), and a mismatch between a last click and a survey answer doesn’t measure what the ad added.
If you run a referral or gifting campaign, time it to the build. Have your referral offer, shareable post-purchase moment or gifting message live by early November (Nov 1) and running through mid-December. For how to track it, see measuring word of mouth.
Why: the word-of-mouth share is already about 4 points above October in the days before Thanksgiving (Nov 24 to 26) and peaks Dec 8 to 10, so a campaign that starts on Black Friday misses the build. (The daily timing comes from brands with enough answers per day to chart, 1,000+ in October.) It repeated in 2023, 2024 and 2025 and rose in every category. Apparel should expect a bigger lift than food and drug. Brands with a visible referral program saw about the same rise as brands without one, so the campaign rides the rise rather than causing it. Count its own referral-link orders to see what it adds.
Keep influencer codes live and make them easy to use. Keep influencer-specific codes through BFCM, give each creator a discount link that applies their code (it still shows up in your code report), and make sure the code stacks with, or beats, your sitewide offer. A referral link also gives you a count of referred orders, and the survey answer tells you where the rest heard about you.
Why: a code report only sees checkout codes. At BFCM, fewer than 1 in 5 answered orders at the typical brand carried a checkout code, so most orders, word of mouth included, never show up in it.
To see how long the BFCM run lasts and whether your own order volume is on pace, use our Black Friday and Cyber Monday benchmarks.
October paid social and the BFCM rise: a correlation only
The quarter of brands with the highest share of paid-social-tagged orders in October saw their friends-and-family share rise about 3 points more at BFCM than the quarter with the lowest, after adjusting for brand size, category and October friends-and-family share. That’s consistent with paid feeding word of mouth, but it’s a correlation, not proof. We had no spend data, so the measure is each brand’s share of paid-social-tagged orders. Brands that run a lot of paid social also differ in product, audience and growth stage. The practical reading is modest: keep October paid social running, and don’t assume word of mouth arrives for free.
Word of mouth sits flat through October, then starts climbing in the first week of November. (The daily timing comes from brands with enough answers per day to chart, 1,000+ in October.) Orders step up then too: about 10% on November 1st itself, in each of the last three years (Black Friday and Cyber Monday benchmarks). Get your post-purchase survey live in October, while you still have normal weeks to measure BFCM against. Book a demo.
Frequently asked questions
How do “How did you hear about us?” answers change during BFCM?
Word of mouth is the biggest shift. At the typical brand, the share of customers who named a friend or family member rose from 15.8% in October to 22.0% over BFCM (Thanksgiving to Cyber Monday). Social and search take a smaller share of answers but are still named more often per day than in October, and influencer, podcast and YouTube shares hold steady.
When does word of mouth peak around Black Friday?
After BFCM. The friends-and-family share starts climbing in early November. It’s about 4 points above October in the days before Thanksgiving and 5.5 points above on Black Friday, then peaks on Dec 8 to 10, more than a week after Cyber Monday. (The daily timing comes from brands with enough answers per day to chart, 1,000+ in October.)
Why does UTM tracking miss word-of-mouth customers?
A UTM tag records the last link clicked, and many customers who heard about you from a friend never click a tagged link. About two-thirds of customers who named friends or family arrived with no UTM tag, so your store’s UTM report can’t tie those orders to any campaign. The tag and the answer measure different things, so the gap doesn’t measure incrementality.
Do discount codes show where customers found you?
Partly. Orders with a code named an influencer about 0.8 points more often than orders without one, so codes catch some influencer customers. But at BFCM only about a third of customers who named an influencer used a code, down from more than half in October, and orders without a code named friends and family about 2 points more often than orders with one. Codes here are checkout codes only, so automatic discounts look like no code.
Does word of mouth increase during Black Friday?
Yes. At the typical brand, the share of customers who named a friend or family member rose from 15.8% in October to 22.0% over BFCM (Thanksgiving to Cyber Monday), and it rose at 85% of brands. The same rise showed up in 2023, 2024 and 2025. It starts in early November and stays up after BFCM, peaking on Dec 8 to 10 at large brands.
Is the BFCM word-of-mouth rise just fewer people answering the survey?
No. At BFCM, about 2 points fewer first-time customers answer the question at the typical brand, which explains only about 0.3 of the 4.6-point word-of-mouth rise. Friends-and-family answers also grew about 30% faster than orders, and the lift was just as large at brands whose answer rate held steady.
Should I cut paid social if its share falls at BFCM?
No. Customers still named social platforms more often at BFCM: about 3.3 times as many answers per day as in October at the typical brand, against 3.8 times for all answers. Friends and family grew faster, so social’s share fell. A smaller share is not evidence a channel stopped working. Judge spend on your own incrementality tests.
When should I start my BFCM word-of-mouth push?
By early November (Nov 1). The friends-and-family share is already about 4 points above October in the days before Thanksgiving and peaks Dec 8 to 10, so a referral or gifting campaign that starts on Black Friday misses the build. (The daily timing comes from brands with enough answers per day to chart, 1,000+ in October.)
How does self-reported attribution compare with UTM tracking at BFCM?
Self-reported attribution asks customers how they first heard about you, usually with a post-purchase survey question like “How did you hear about us?”. A UTM tag records the last link clicked before the order. At BFCM the two disagree more than usual: at the typical brand, only about 1 in 9 dollars from paid-search-tagged orders came from customers who said they found the brand through search, down from about 1 in 6 in October.
Why do so many BFCM orders show up as direct?
Some come from customers who heard about you from someone and typed your name in, which leaves no UTM tag. At the typical brand, direct orders (no UTM tag and no referring site) named friends or family 7 points more often than the brand’s other orders at BFCM, up from 4 points in October. Untagged orders aren’t all word of mouth, though: about 29% of orders with no UTM tag named a social platform.
About the data
Who’s in it. Shopify and ecommerce brands running a Fairing HDYHAU survey (“How did you hear about us?”) during BFCM 2025 (internal test shops excluded). The main set is 800+ Shopify and ecommerce brands with 100+ “How did you hear about us?” answers in both October and BFCM 2025. A channel counts for a brand only if the brand offers that answer. Comparisons inside a brand (by UTM tag, discount code or customer type) need a minimum number of orders on each side, so they use the brands that clear that bar. We give the rest as percentages of brands.
Windows. October is Oct 1 to 31, 2025, the normal-month baseline. BFCM is Thanksgiving through Cyber Monday, Nov 27 to Dec 1, 2025. Black Friday falls on a different date each year (Nov 24 in 2023, Nov 29 in 2024, Nov 28 in 2025), so anchoring on Thanksgiving through Cyber Monday compares the same five days every year. The daily view covers the season, Nov 1 to Dec 20, 2025, with October weeks for reference, and uses large brands with 1,000+ October answers. The mid-December figure covers Dec 11 to 20. “The days before Thanksgiving” in the daily view means Nov 24 to 26. Dates use the shop’s local day.
Which brands. Comparisons of UTM tags, discount codes, sale days and reorders use Shopify brands only. Survey-answer shares (word of mouth, channel shares, pace) use all brands.
Product categories. Categories are the ones brands chose when they set up Fairing. Supplement brands mostly chose Health & Beauty (about 4 in 5); most of the rest chose Food & Drug.
Among customers who answered. Most brands ask this question only of first-time buyers, so at the typical brand almost all answers (about 96%) come from first orders. Read “customers” and “orders” on this page as mostly first-time customers and their orders, and revenue and code shares as shares of answered orders. Not every customer answers, and people who answer can differ from people who don’t. At BFCM, slightly fewer first-time customers answer: the answer rate slips by about 2 points at the typical brand (see our BFCM benchmarks). That doesn’t explain the friends-and-family rise. It was just as large at brands whose answer rate held steady, and even if every customer who skipped the question would have named another channel, the typical brand’s friends-and-family share would still be clearly up.
*We counted a brand as having a visible referral program if at least 5 answered orders between Sep 30 and Dec 3 came through a referral program we could detect: a UTM tag from a referral platform, a referral campaign or medium tag, or a randomly generated referral code such as FRIEND-AB12CD. Programs whose links carry no tag, and whose rewards apply automatically, don’t show up. Some brands with a program therefore sit in the comparison group, which would make the two groups look more alike than they really are.