Benchmarks / Black Friday statistics
Black Friday statistics and benchmarks for 2026
3 years of order data from 2,200+ established Shopify and ecommerce brands
Matt Bahr, CEO & Co-Founder · Published October 2026 · How we measured →
This is a long report. Copy the prompt above into any AI tool to pull out what matters for your brand.
Most BFCM plans I see start from one number: Black Friday will be some multiple of a normal day. Inventory gets ordered against it, the CS schedule gets built around it, and the ad budget gets split on it. We went through three years of order data from 2,200+ Shopify and ecommerce brands on Fairing to check that number. The median brand did 4.6x its October daily orders on Black Friday from 2023 to 2025, and the middle half of brands landed anywhere from 2.5x to over 8x. That range is the point: the number worth planning around is your own. Measure it the same way, and the pacing table at the end of this post lets you check it week by week.
Key takeaways
On this page
Part 1: The number to plan for
Part 2: The calendar
Part 3: Customers and measurement
Part 4: Putting it to work
1. The average Black Friday describes almost nobody, so forecast from your own
Unless stated otherwise, every number below is for the median brand, shown as a multiple of that brand’s own average daily orders in October. “Extra orders” are orders above that October average. A brand that averages 100 orders a day in October and does 460 on Black Friday has 360 extra orders that day.
Black Friday’s median is 4.6x October. Your own last year is a far better guide than that.
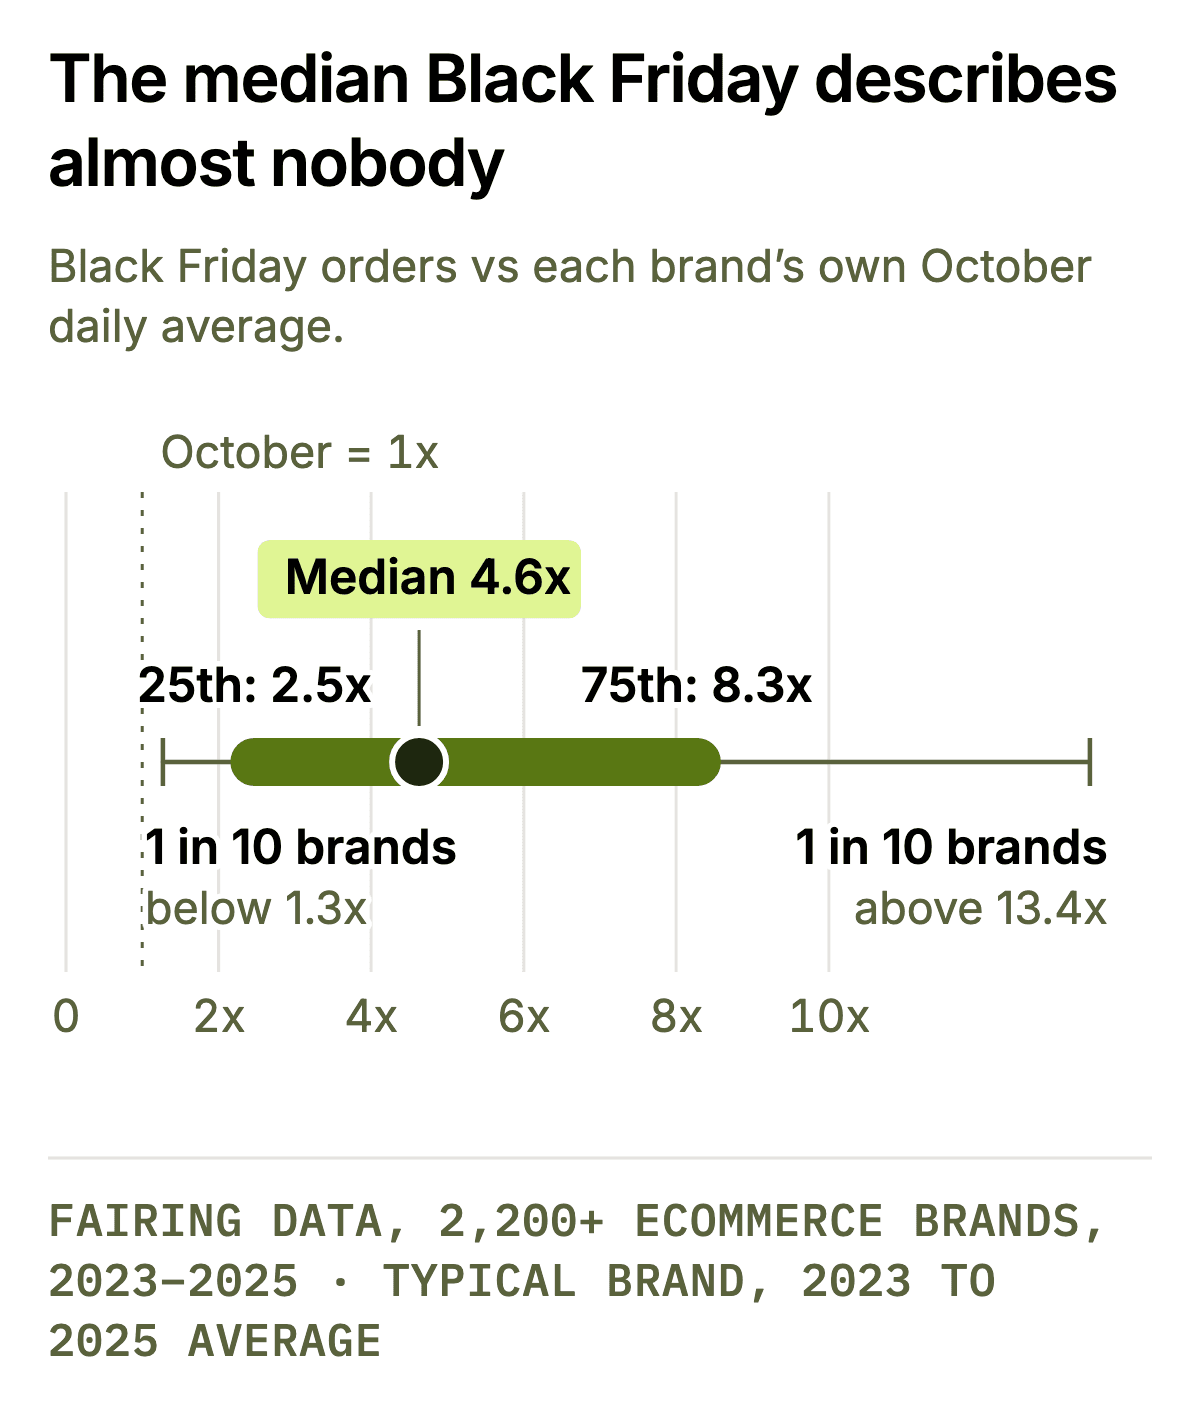
The median is 4.6x. The range is huge.
Divide a brand’s Black Friday orders by its own October daily average, and the median brand lands at 4.6x. That’s the average of the 2023, 2024 and 2025 medians, and each year is shown below. The middle half of brands ranges from about 2.5x to over 8x. About one brand in five does less than 2x, and about as many do 10x or more.

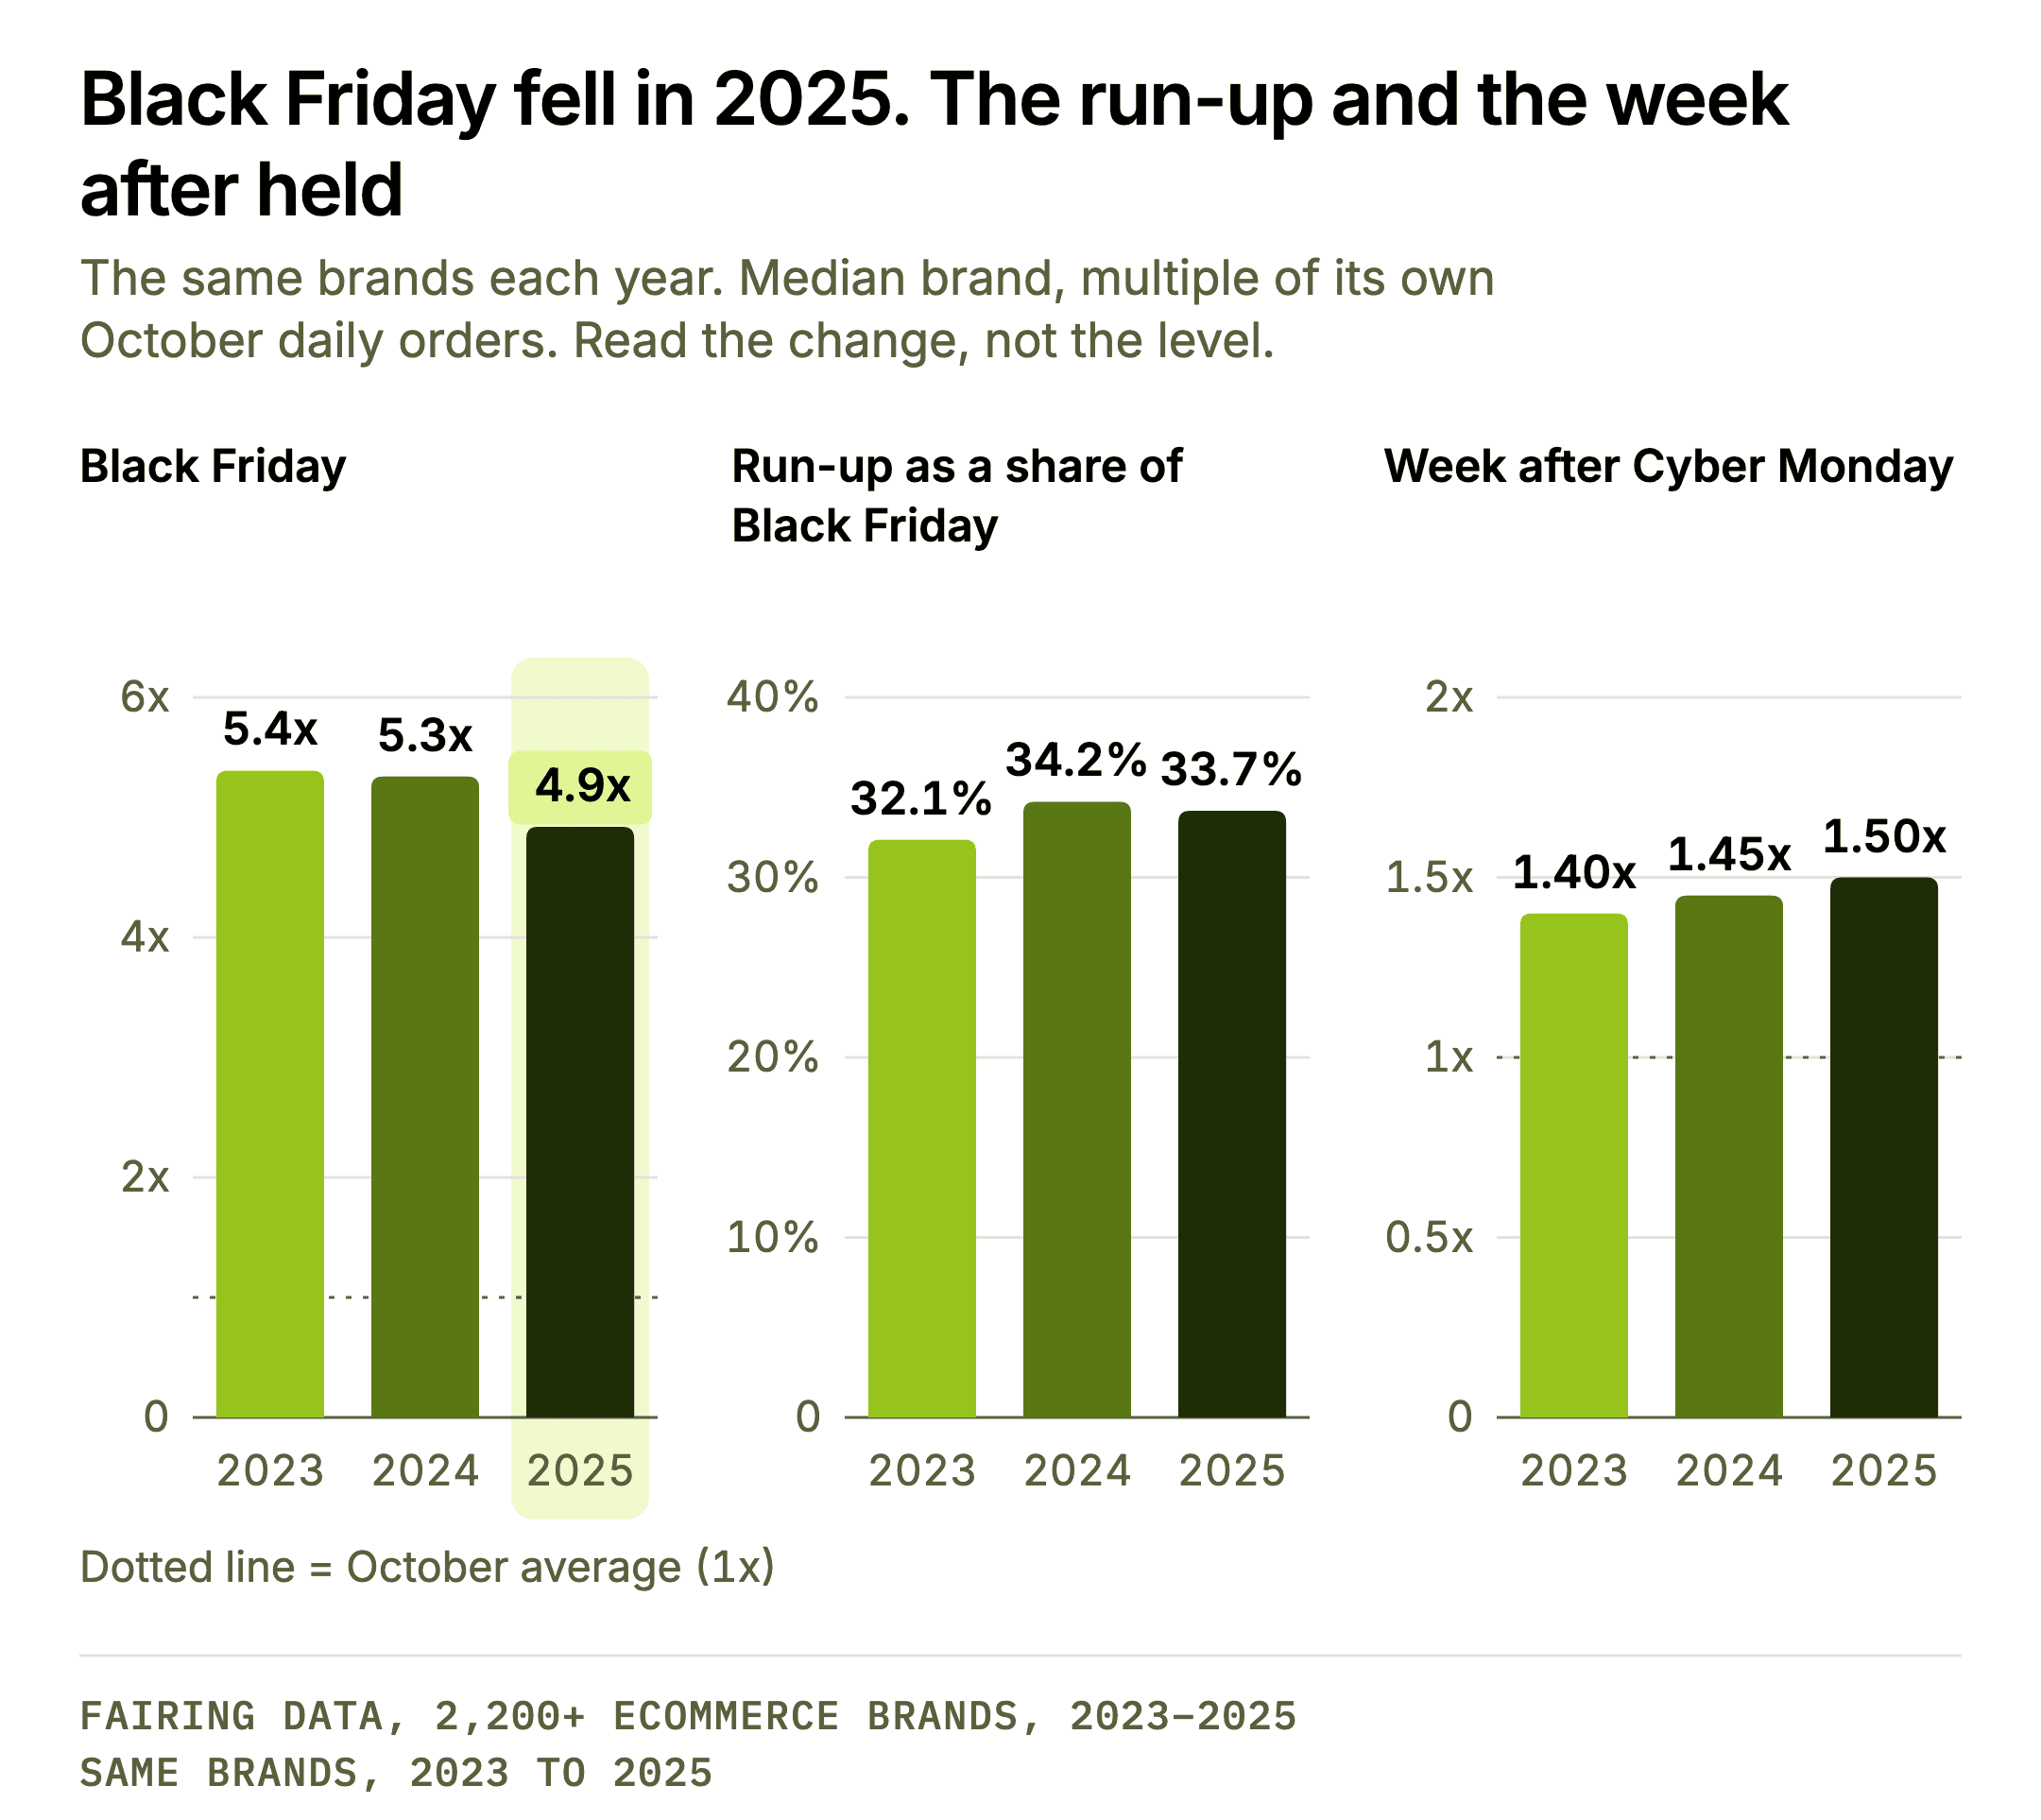
Black Friday fell in 2025. The run-up and the week after held.
Compared with its own 2024, the typical brand’s Black Friday was about 7% lower in 2025, while the weeks around it held.
The median brand’s Black Friday was 4.78x October in 2023, 4.80x in 2024 and 4.33x in 2025. Comparing each brand with its own 2024:
The typical brand was down 7% (95% confidence interval, 4% to 11% down).
58% of brands fell.
That’s a real drop in orders, about 6% fewer on the day, with October flat.
From 2023 to 2024 there was no real change. Following the same brands each year, the rest of the season held: the week after Cyber Monday ran 1.40x, 1.45x and 1.50x, and the run-up (16 to 2 days before Black Friday) grew relative to Black Friday in 2024 and held in 2025.
The chart below follows the same brands each year, so the years compare like for like. Its levels run higher than the all-brand median, so read the change from year to year, not the level.
Size explains part of the spread
Bigger brands spike harder. The smallest quarter of brands (about 17 orders a day in October) does 4.0x on Black Friday; the top 5% (about 1,400 a day) does 6.0x. Their Cyber 5 average (Thanksgiving through Cyber Monday) rises the same way, from 3.0x to 4.0x. It holds within apparel alone, at about 4.8x for the smallest quarter and about 6.8x for the largest.
Size changes the peak, not the aftermath. The week after Cyber Monday (about 1.35x) and December gifting (about 1.24x) look the same for the smallest quarter of brands (about 17 orders a day) and the largest quarter (about 377 a day).
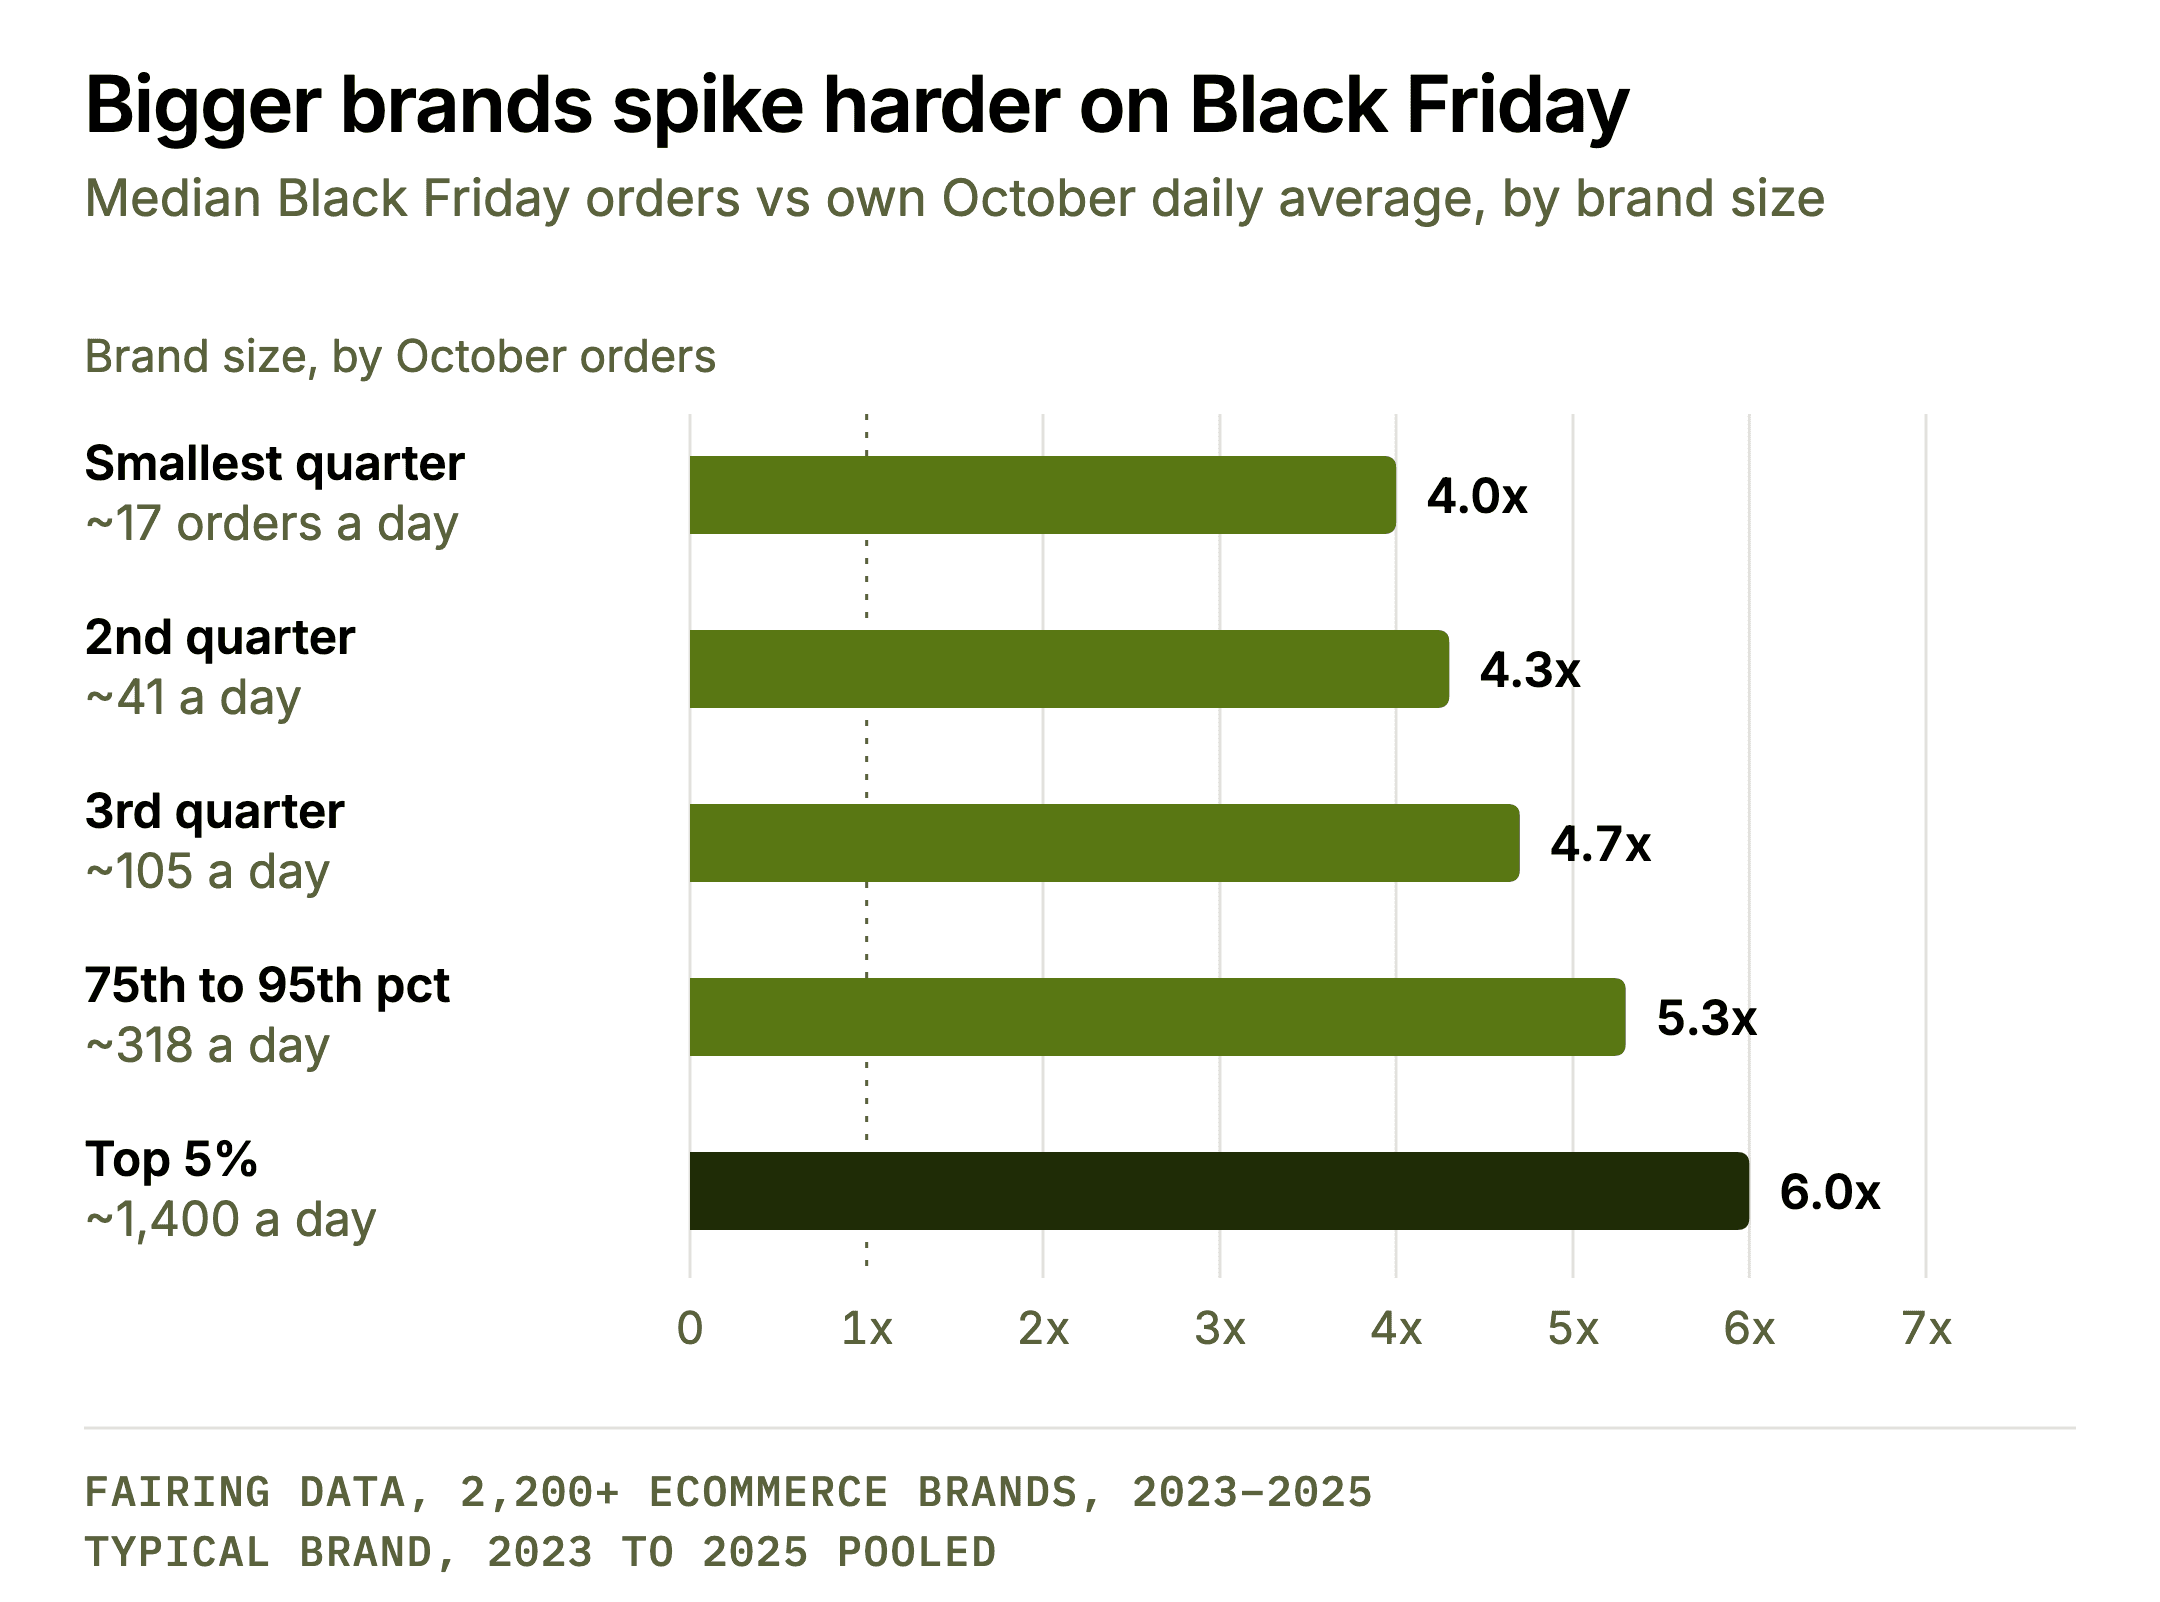
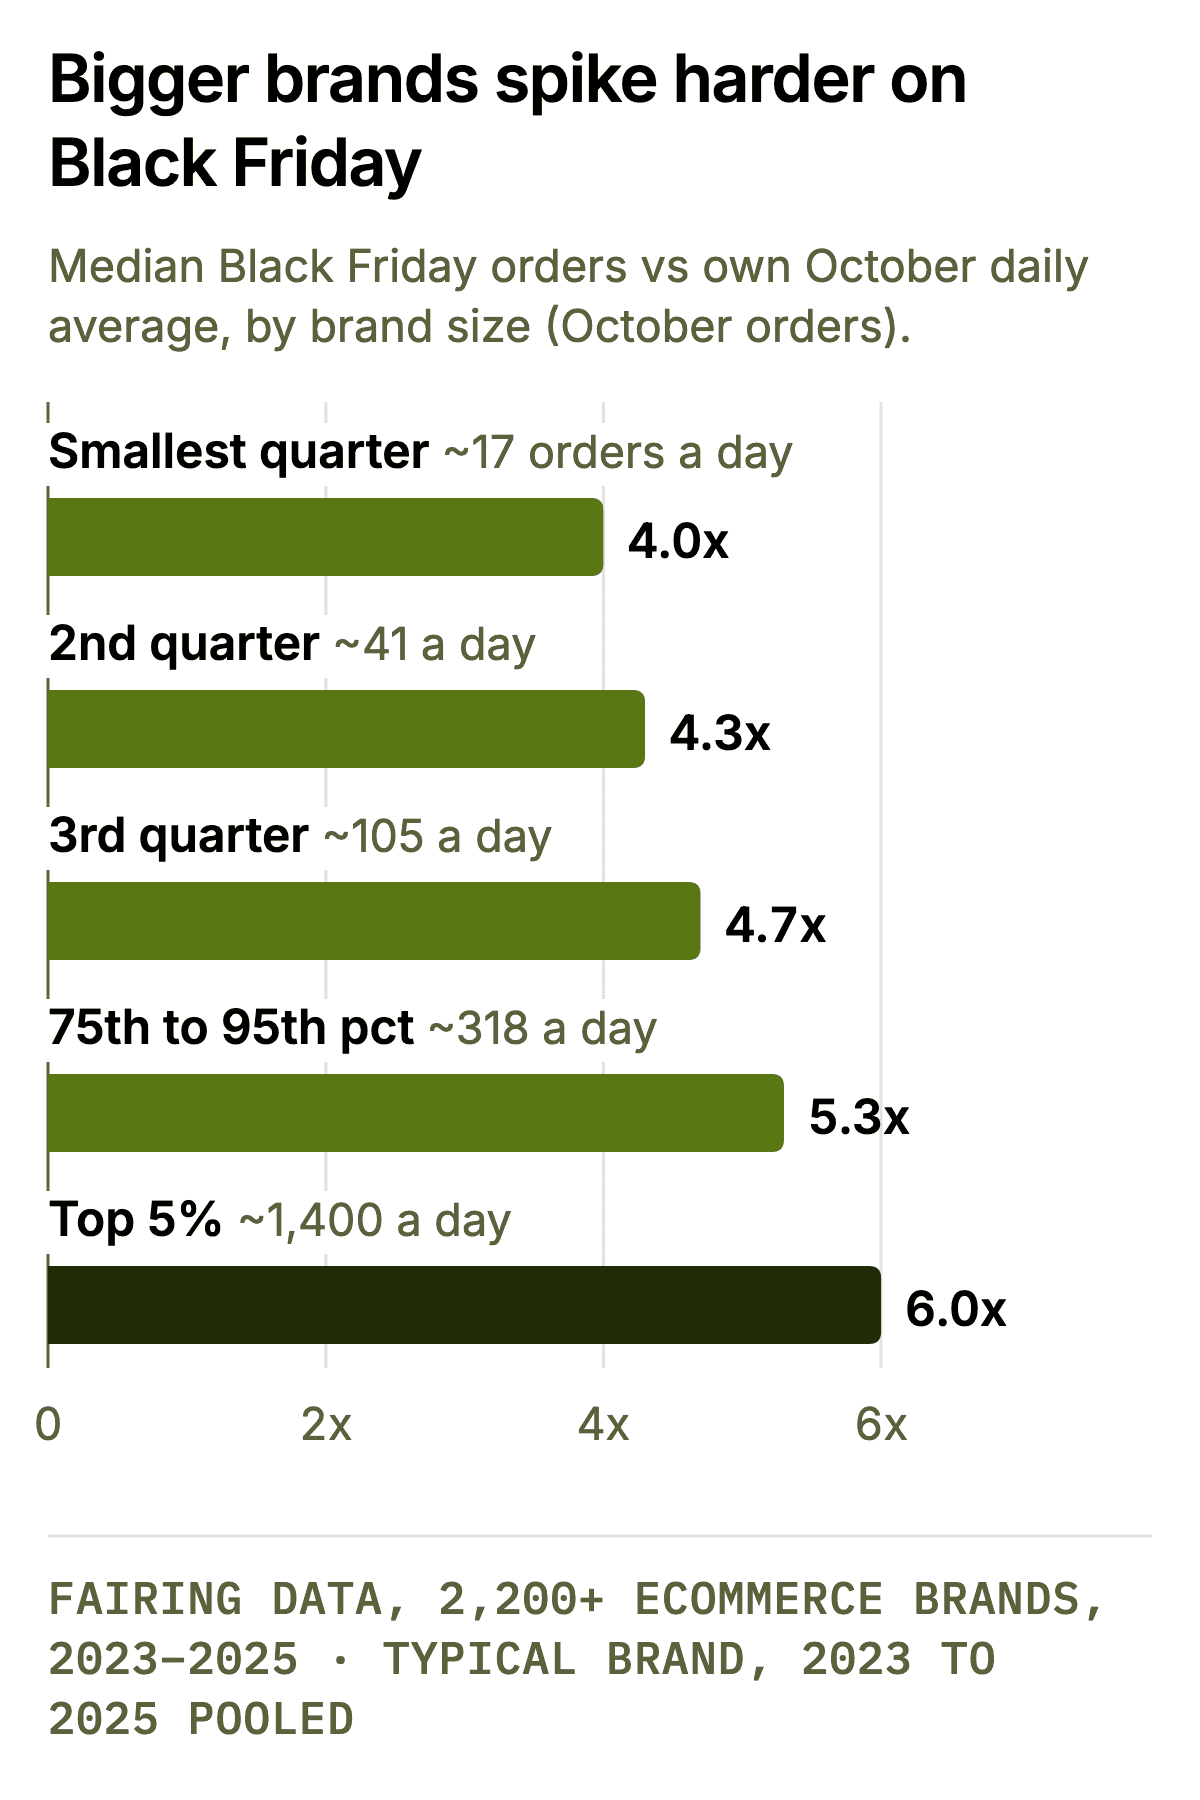
Where you sell matters too
Black Friday lift varies by shop currency, and the gap held every year:
US dollars: about 5.1x.
Euros: about 3.6x.
Pounds: about 3.2x.
Canadian dollars: 6.6x, the highest of all.
Canadian and Australian brands also get a real Boxing Day, about 2x October on Dec 26. For US and UK brands it’s close to a normal day. Shop currency stands in for market here, so treat the Canadian and Australian figures as directional.
Your own last year is the best forecast
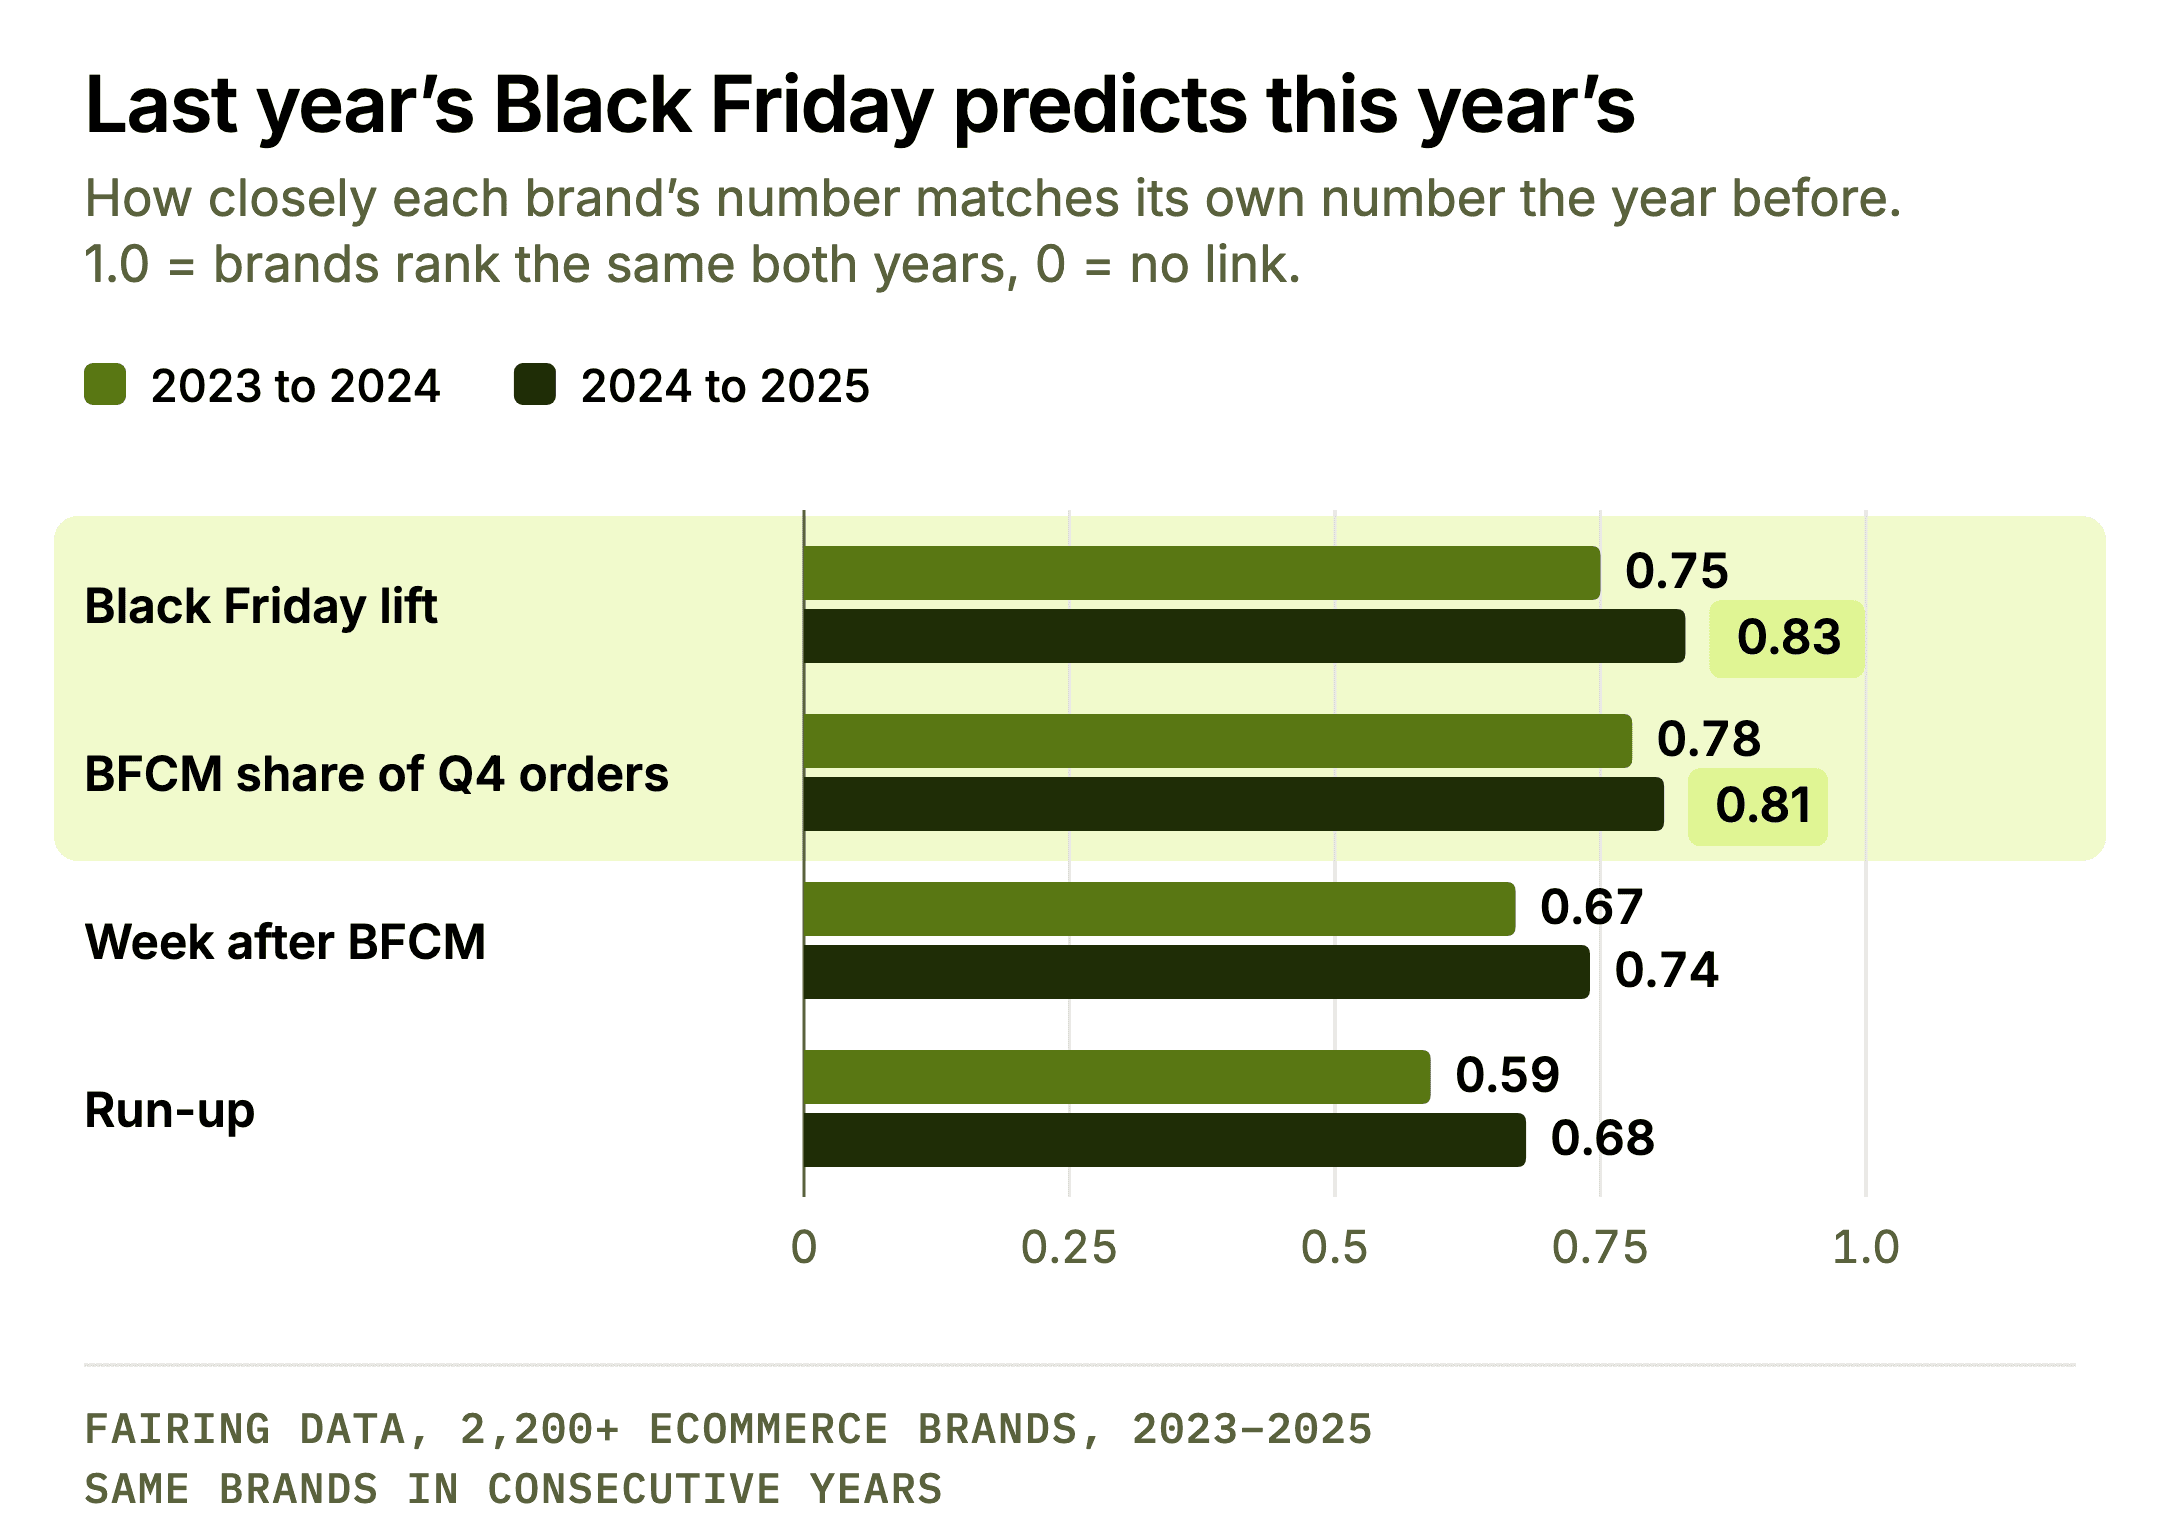
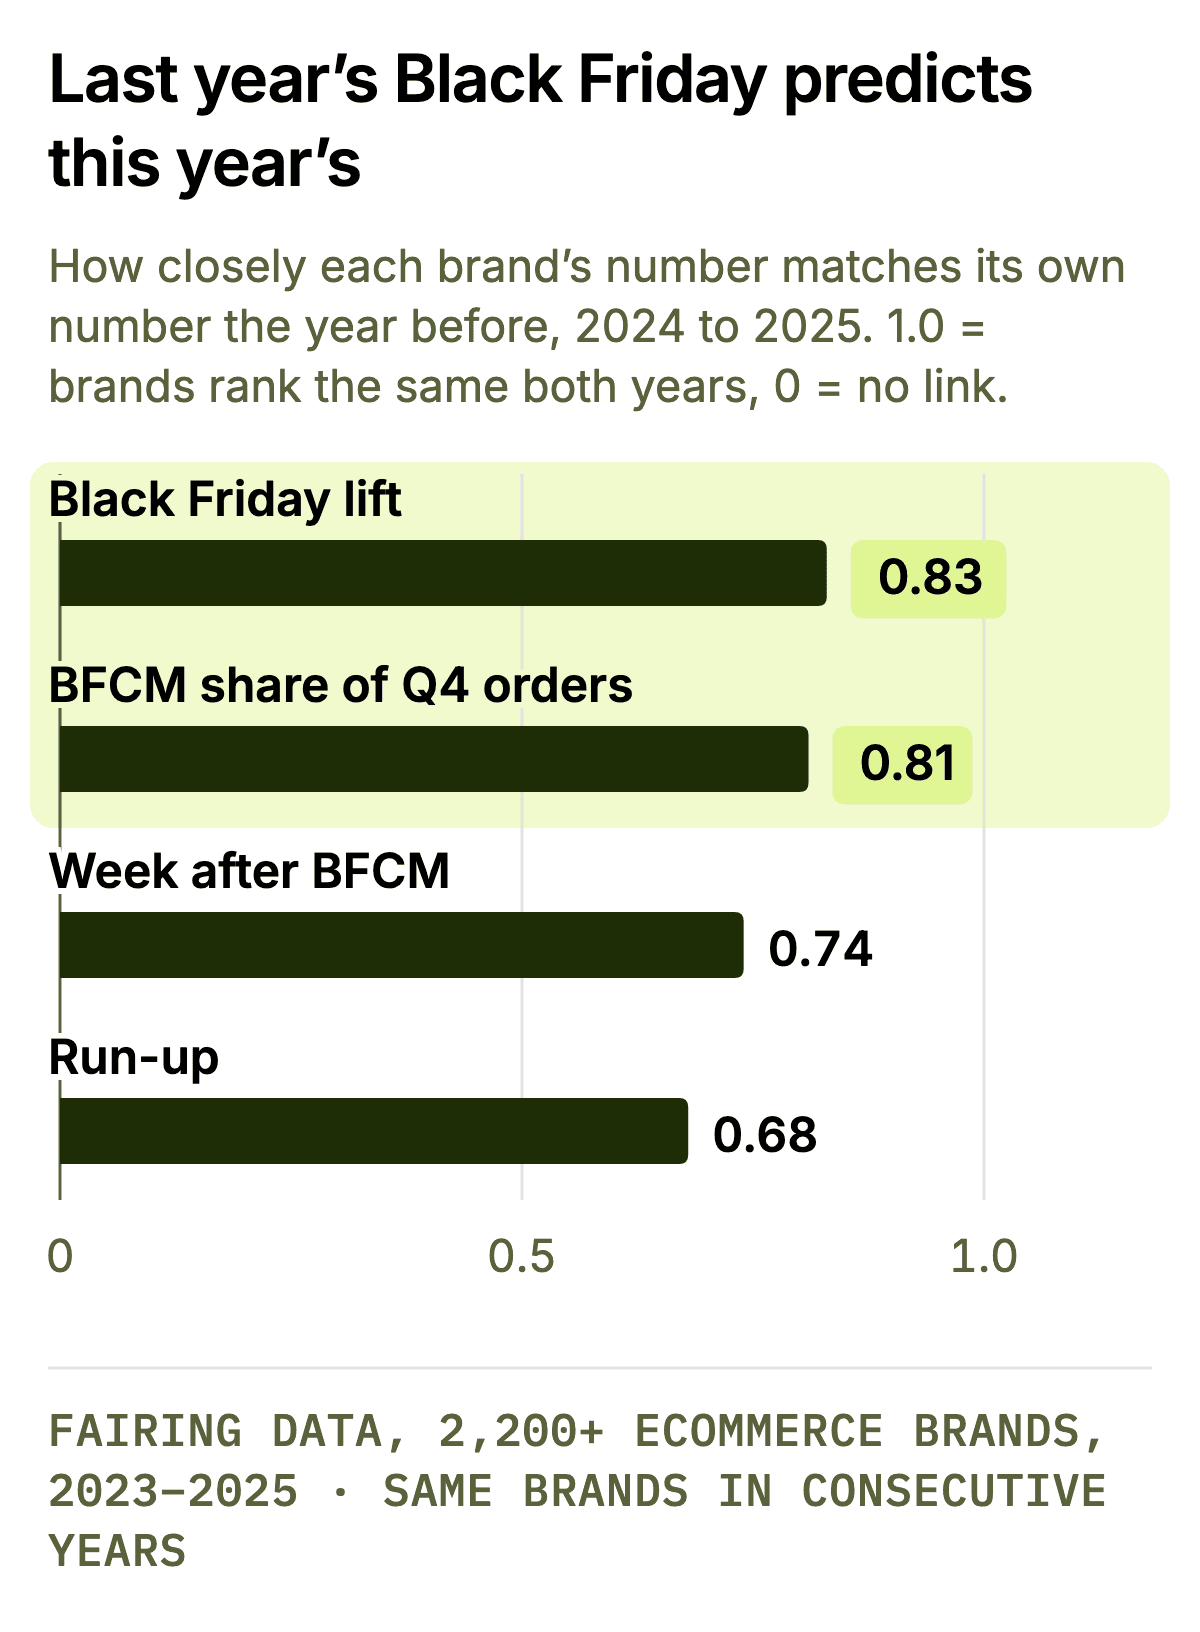
To forecast your Black Friday, start from your own last one. Brands that spiked hard one year spiked hard the next, and brands with a small Black Friday stayed small. Each brand’s Black Friday lift tracked its own the year before closely: a correlation of 0.75 (2023 to 2024) and 0.83 (2024 to 2025), where 1.0 would mean the same ranking every year. The share of Q4 that lands in BFCM repeats just as reliably (0.78 and 0.81), and so, a little less tightly, do the run-up and the week after. Your BFCM shape, how sharp the peak is and how early or late it lands, stays much the same from one year to the next.
Two cautions
Exceptional years drift back. The slope of this year’s lift on last year’s is 0.72 to 0.82, below 1, so a breakout Black Friday tends to land closer to normal the next year.
The typical brand’s lift still moves 25% to 27% from one year to the next, and only about half of brands land within 25% of their prior year.
Your offer repeats far less. Changes in code share and AOV at BFCM correlate only 0.34 to 0.59 with the year before, because they follow each year’s discount plan. Forecast order volume from last year, and plan the offer fresh.
How to plan for BFCM 2026
Why it matters: “Black Friday is 4.6x” is off by half for most brands, so stock and staff for your own multiple.
Pull your own Black Friday 2025 and Cyber 5 2025 multiples (orders divided by your October 2025 daily average). That’s your planning base, unless your business model has changed.
Plan a 25% band as your central case. Stress-test inventory and staffing at 50% either side.
If 2025 was a breakout year, plan the middle of the band below it.
Check it against your size band. A small brand planning for 6x, or a 1,000-orders-a-day brand planning for 4x, should know why.
Selling mainly in euros or pounds? Scale the all-brand numbers down by about a third.
Adjust up or down on Mon Nov 23 with the pre-Thanksgiving read from section 6.
2. BFCM grows baskets for consumables and brings new customers to apparel and home
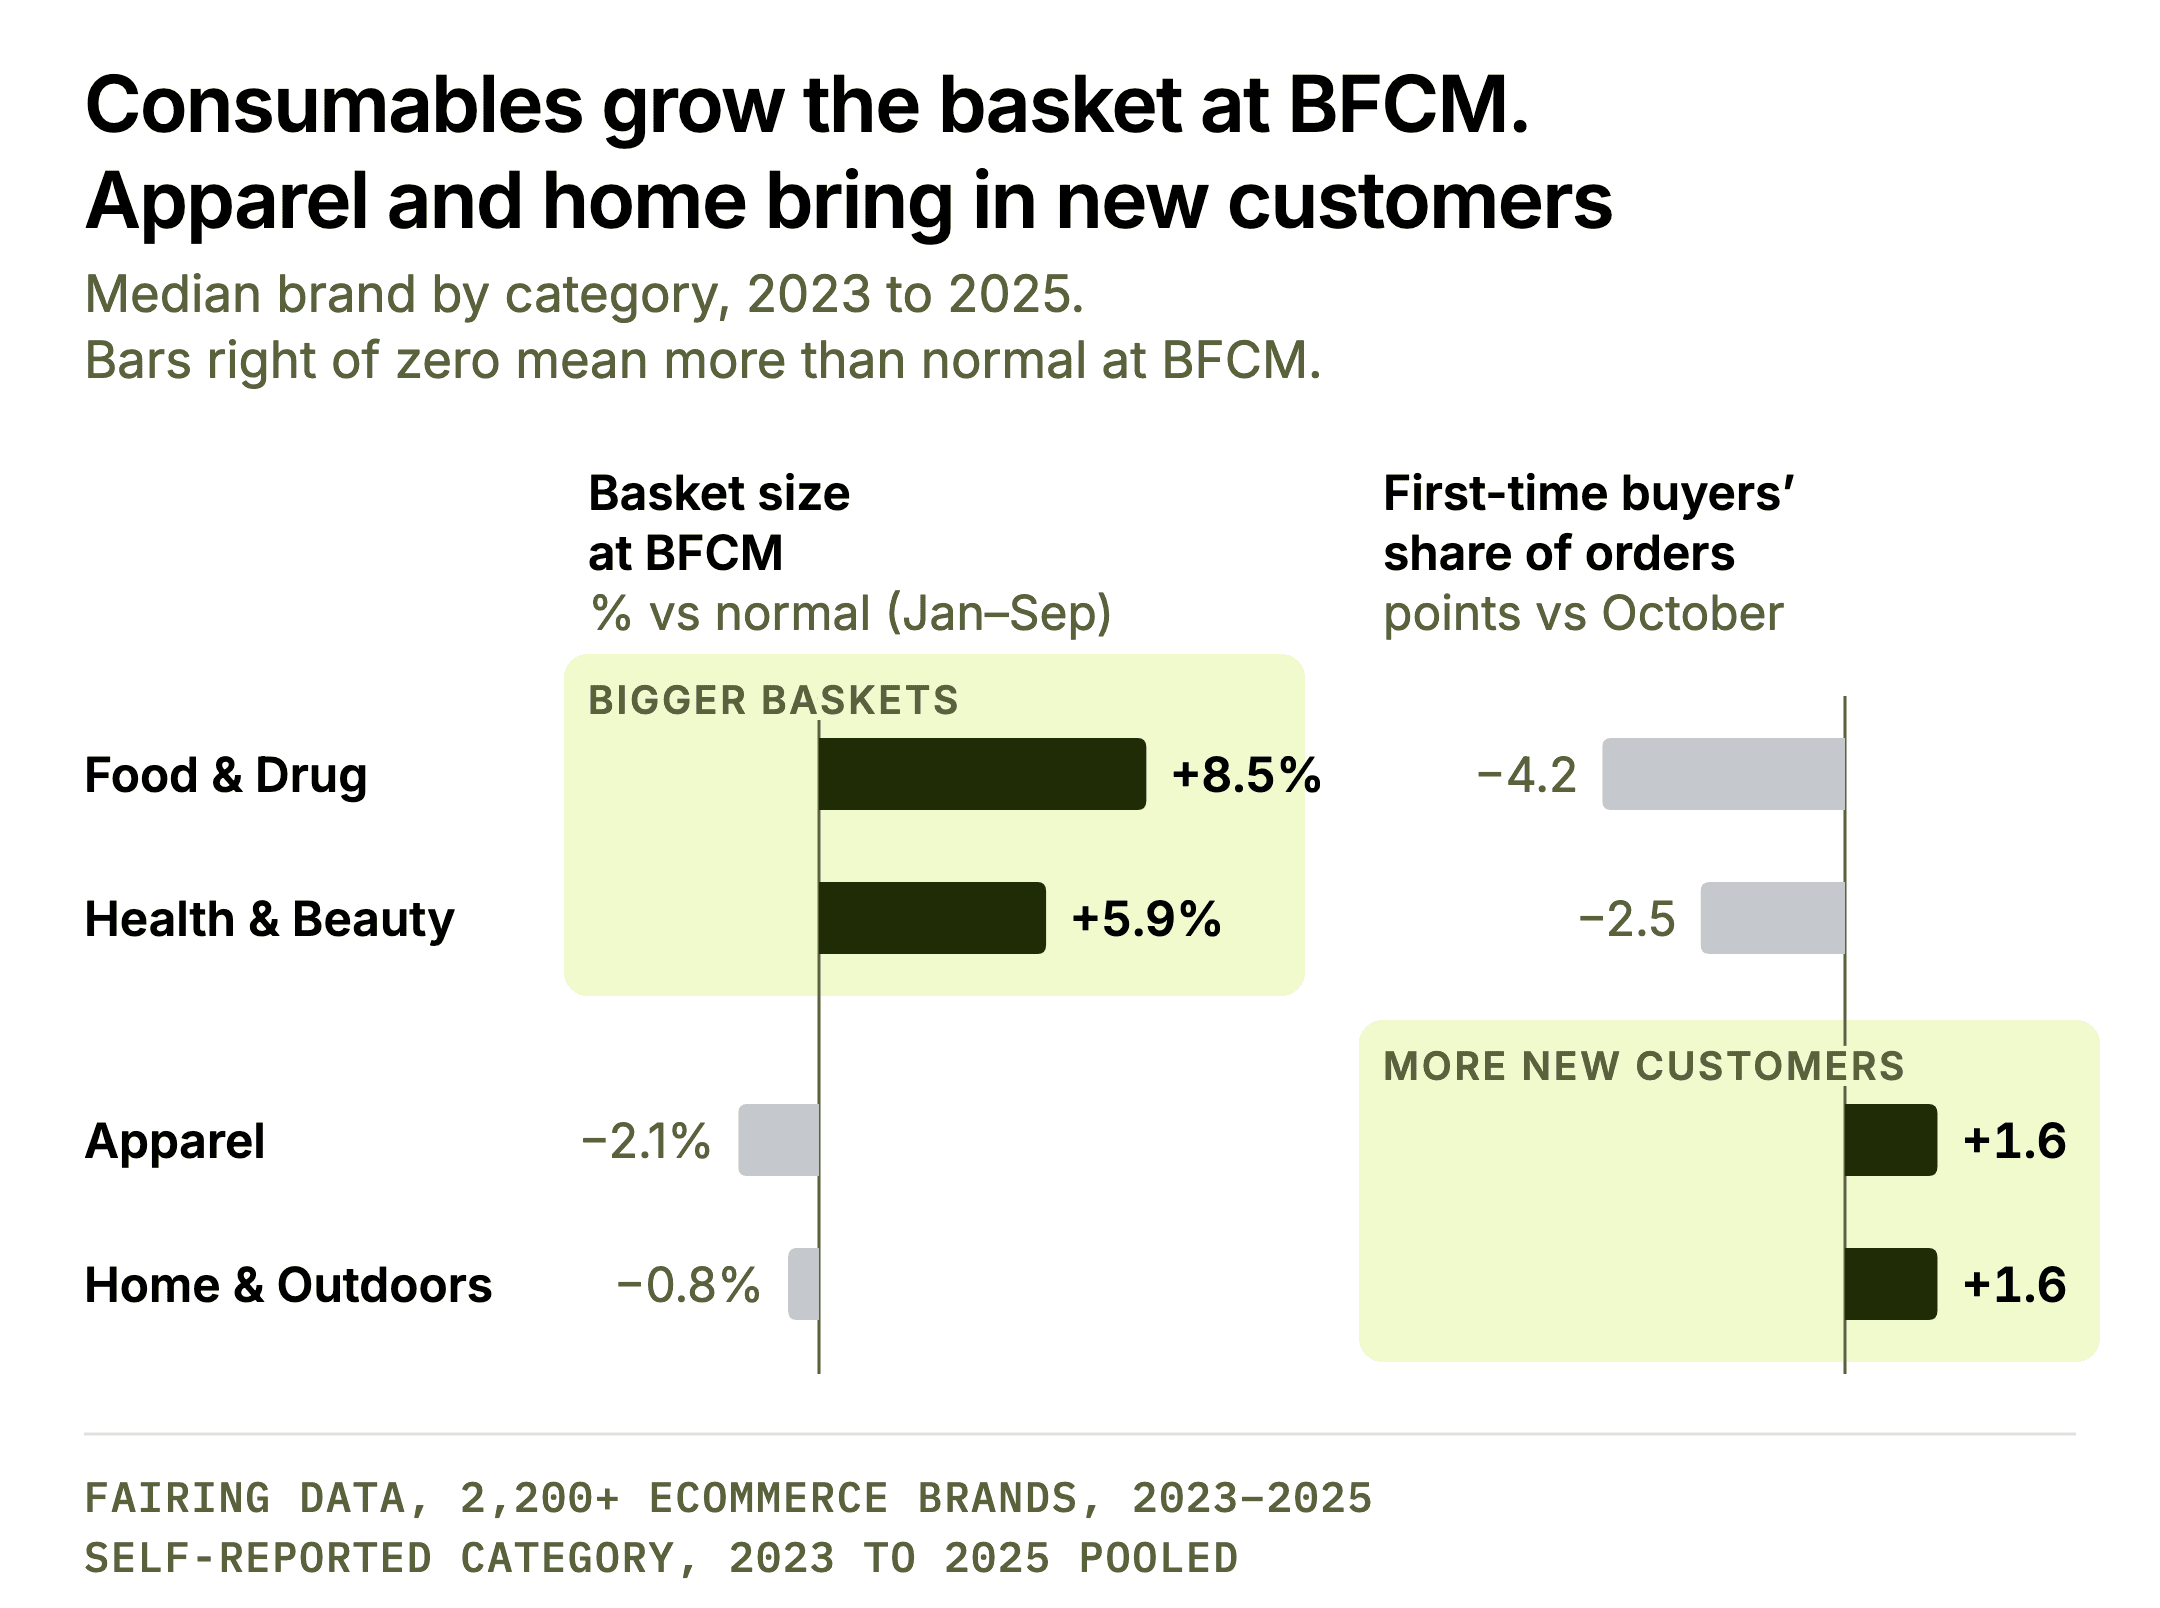
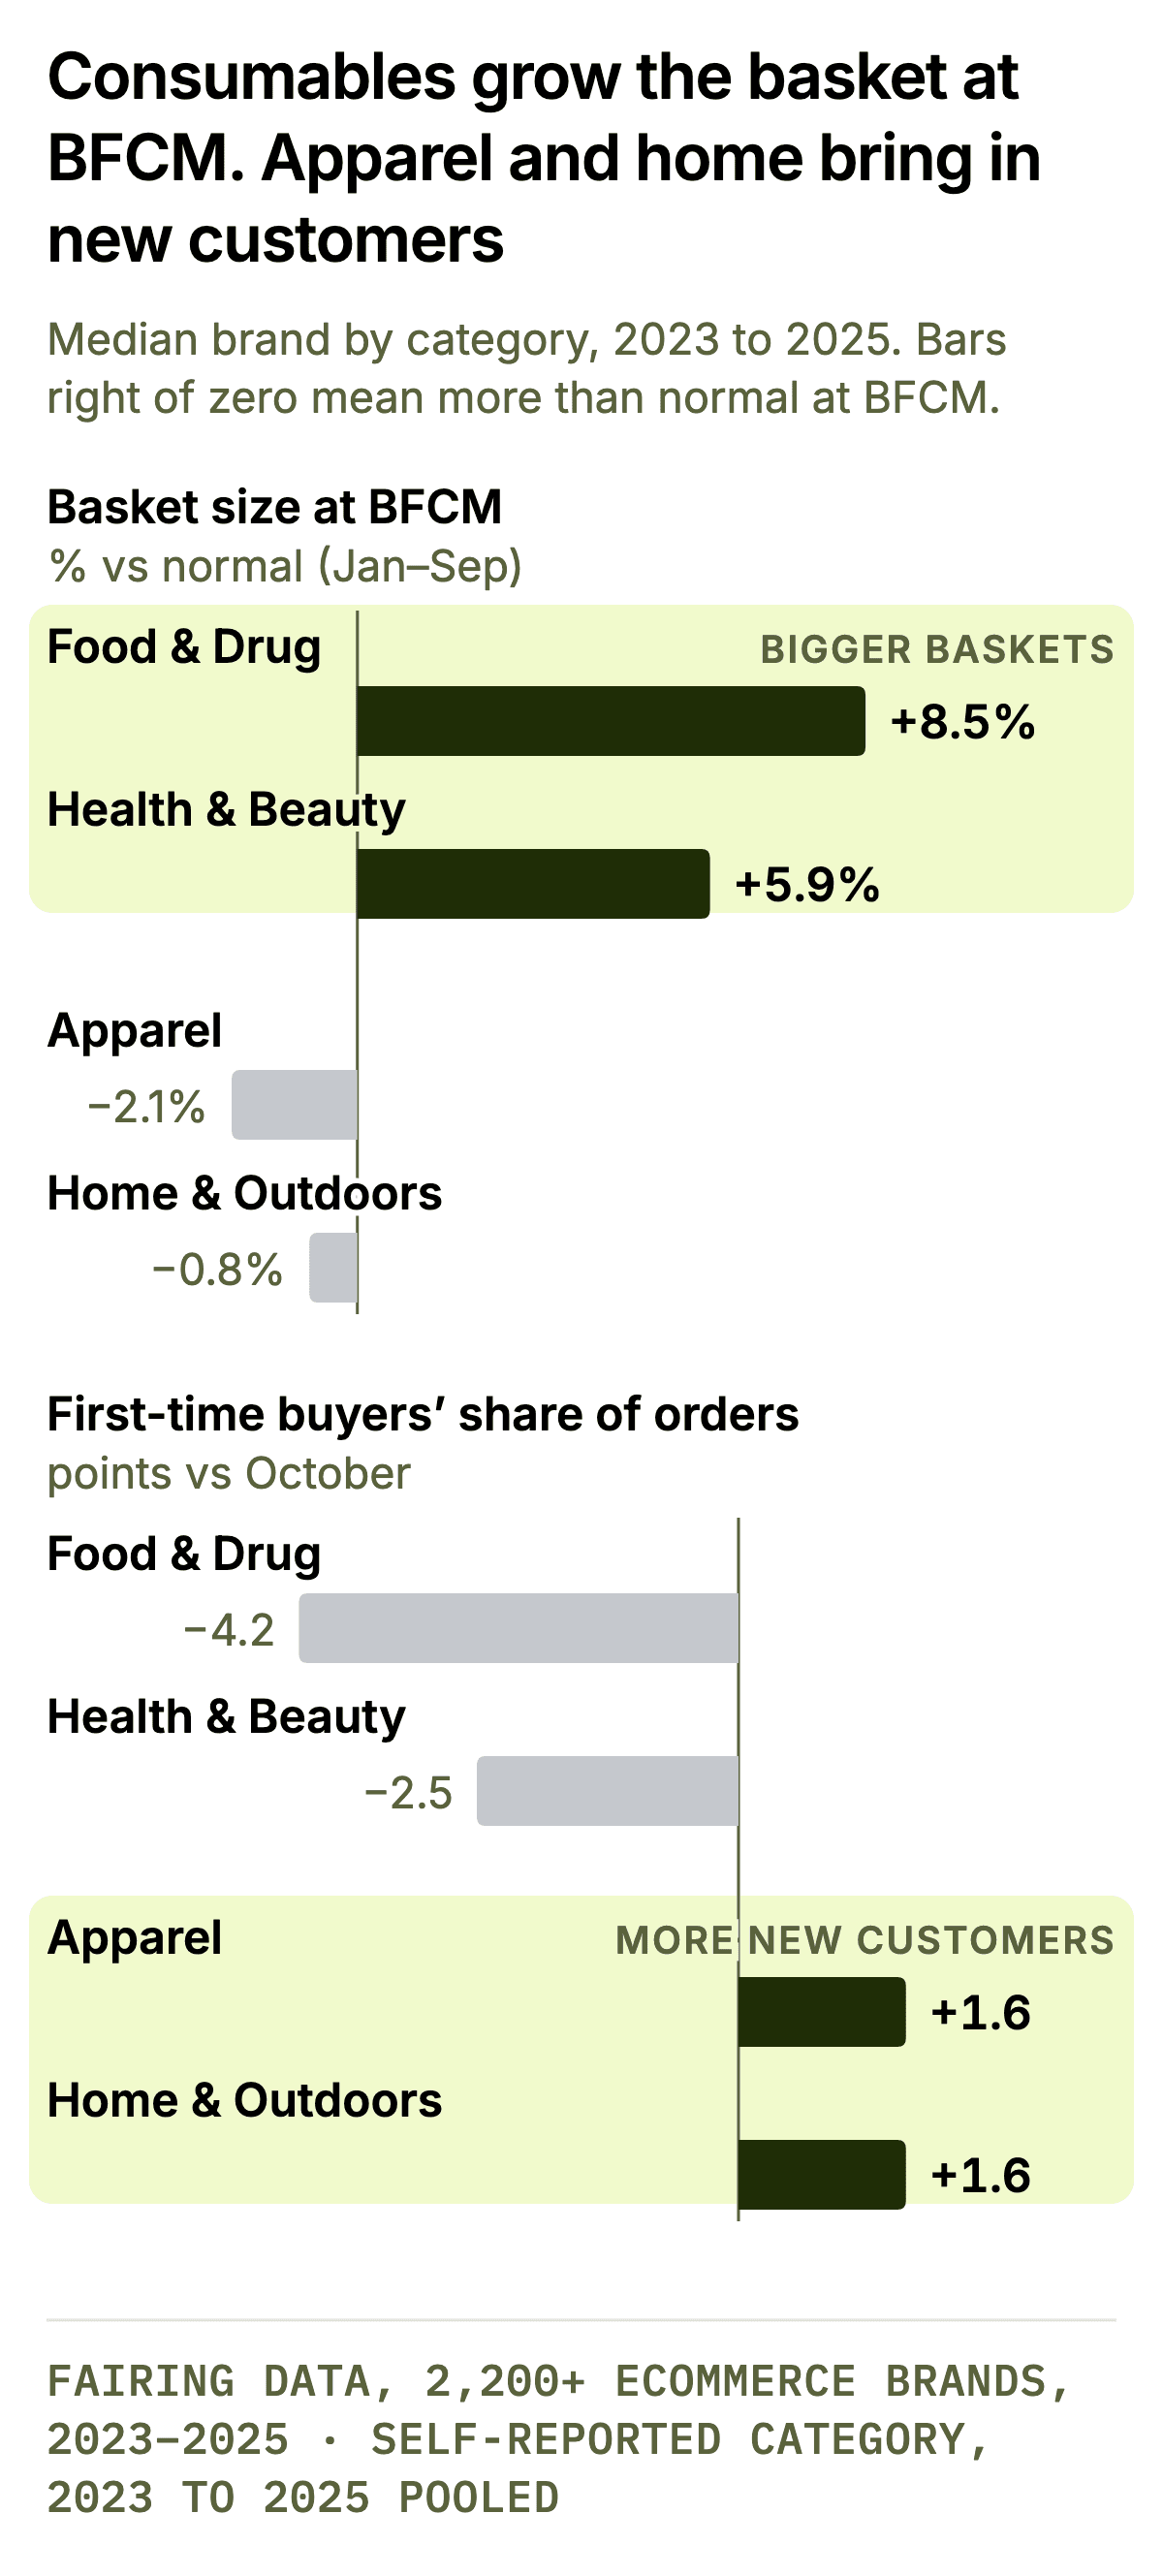
Across all brands, BFCM barely changes basket size or the share of first-time buyers. That flat average hides two groups pulling in opposite directions. Consumables (Food & Drug, Health & Beauty) sell bigger baskets, mostly to customers they already have. Apparel and home spike higher and bring in more first-time buyers. Which group you’re in decides whether to plan BFCM around basket size or around acquisition.
BFCM’s averages are flat. The shifts sit on either side.
Against each brand’s own January-to-September level, the biggest moves come before and after BFCM. The run-up has the biggest baskets and the fewest first-time buyers of the year, because existing customers buy early and buy more. December flips it, with the smallest baskets and the highest share of first-time buyers, and BFCM sits in between.
| Period | Basket size vs Jan to Sep | First-time buyers' share of orders |
|---|---|---|
| January to March | −1.4% | 67% |
| July to September | +0.5% | 65% |
| October | +2.7% | 64% |
| Run-up (16 to 2 days before Black Friday) | +3.1% | 63% |
| Thanksgiving to Cyber Monday | +1.4% | 64% |
| Week after Cyber Monday | −1.5% | 68% |
| December 11 to 20 | −1.0% | 69% |
Two groups of categories behave in opposite ways
Category is the merchant’s self-reported product category. Each of the four groups has hundreds of brands.
Find your category’s row. These are the numbers to plan against, in place of the all-brand median.
| Category | Run-up | Black Friday | Cyber Monday | Week after | Dec 11 to 20 |
|---|---|---|---|---|---|
| Apparel | 1.61x | 6.03x | 4.58x | 1.62x | 1.59x |
| Home & Outdoors | 1.71x | 5.88x | 4.79x | 1.62x | 1.33x |
| Health & Beauty | 1.42x | 4.14x | 3.30x | 1.14x | 1.03x |
| Food & Drug | 1.23x | 2.75x | 2.48x | 1.05x | 0.97x |
Consumables use BFCM as a stock-up for existing customers
Food & Drug lifts 2.75x on Black Friday and Health & Beauty lifts 4.1x. Their baskets grow (+8.5% and +5.9%) while the share of first-time buyers falls (−4.2 points and −2.5 points). That’s the pattern you’d expect from bundles and multi-packs bought by people who already know the product.
Apparel and home use BFCM to acquire
Both lift about 6x. Apparel baskets shrink 2% and home’s basket is flat, while the share of first-time buyers rises about 1.5 points. On every one of these metrics, the 95% confidence intervals for apparel and the consumables categories don’t overlap.
The split carries into December
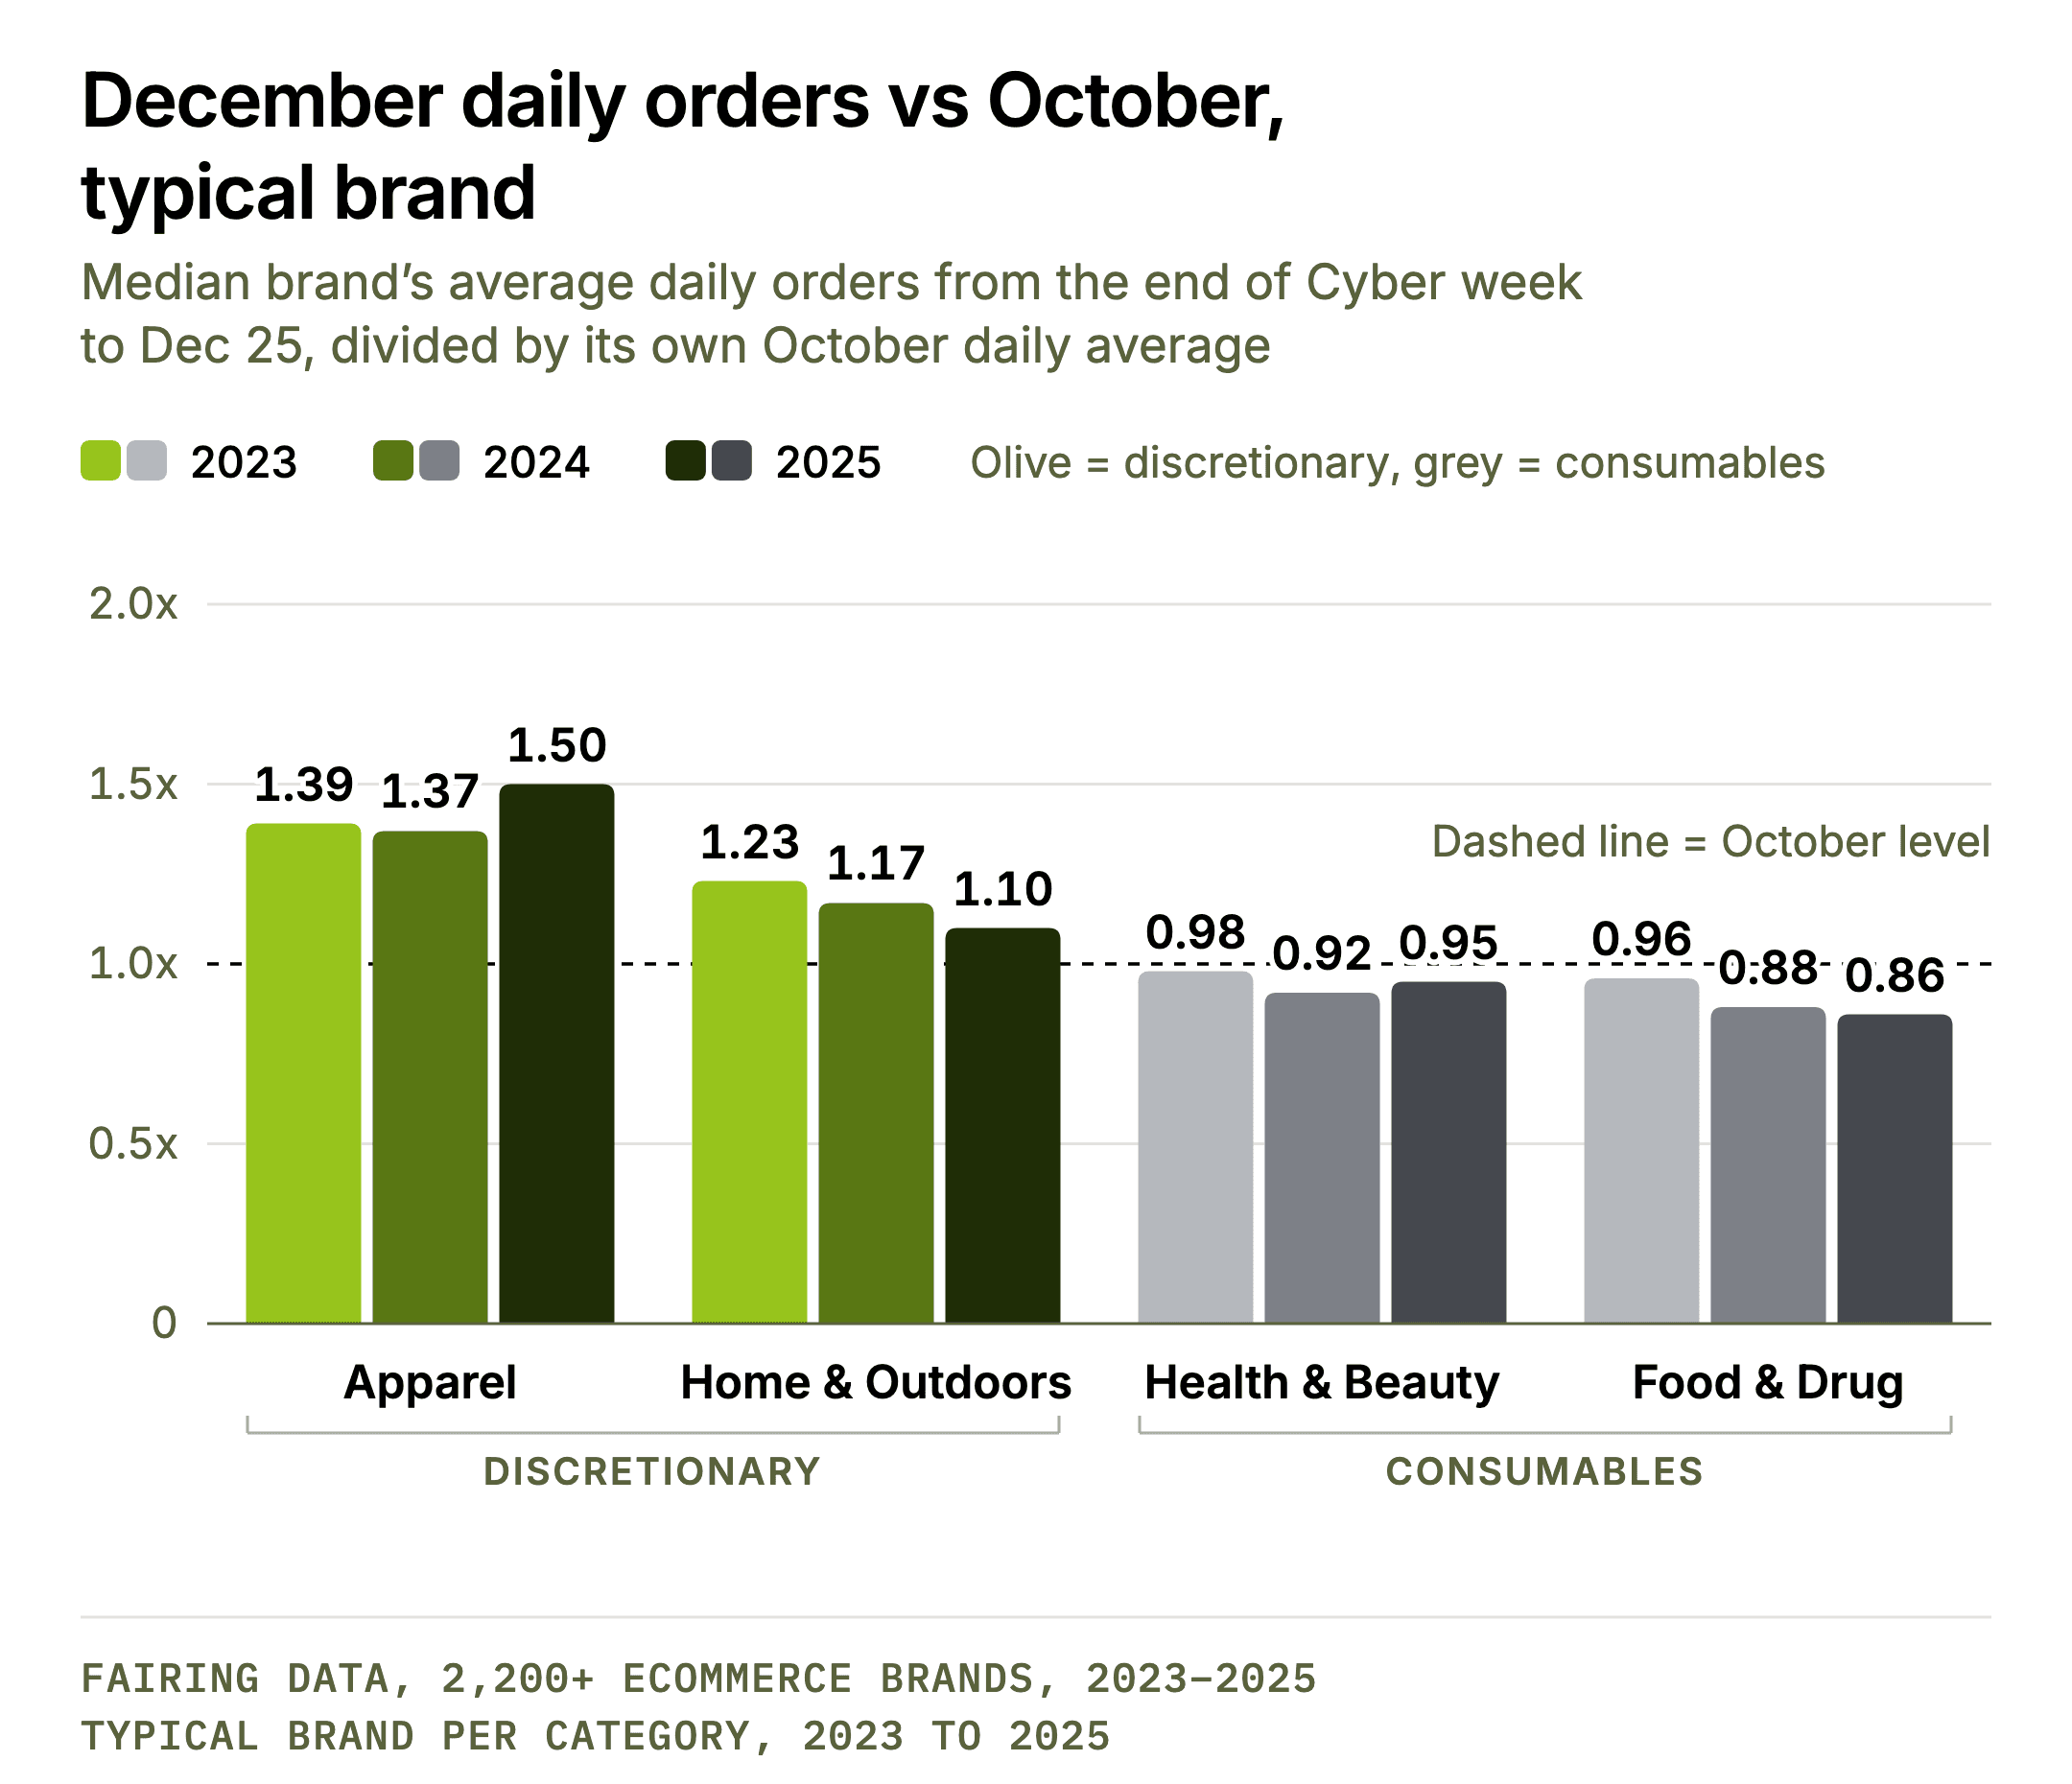
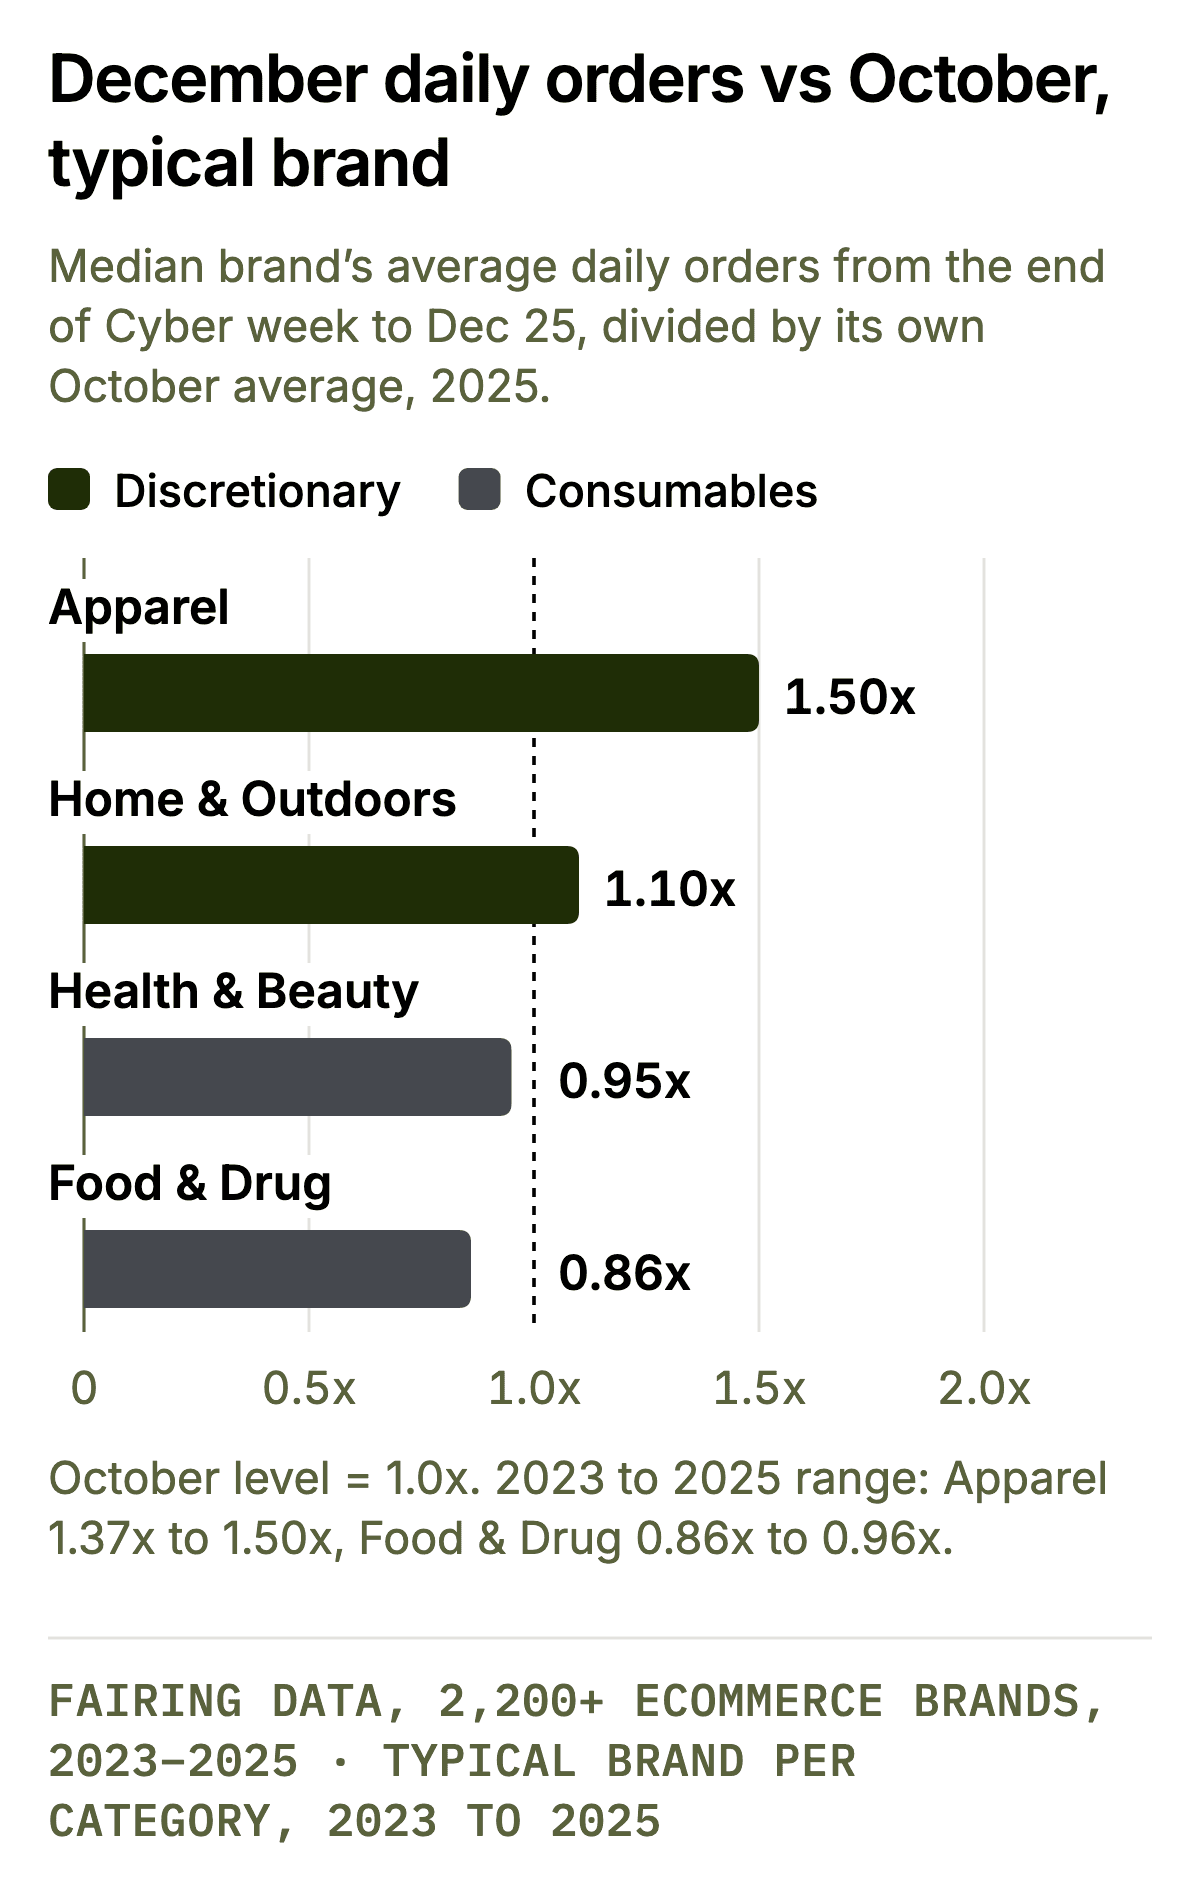
Compare each brand’s December with its own October. From the end of Cyber week (the week after Cyber Monday) to Dec 25, the typical apparel brand ran at 1.4x to 1.5x its October daily orders and the typical home brand at 1.1x to 1.2x. Consumables ran below October. The typical Health & Beauty brand was at 0.92x to 0.98x, and the typical Food & Drug brand fell from 0.96x in 2023 to 0.88x in 2024 and 0.86x in 2025.
Two cautions on December
The window was five days shorter in 2024 (see section 4), but each figure is a daily average, so window length does not drive it.
It fits customers who stocked up at BFCM and didn’t need to reorder yet. We haven’t split reorder timing by category (section 10 has it for all brands).
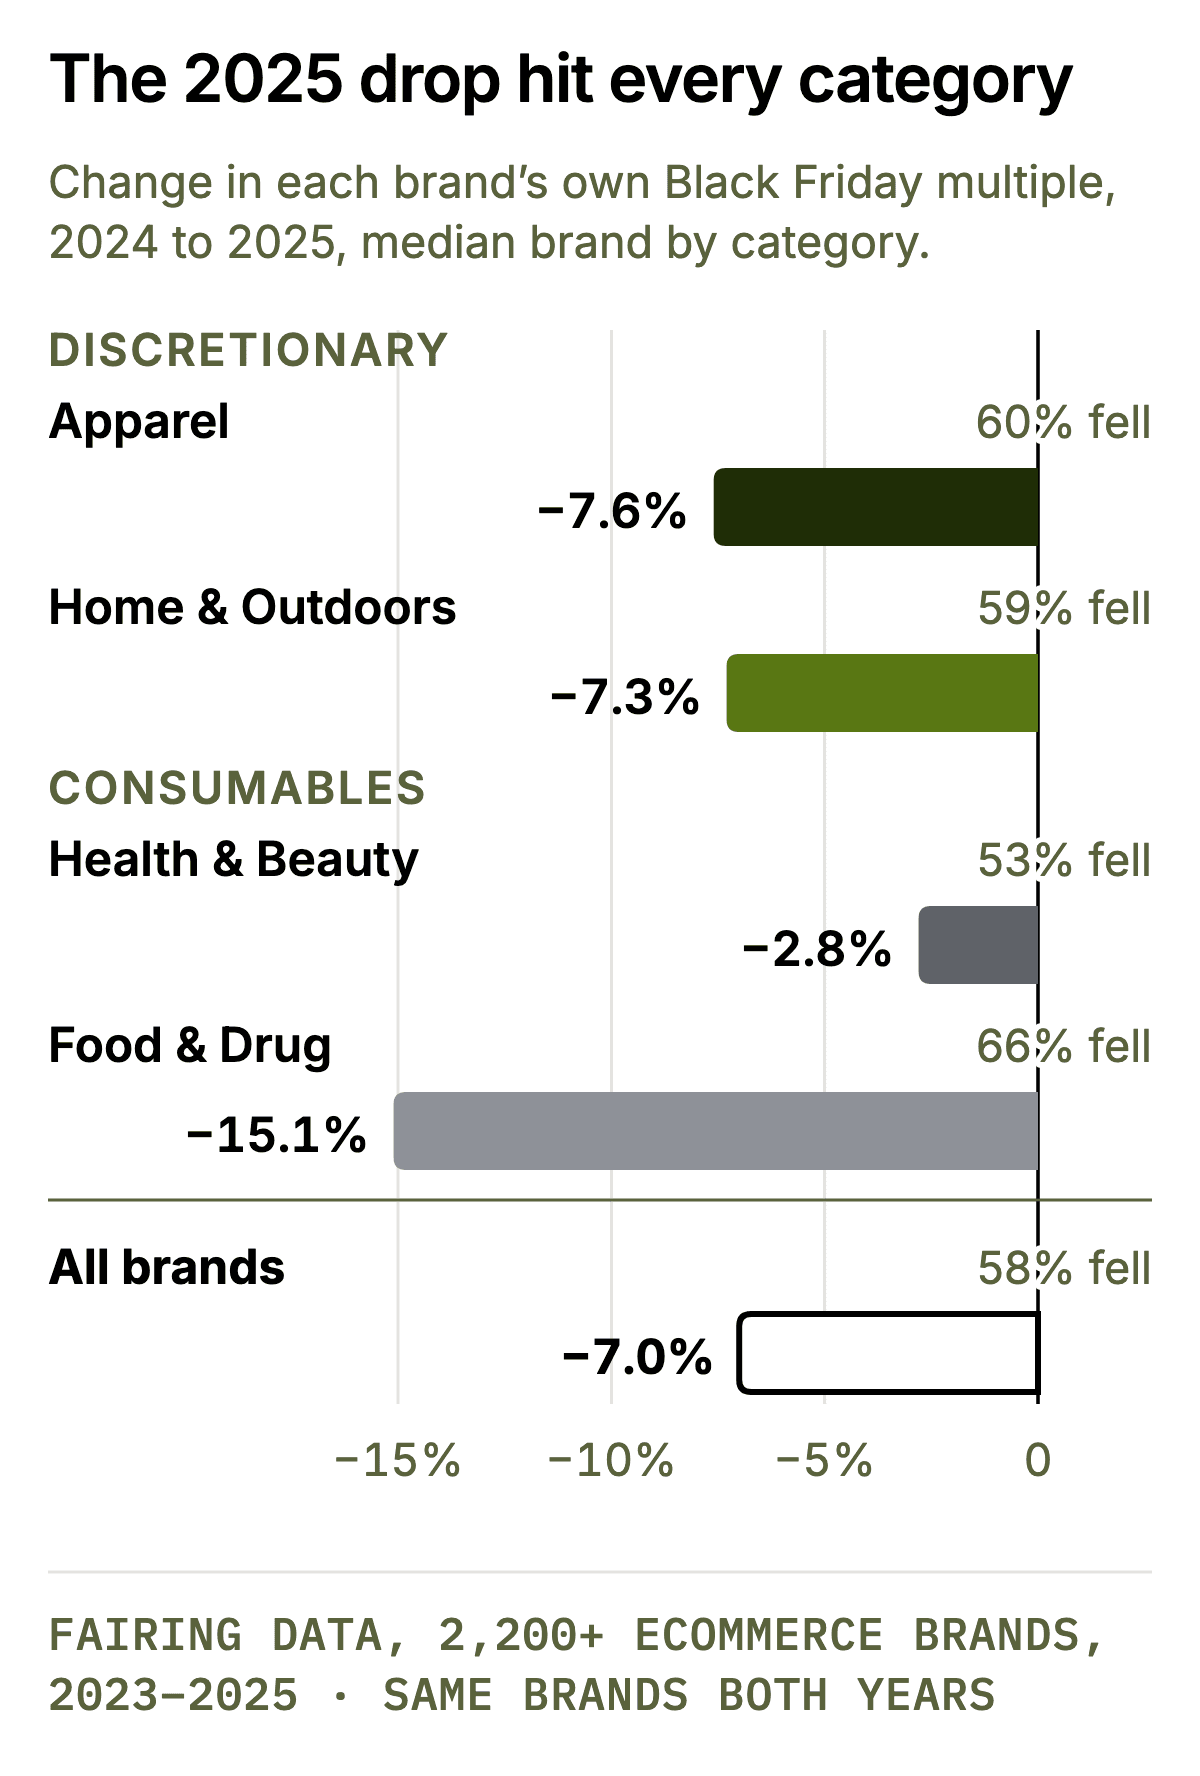
The 2025 drop hit every category
Comparing each brand with its own 2024, apparel and home were both about 7% lower, Food & Drug was 15% lower and Health & Beauty was 3% lower. Year-by-year category medians can look like one category shrinking and another holding, but much of that is which brands were active each year.
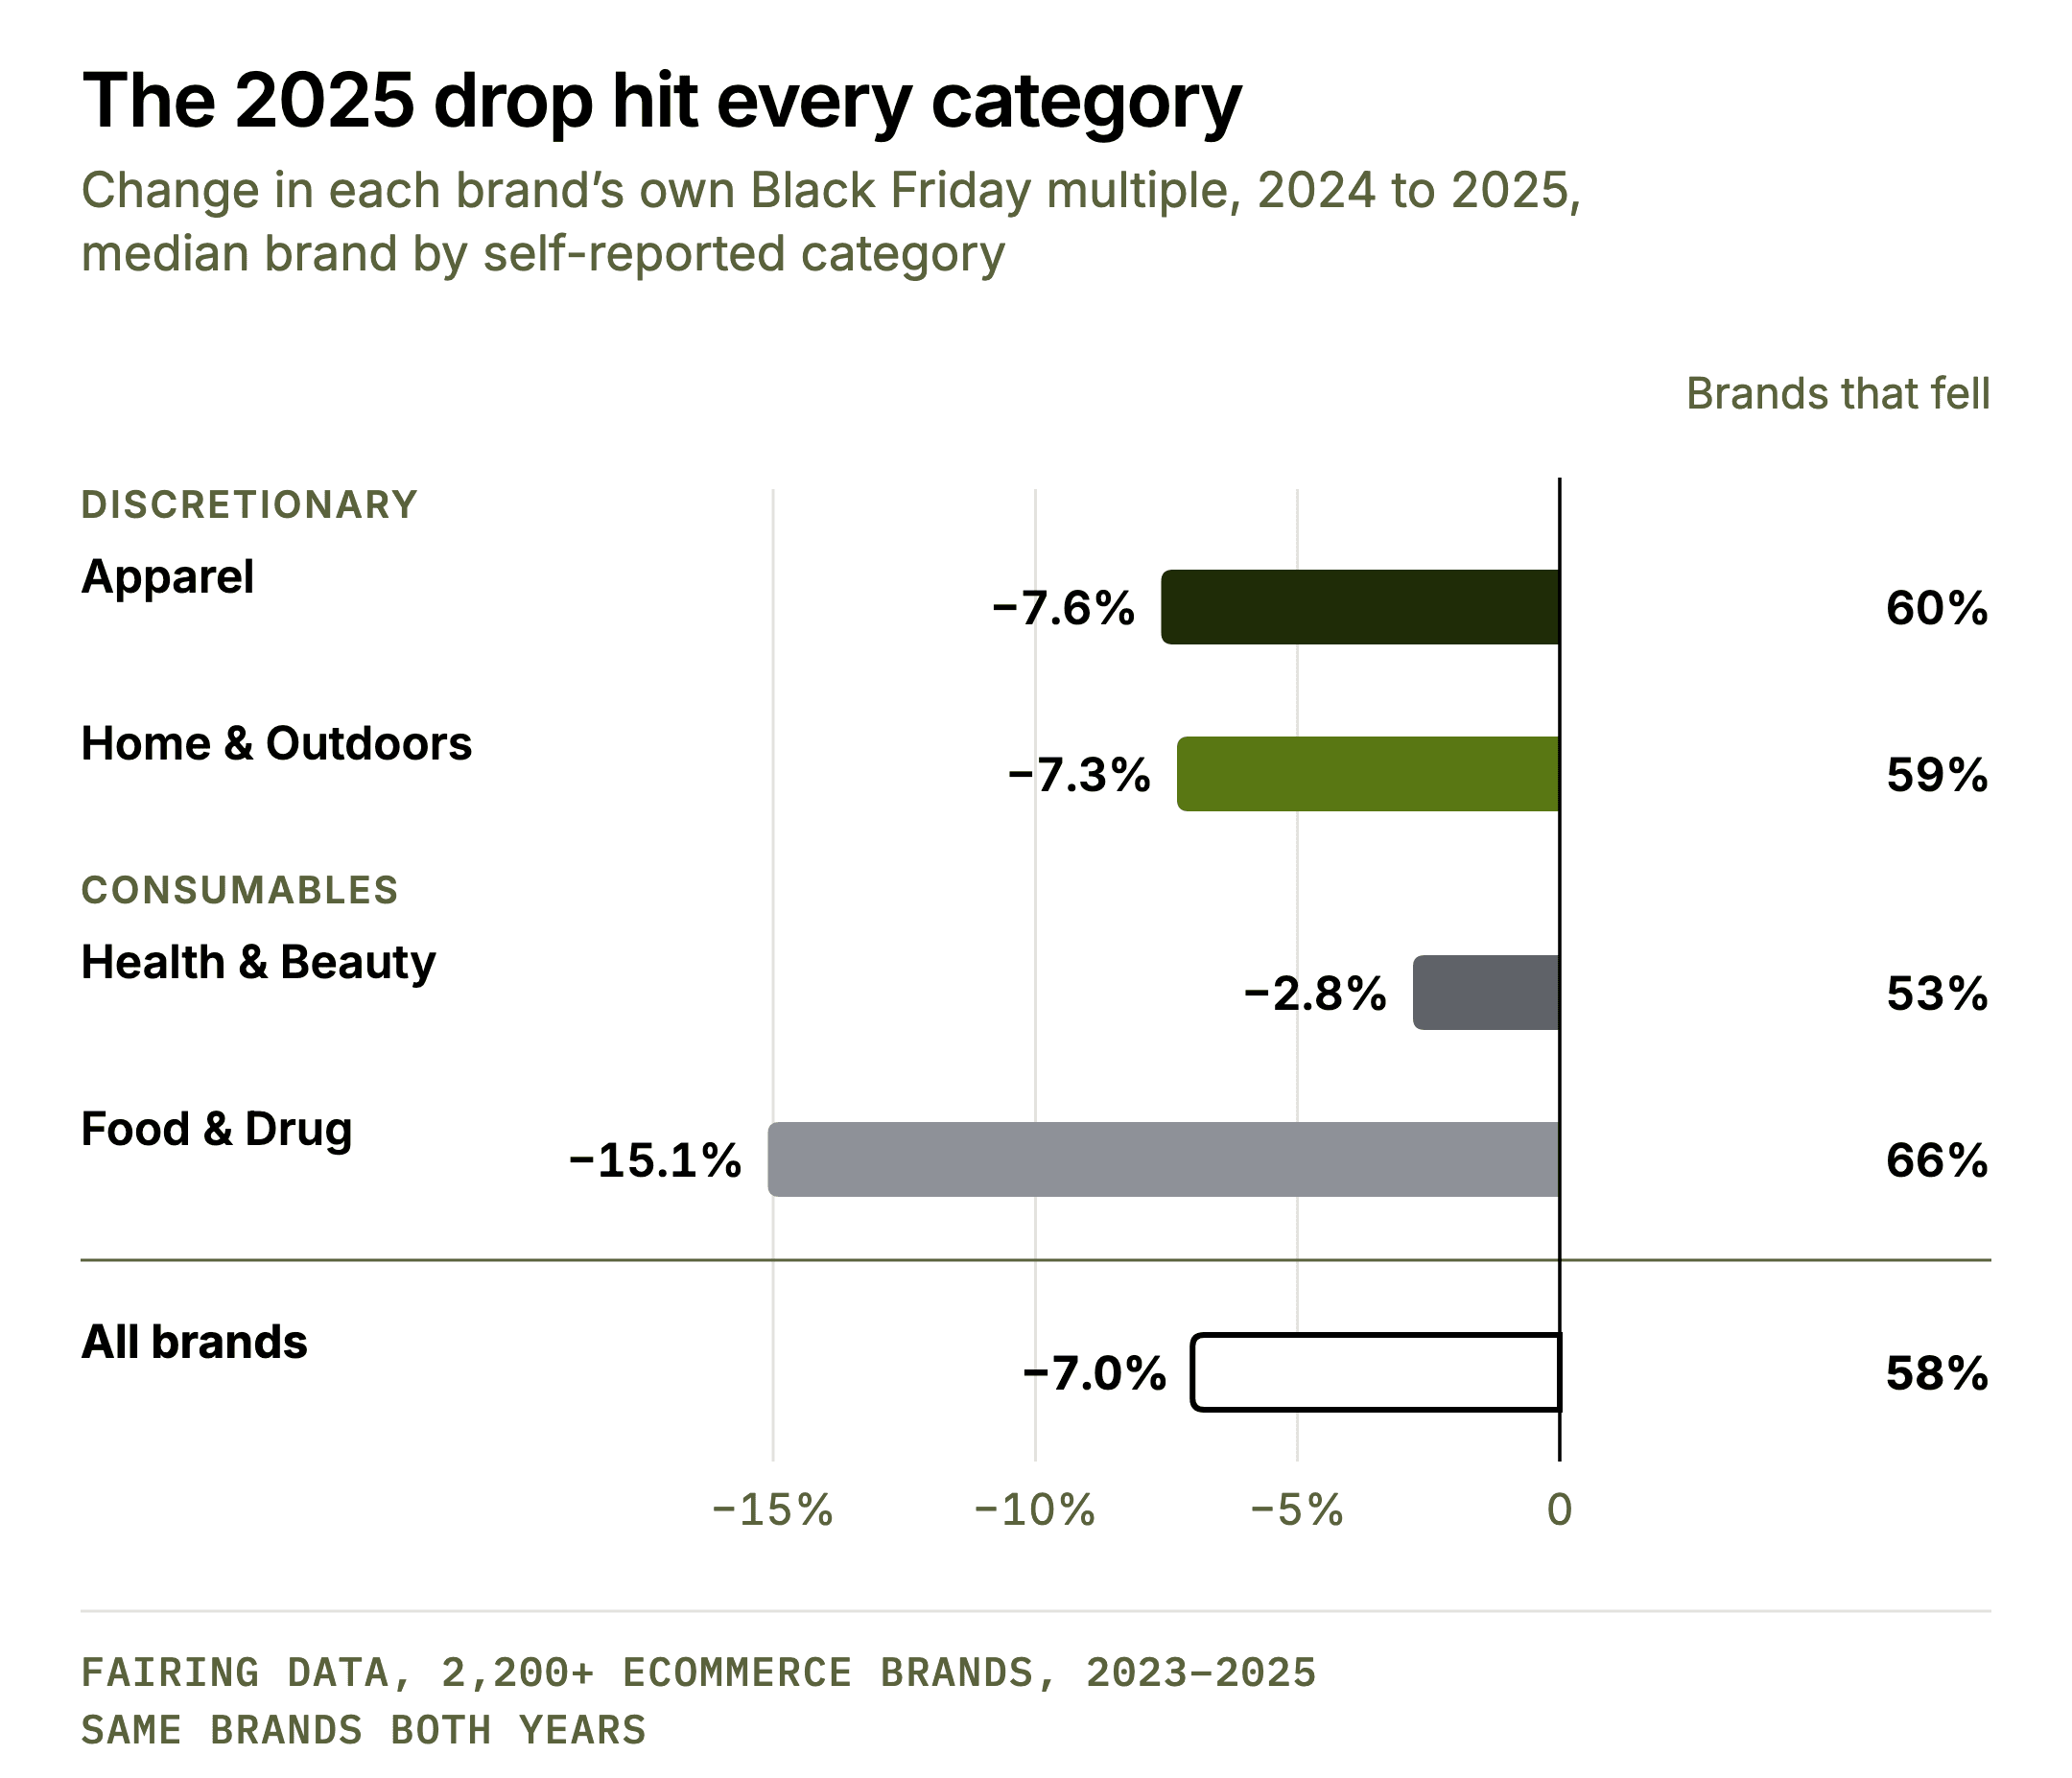
How to plan for BFCM 2026
Why it matters: Industry benchmarks blend these groups, so a Food & Drug brand at 2.8x is on its category’s median and judging it against an apparel brand’s 6x leads to the wrong call on spend.
Consumables: build the basket with bundles, multi-packs and spend thresholds, and give existing customers the early offer.
Expect December to run a little below October level.
Use it for subscription conversion and replenishment reminders, not another round of discounts.
Apparel and home: treat BFCM as your biggest prospecting window. Keep acquisition spend on through the December peak, and build creative for first-time buyers.
Everyone: benchmark against your category’s numbers, not the all-brand median.
Plan the two groups differently: consumables win on basket size and loyal customers, apparel and home on acquisition.
3. Price point sets how you win
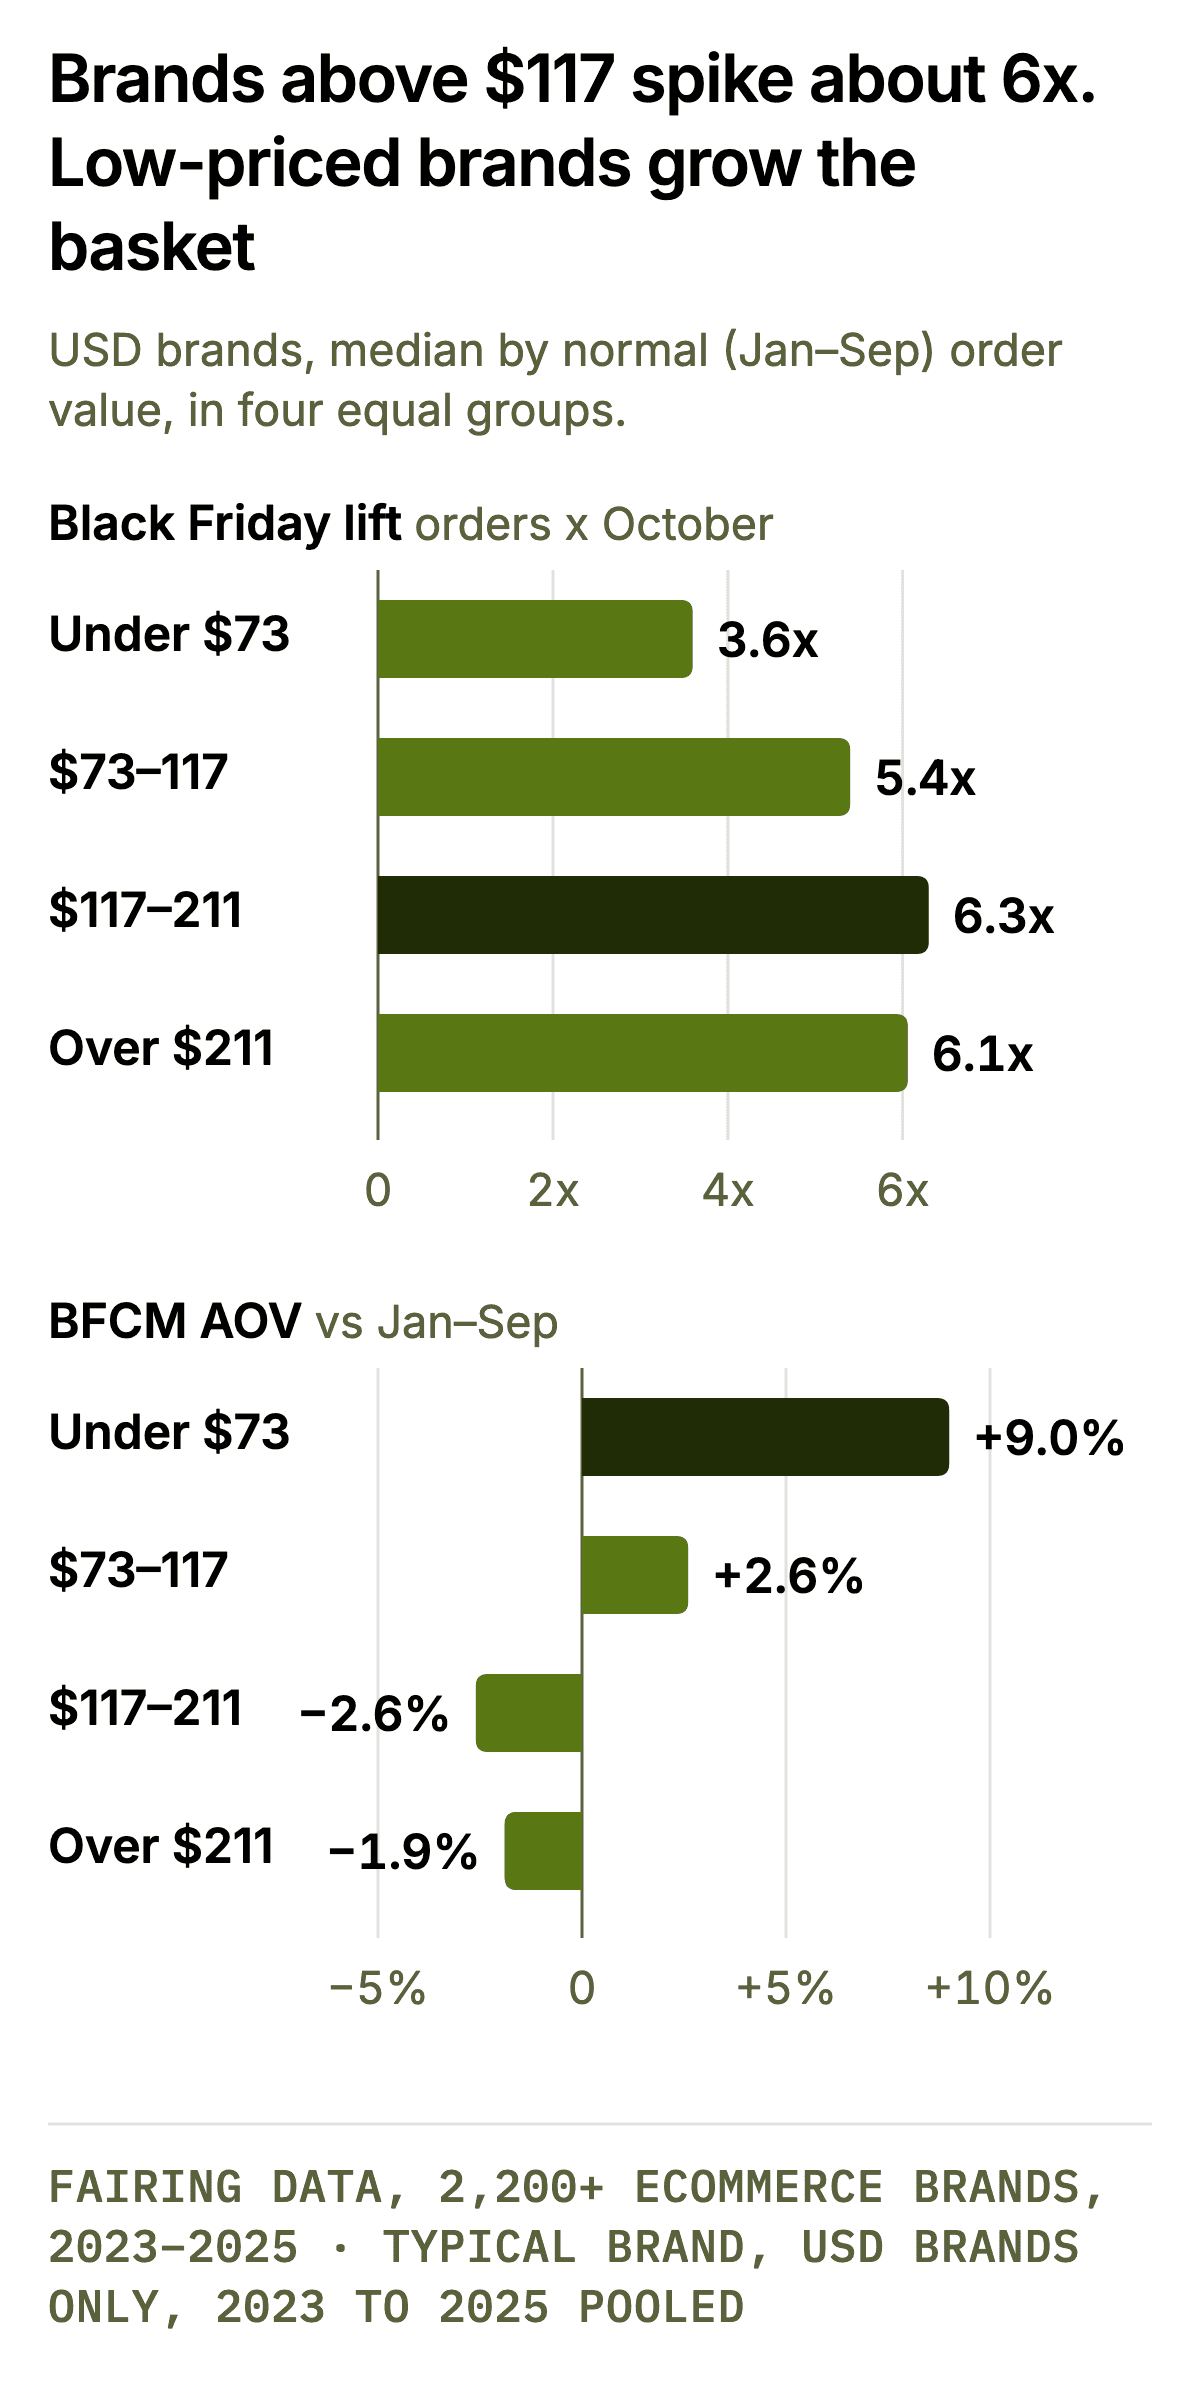
Brands whose normal order is above $117 spike about 6x October on Black Friday. Brands under $73 spike less, but grow the basket.
Higher-priced brands spike about 6x
A brand with a normal order above $117 lifts about 6x October on Black Friday. Its baskets shrink slightly, by 2% to 3%.
Under $73, the lift is smaller but the basket grows
These brands lift 3.6x on Black Friday, and their BFCM basket is 9% bigger. The revenue lift comes to about 3.9x, against about 6x for the $117-plus groups. Price overlaps with category, and Food & Drug and Health & Beauty brands sit mostly in the lower groups.
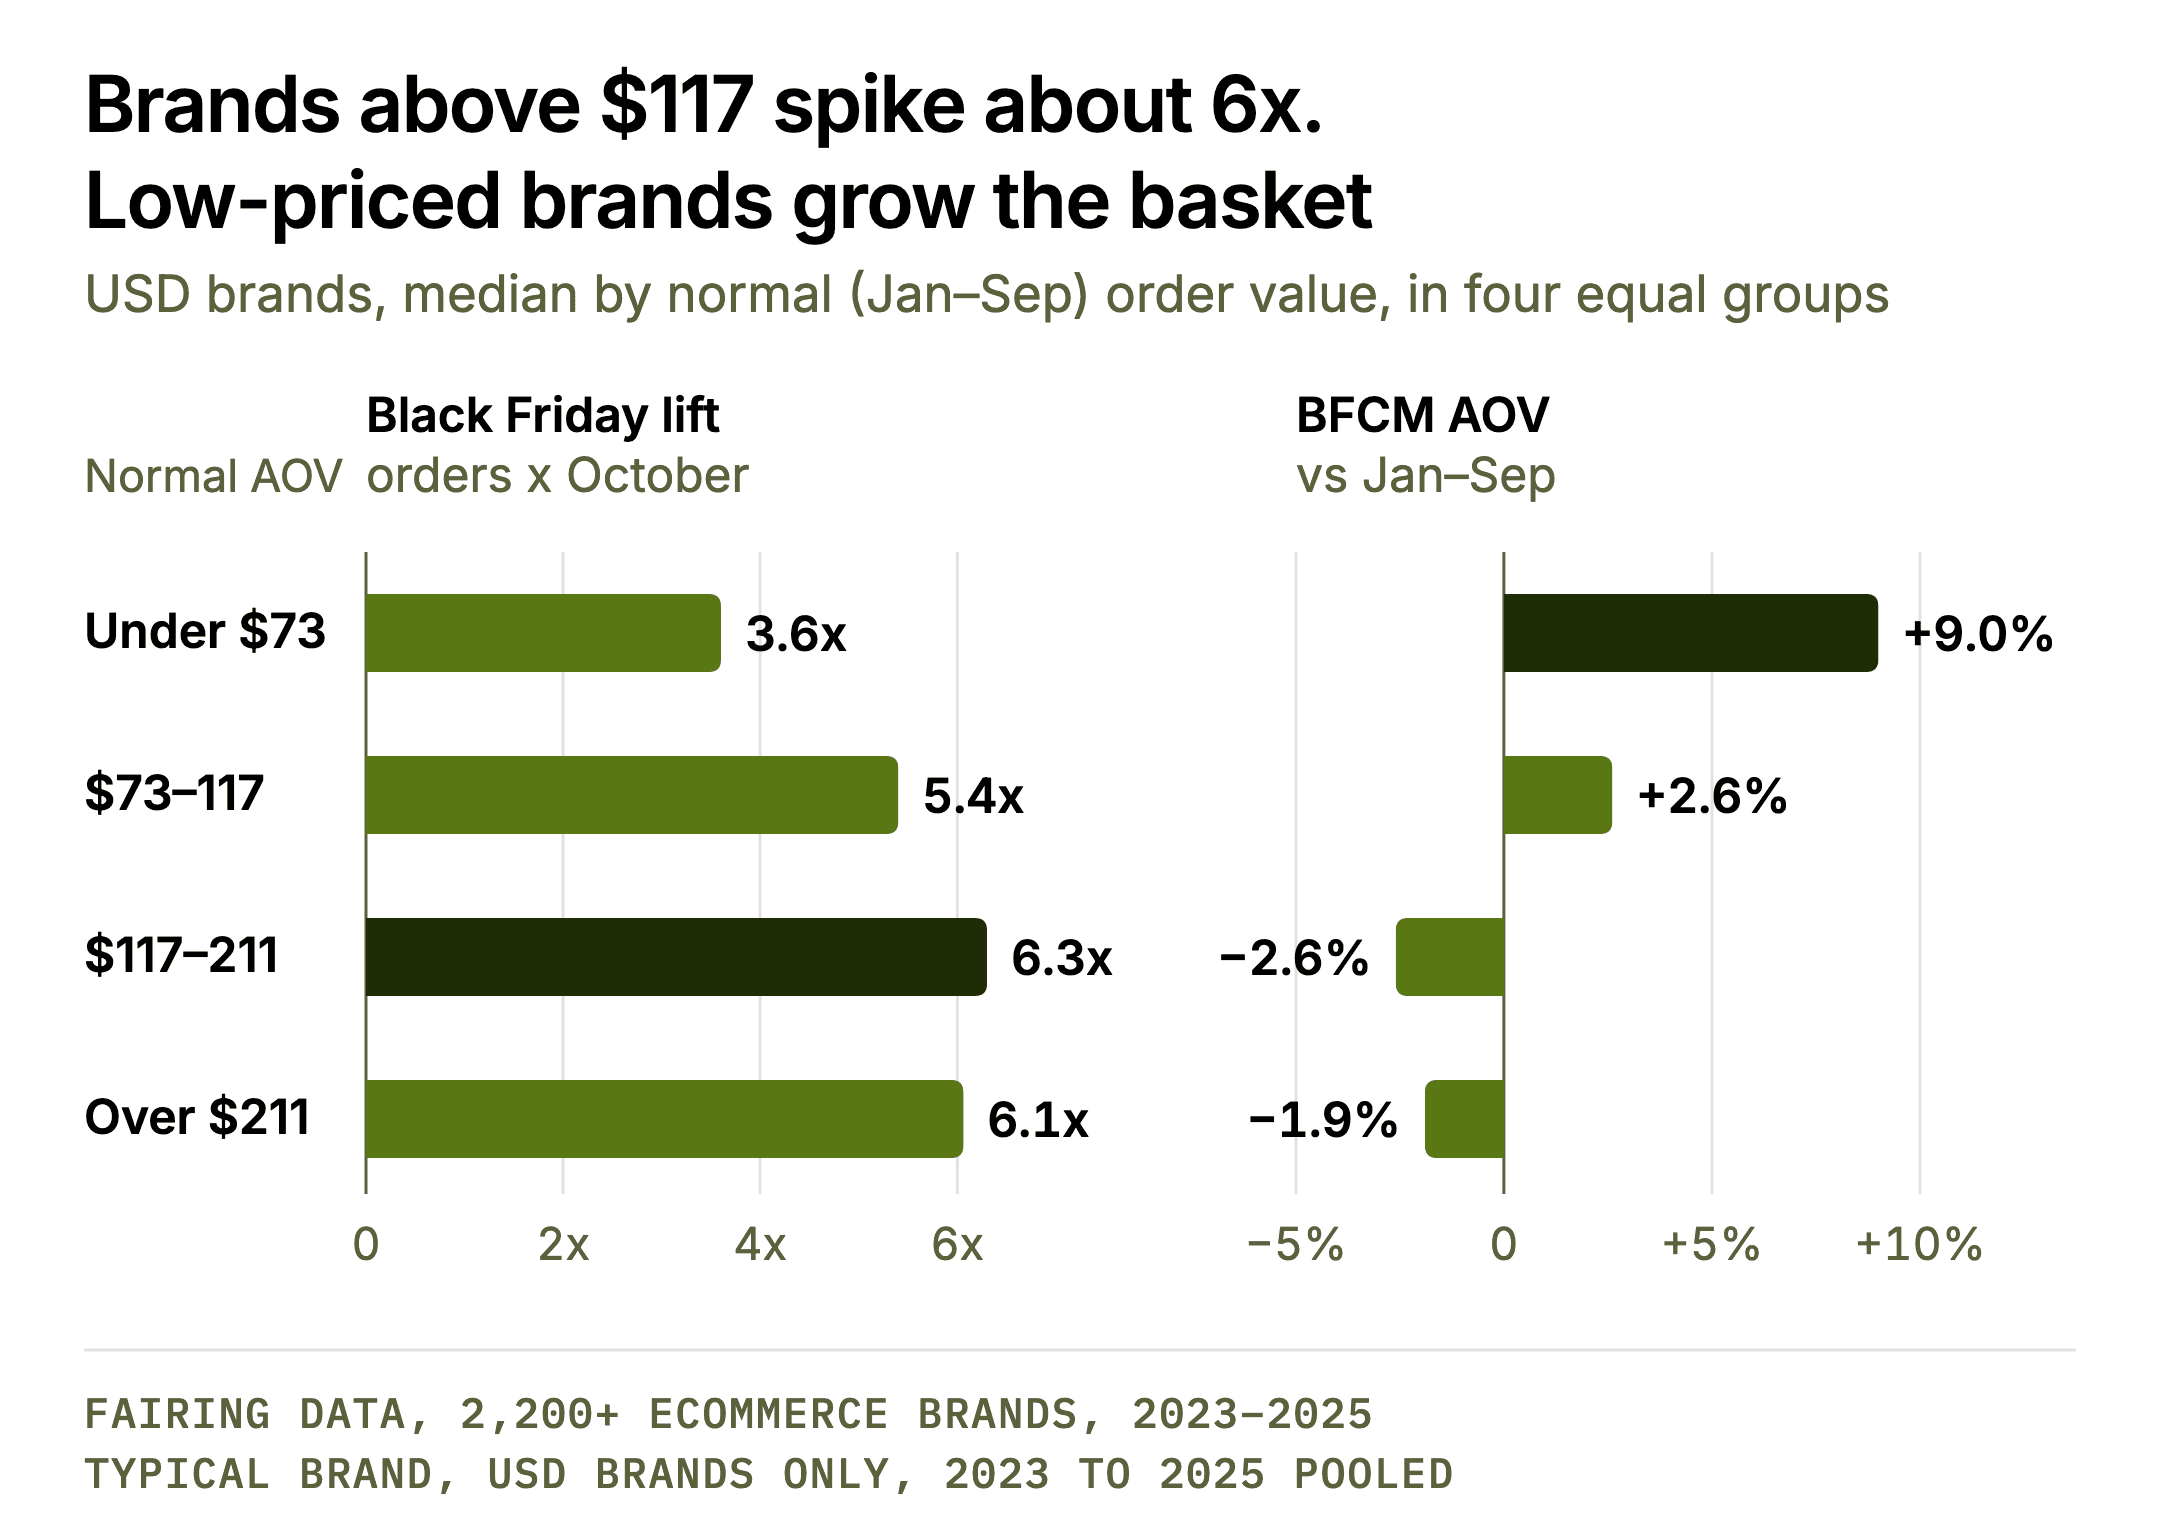
| Normal order value (Jan to Sep) | Typical | Black Friday | BFCM basket change |
|---|---|---|---|
| Under $73 | $56 | 3.60x | +9.0% |
| $73 to $117 | $92 | 5.40x | +2.6% |
| $117 to $211 | $153 | 6.30x | −2.6% |
| Over $211 | $362 | 6.06x | −1.9% |
A bigger lift usually comes with a smaller basket
Inside each brand, order count trades off against order size. In years when a brand’s BFCM lift grew, its BFCM AOV tended to fall, and doubling the lift went with about 6% lower AOV (correlation −0.23, after removing October’s change).
Discounts don’t explain much of it
Deeper discounts are the obvious suspect, but the codes we can see don’t show much. Among orders with a code, the discount runs only 1 to 2 points deeper on Black Friday than in October (about 16% of the order against 14%), and brands with the deepest codes don’t lift more (rank correlation −0.18 in 2024, −0.19 in 2025).
Codes are only part of the picture
Codes miss automatic sitewide discounts, so this isn’t the full picture of what brands offered.
How to plan for BFCM 2026
Why it matters: A low-priced brand that measures BFCM on order count will understate its result, because part of its win shows up in the basket.
Under $73 AOV: optimize for basket size with free-shipping thresholds, bundles and tiered spend-and-save. Judge BFCM on revenue per order as much as on orders.
Above $117: plan for the biggest spike in this data and staff fulfillment and CS for it.
Everyone: if you’re planning a deeper discount than last year, model a lower AOV alongside the higher order count.
4. BFCM runs three weeks, not four days
The median brand’s quarter breaks into six phases, and they land within a few days of the same place each year.
Six phases, mapped onto the 2026 calendar
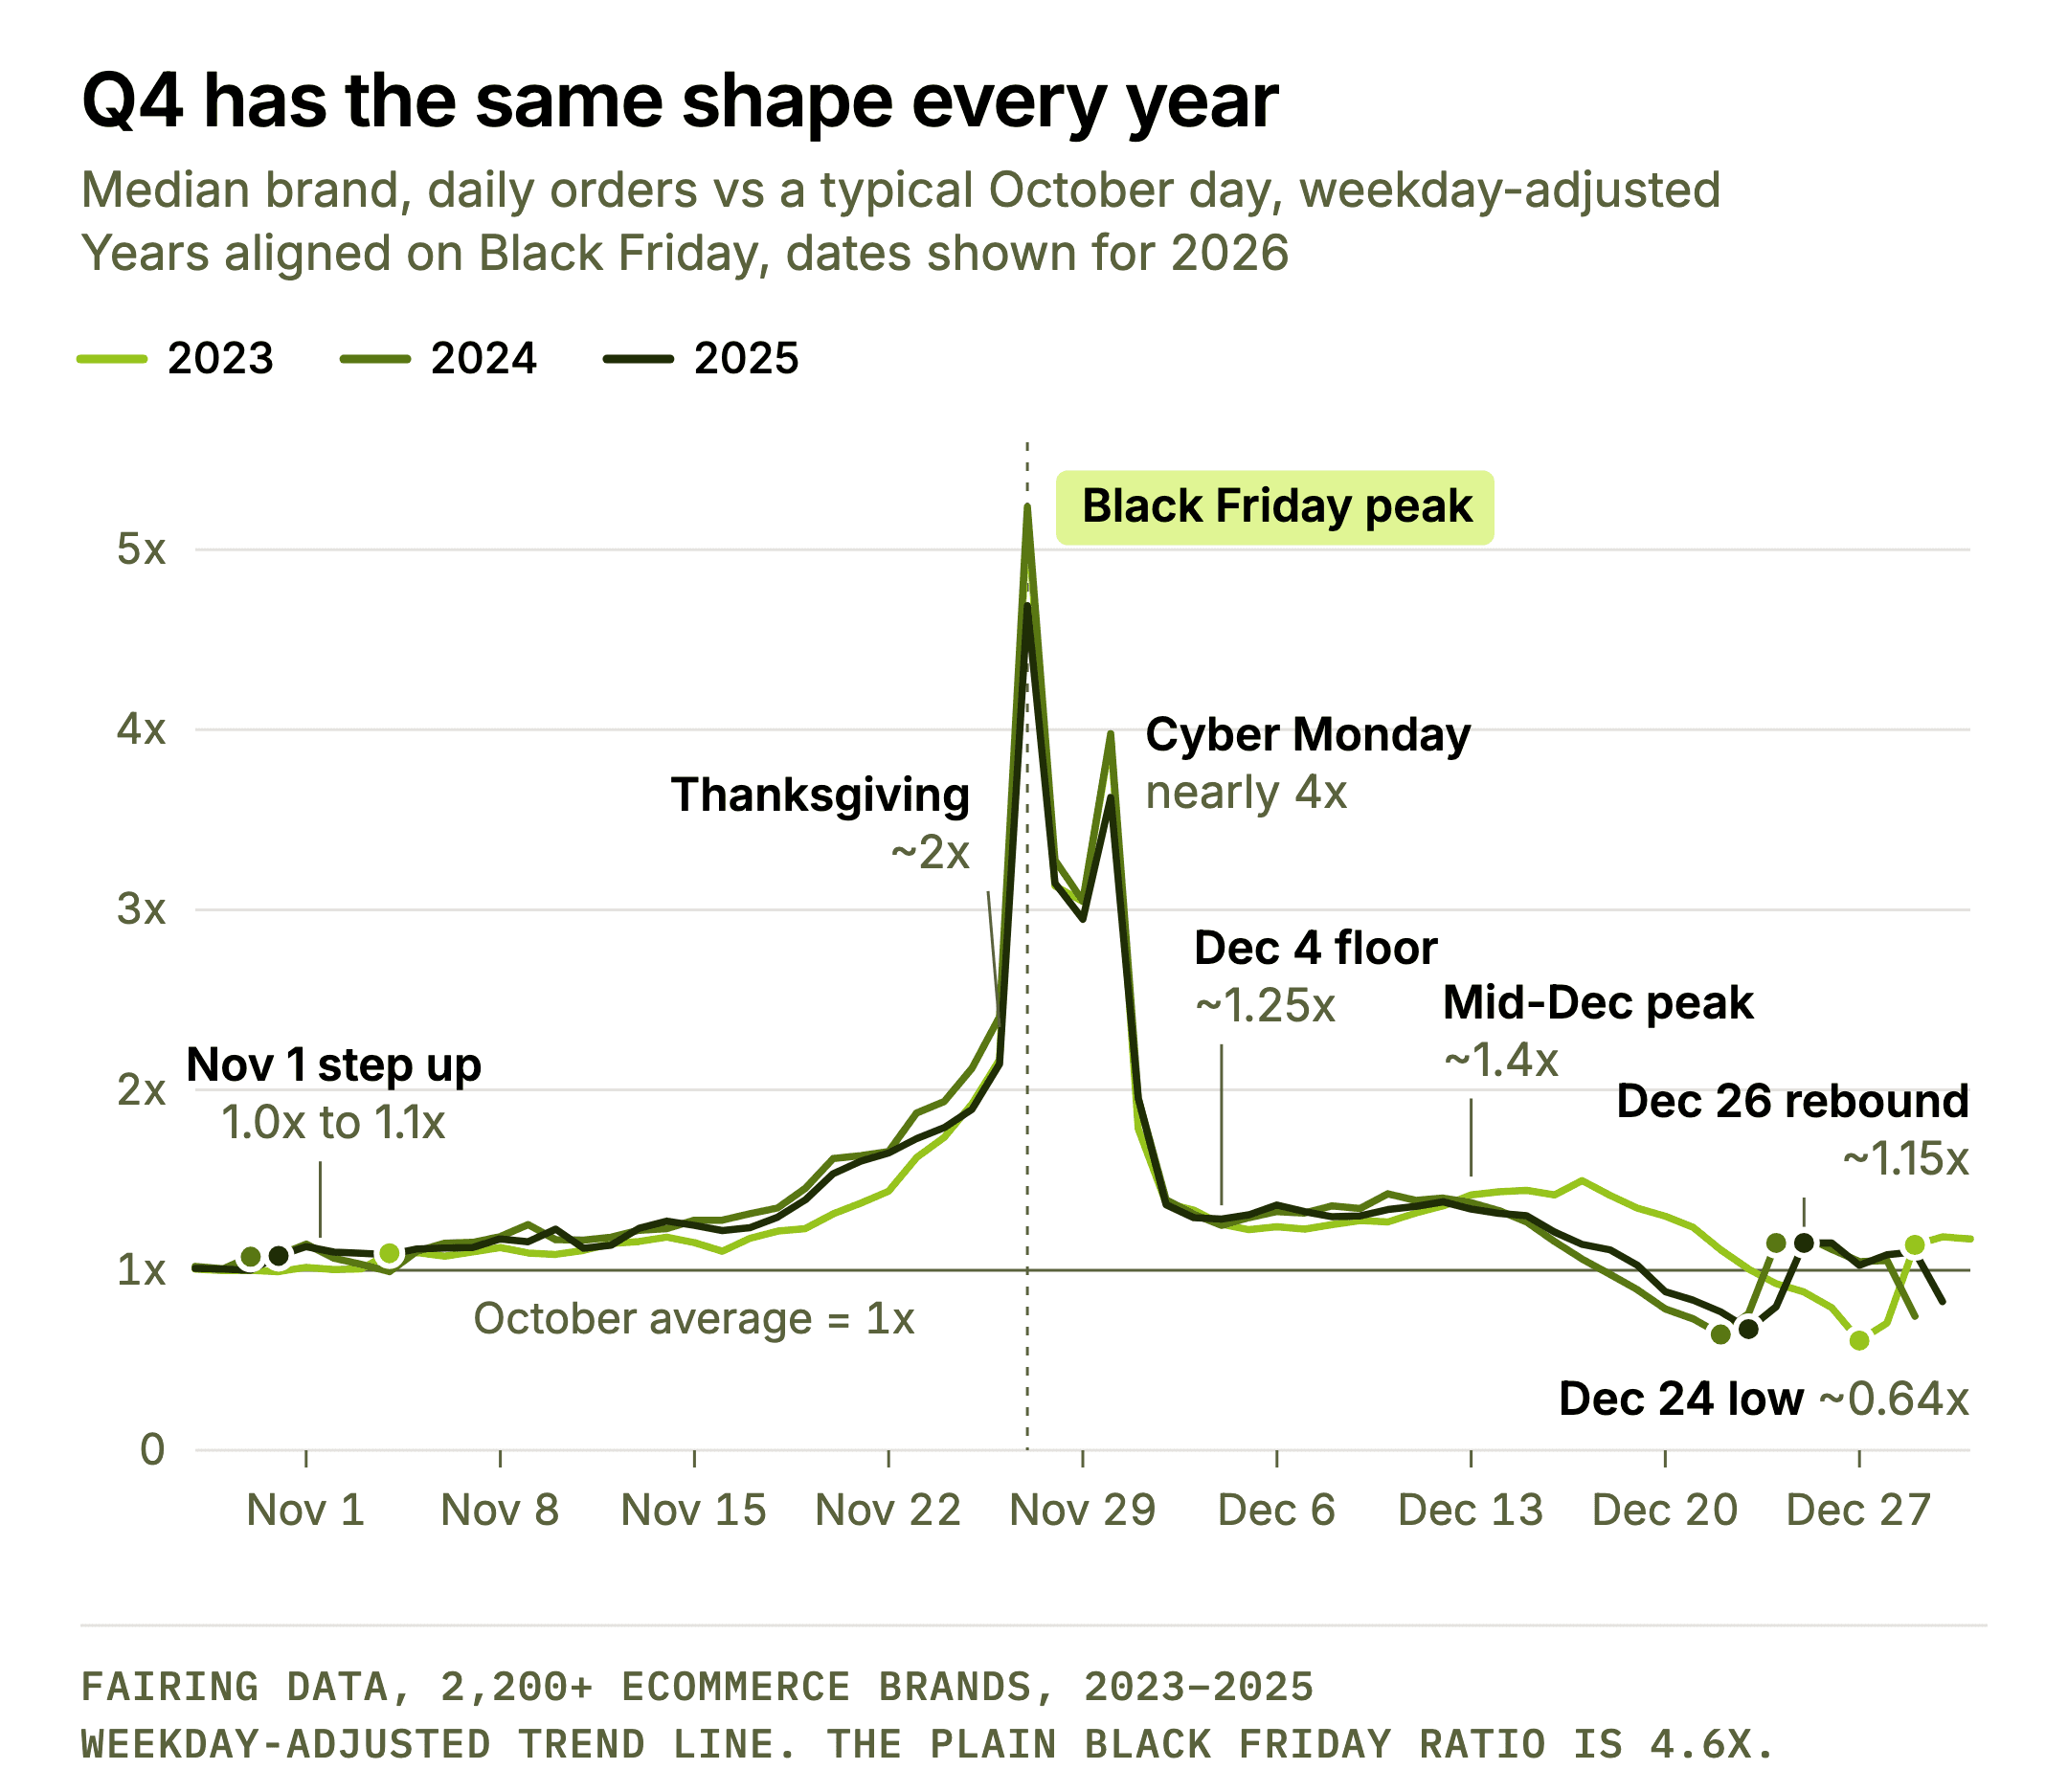
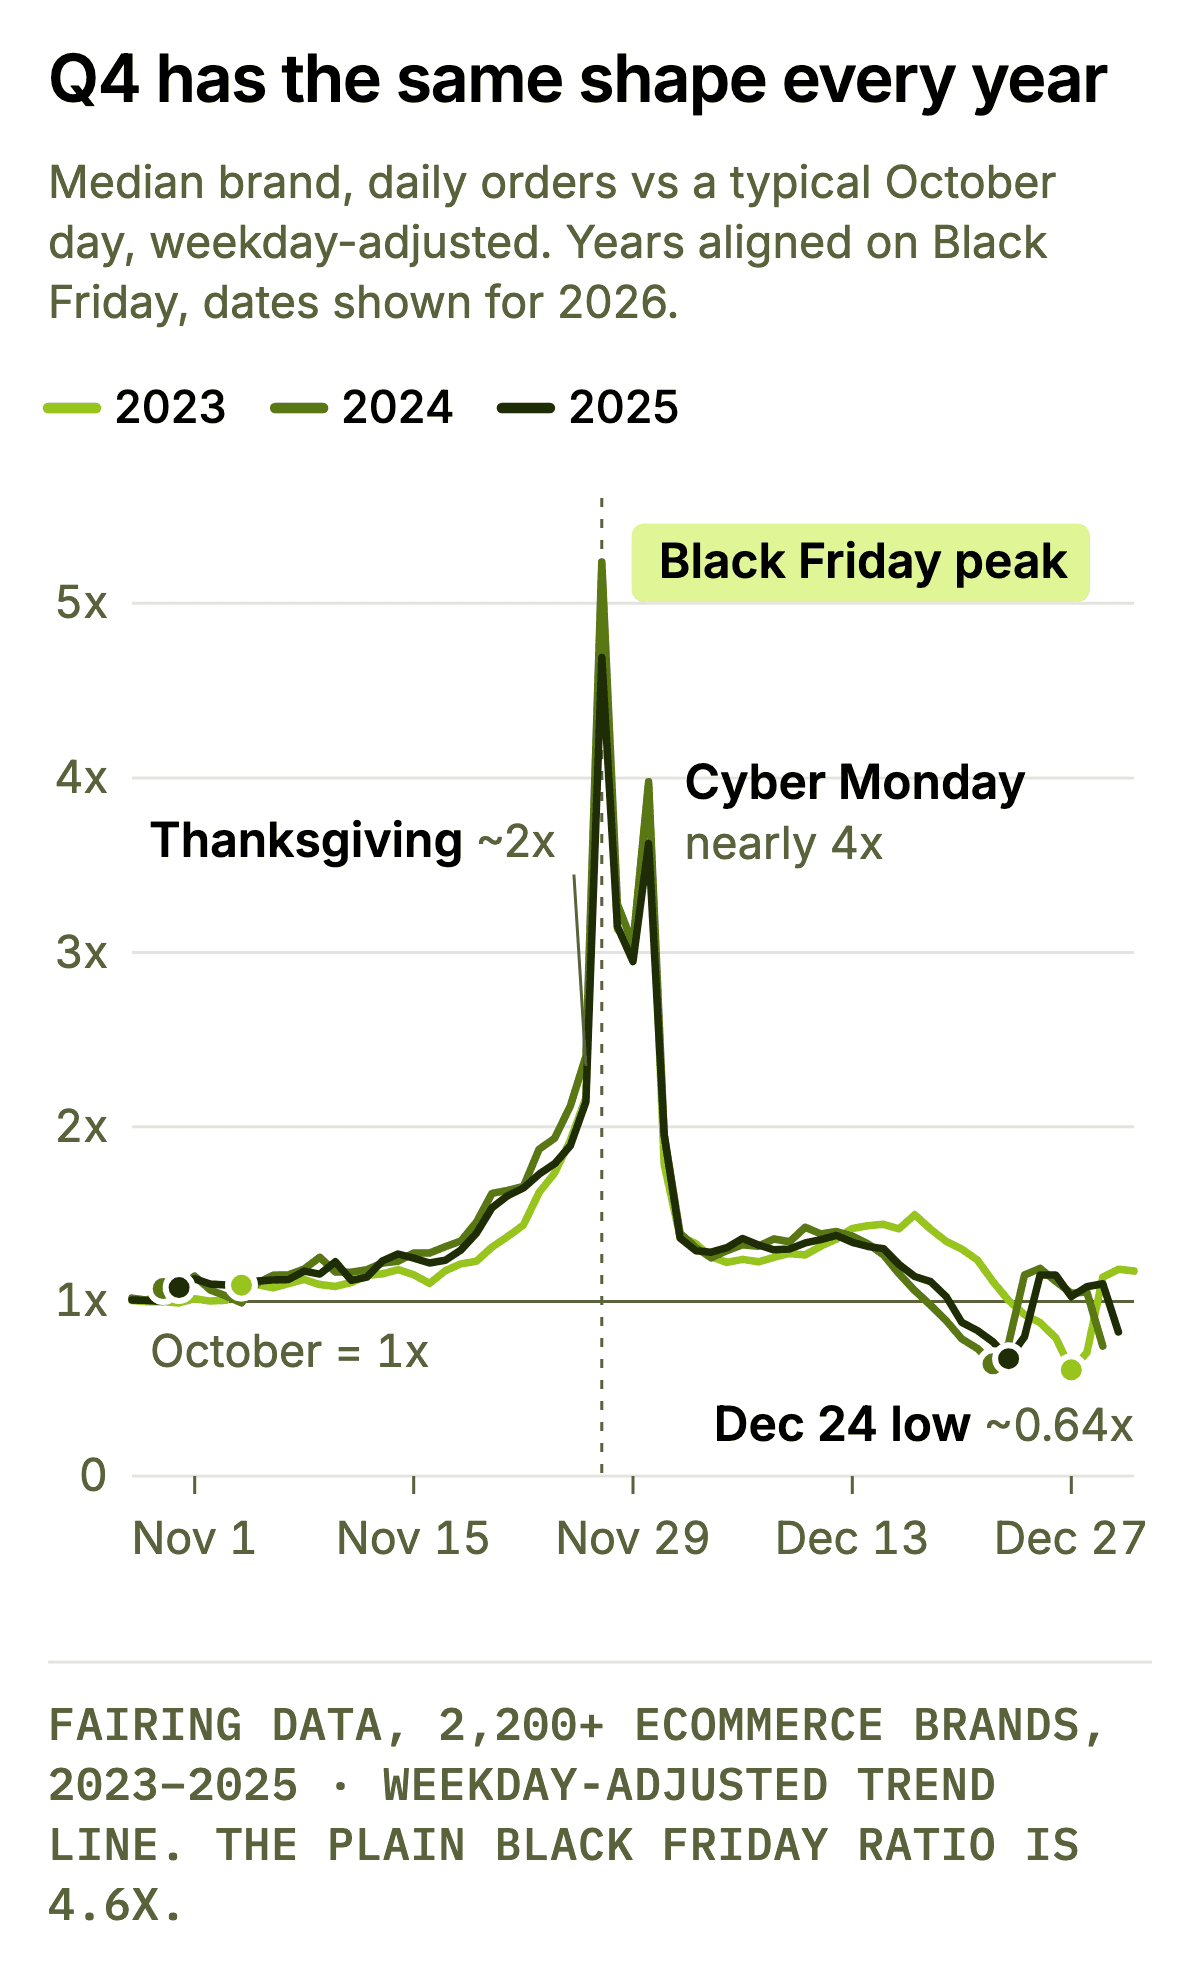
Orders step up on Nov 1 to about 1.1x October (section 5), then hold above 1.25x from about Nov 18 and cross 1.5x for the first time around the 21st. The peak runs Nov 26 to 30, Thanksgiving through Cyber Monday, with Black Friday the biggest day and Cyber Monday the second-biggest day of the year. The rest of the quarter breaks down like this:
Nov 1: the step up from October’s level.
Nov 18 to 21: the ramp.
Nov 26 to 30: the peak.
Dec 4: the post-BFCM floor, about 1.25x.
Dec 13: a December peak of about 1.4x.
Dec 24 to 26: a Christmas Eve low of about 0.65x, then a one-day bump on the 26th.
Half the quarter is booked before Thanksgiving week
By the Sunday before Thanksgiving week, the median brand has booked about half of its October-to-December orders. By the end of Cyber Monday it’s about 70%, or 65% in 2023, when Black Friday fell early, on the 24th. Only about 8% of the quarter lands from Dec 21 to 31, and the 30 days from Nov 16 to Dec 15 are a third of the quarter’s days but carry about 45% of its orders.
Extra orders land across three windows
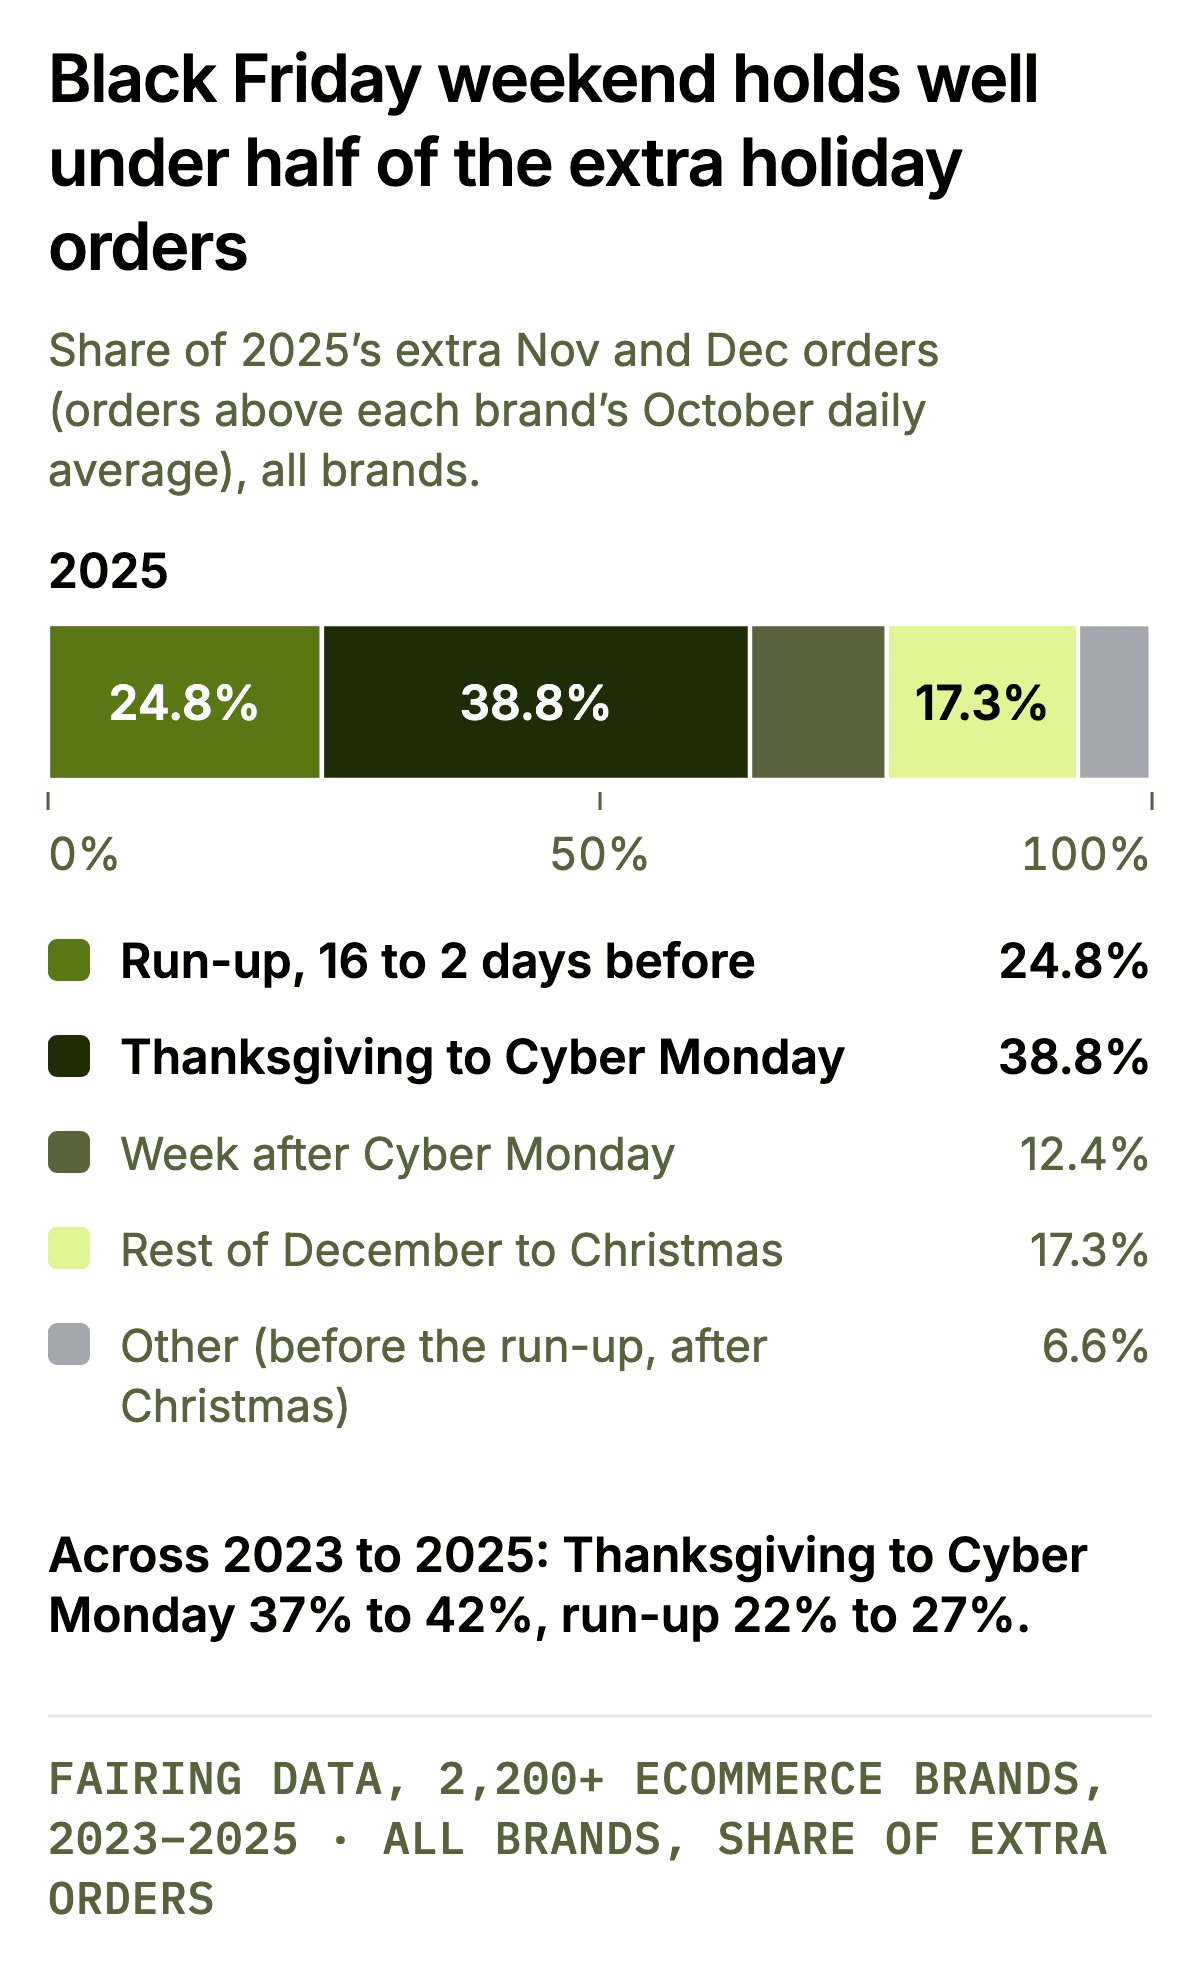
Extra orders are the ones above each brand’s normal October day. They land in three windows:
Thanksgiving through Cyber Monday: 42% in 2023, then 37% to 39% in 2024 and 2025.
The 15 days before Thanksgiving: 22% to 27%.
The week after Cyber Monday: 9% in 2023, about 11% since.
These shares count every order across all brands, so bigger brands weigh more, and they count only extra orders in November and December. Section 7’s figure that the Cyber 5 carries about 13% of the typical brand’s Q4 orders is a different cut: it covers the typical brand and all October-to-December orders, October included.

Black Friday moves, and so do the calendar windows
Black Friday fell on Nov 24 in 2023, Nov 29 in 2024 and Nov 28 in 2025. Every window above is counted from Black Friday itself, so the run-up and the weekend are like for like. The two windows tied to calendar dates aren’t:
| Black Friday | Days from Nov 1 to the run-up | Days from the end of Cyber week to Christmas |
|---|---|---|
| 2023 (Nov 24) | 7 | 21 |
| 2024 (Nov 29) | 12 | 16 |
| 2025 (Nov 28) | 11 | 17 |
| 2026 (Nov 27) | 10 | 18 |
Early November’s share jumped in 2024 and December’s fell, because 2024 had five more days of early November and five fewer days of December. Per day, December was steady at about 1% of the season’s extra orders a day in all three years, so for 2026 expect a December share in line with 2025.
The run-up starts earlier than in 2023
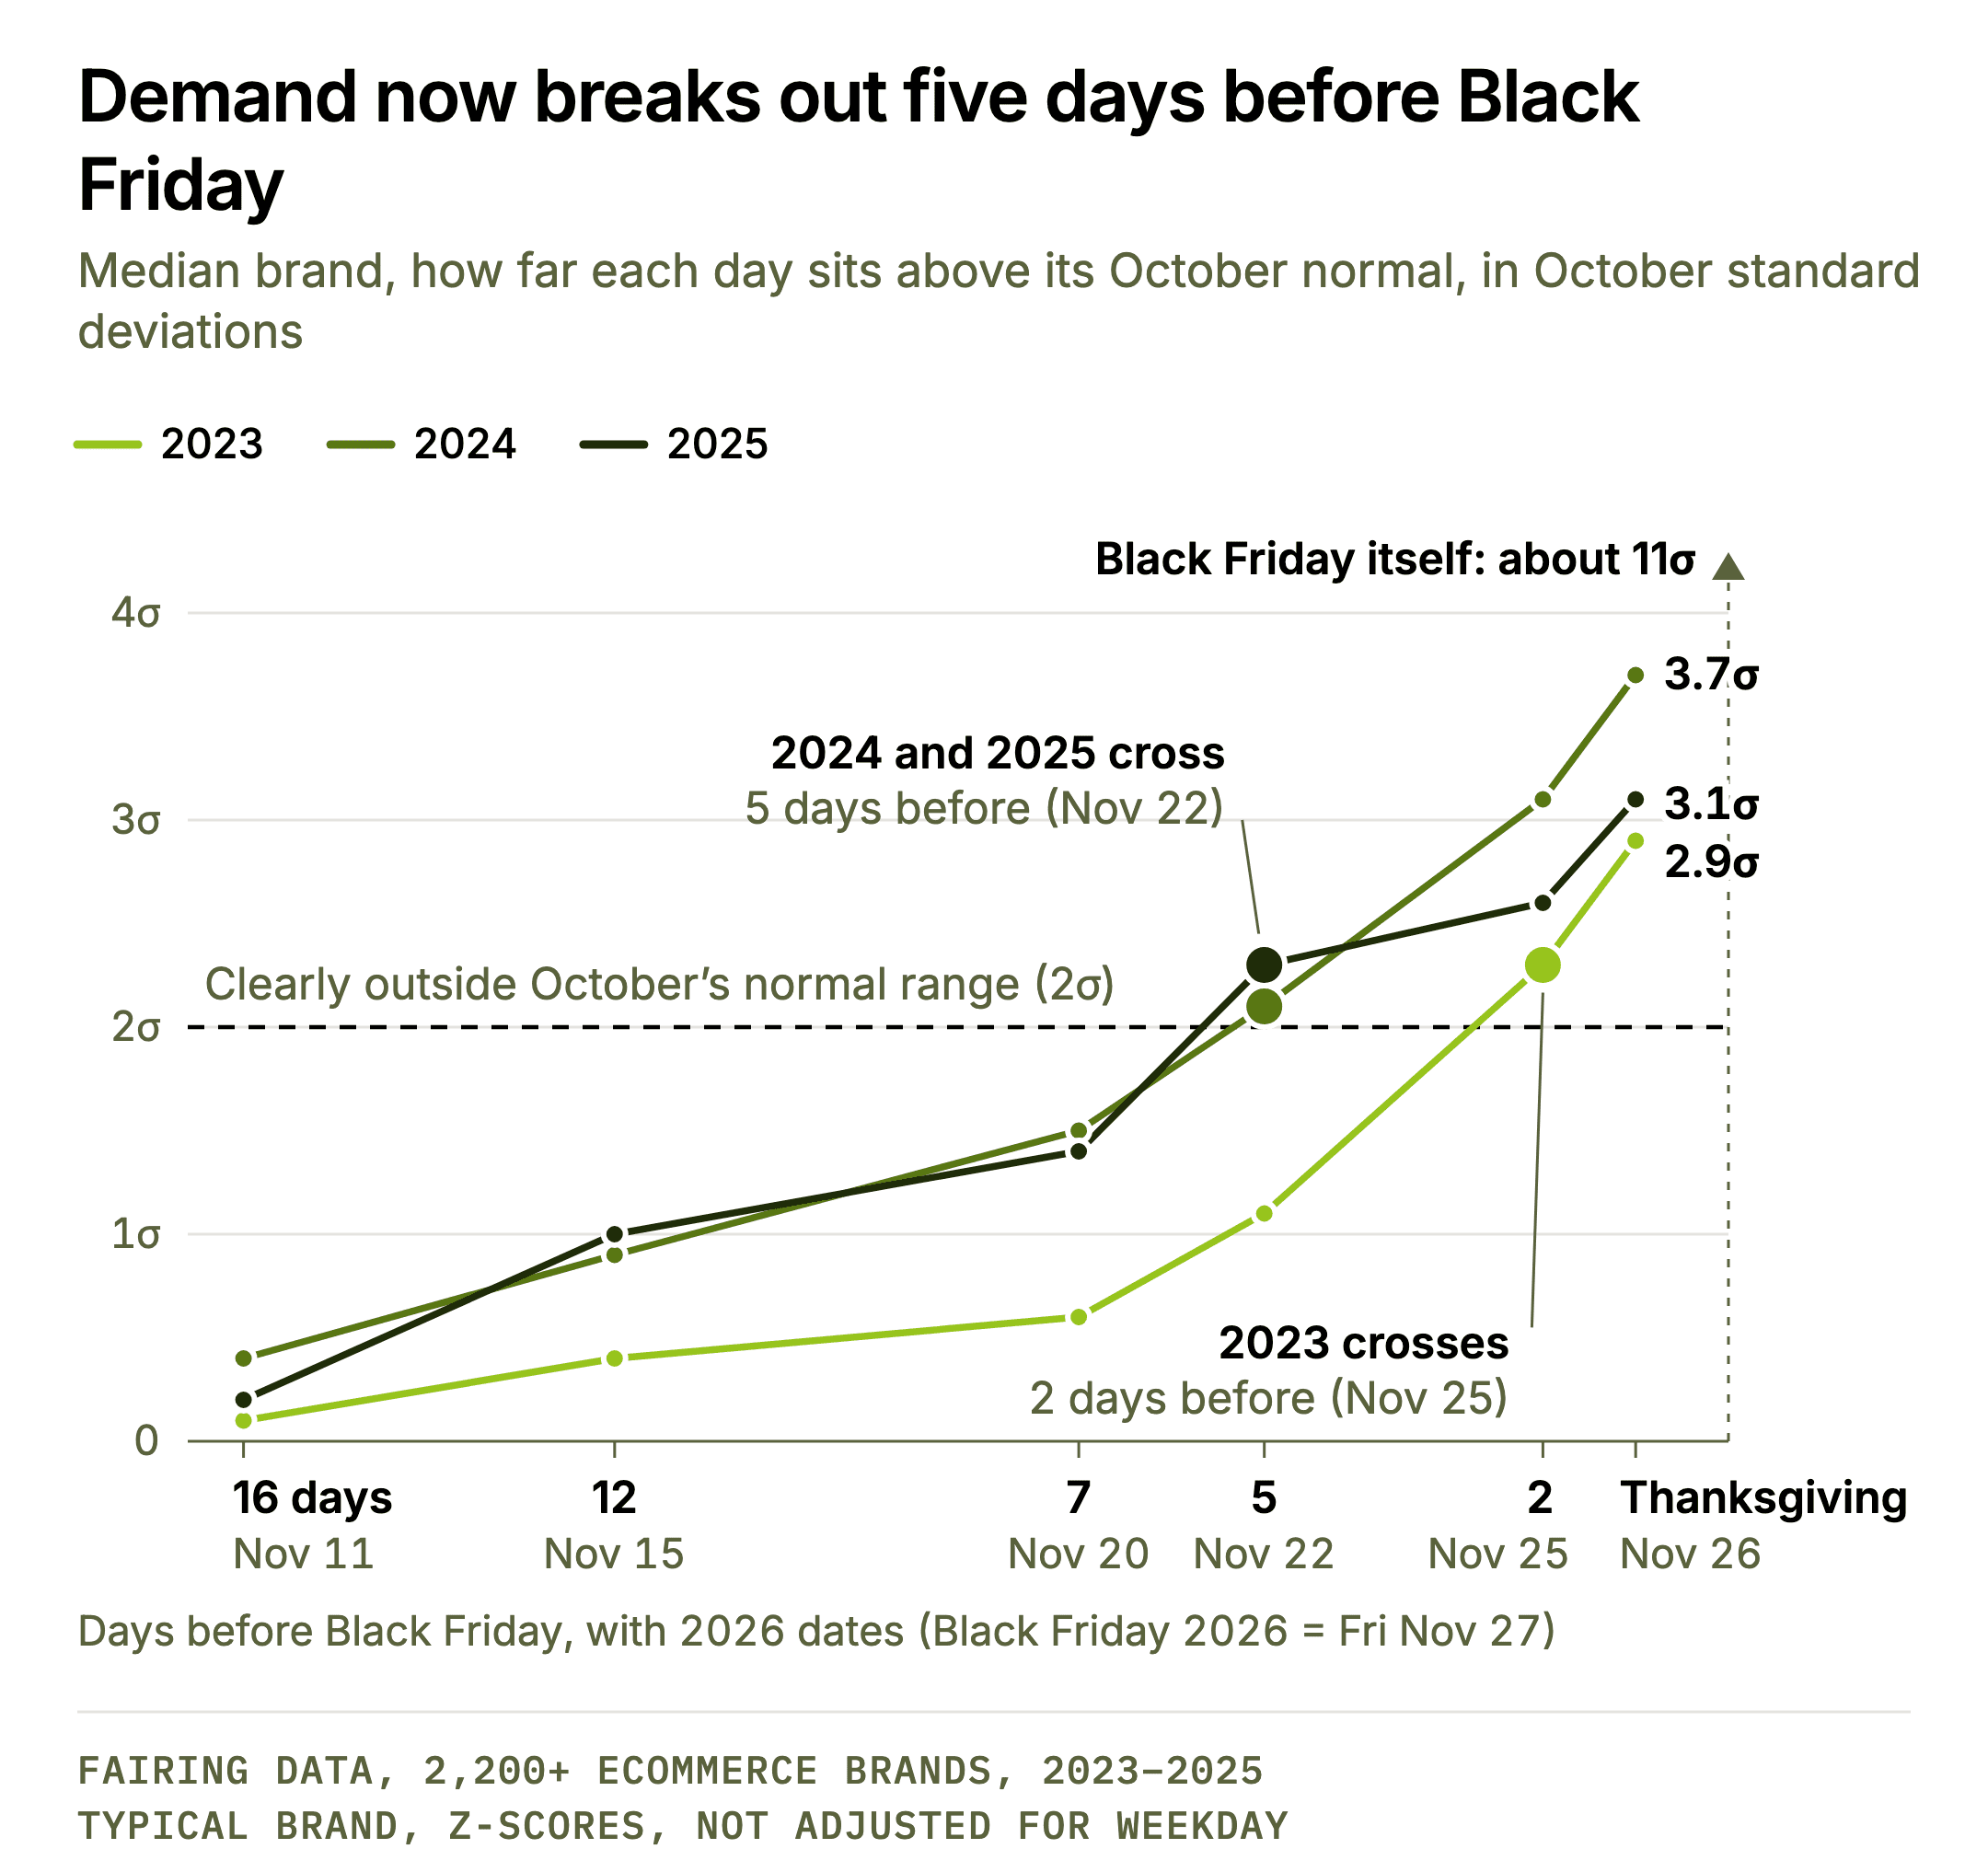
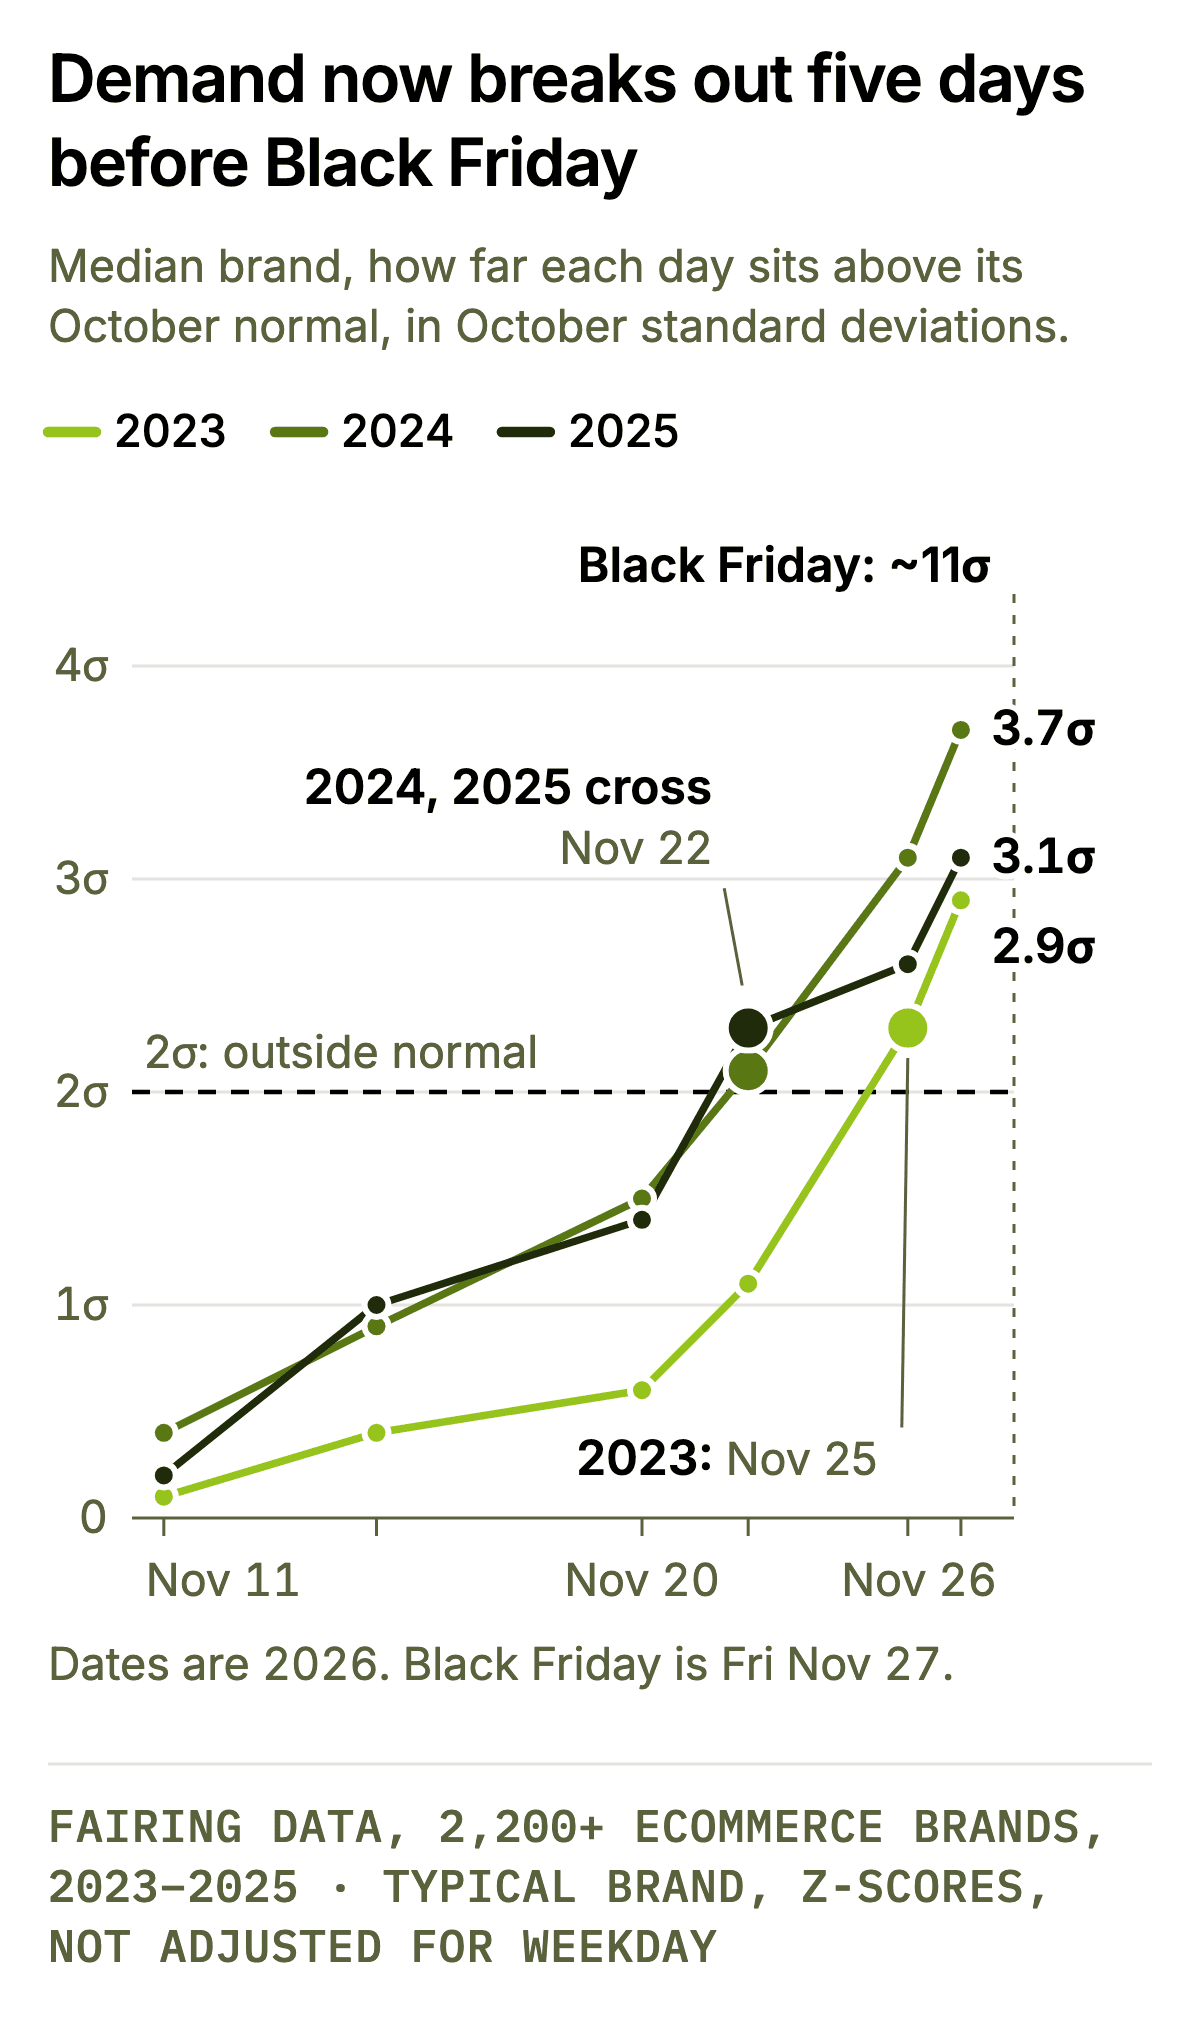
We measured how far each day sits above a brand’s normal October range, in standard deviations of that brand’s own October daily orders. A reading of 2 means the day is clearly outside anything a normal October produces. The median brand crossed that line two days before Black Friday in 2023, and five days before in both 2024 and 2025.
About one brand in five is already past it 16 days out, and even three weeks out, 16% are, because single high days are common. One day above the line isn’t a signal. Several in a row is.
Daily orders have fat tails
If daily DTC orders followed a bell curve, about 2% of brands would sit more than 2 standard deviations above normal on any random day. Three weeks before Black Friday, 16% already do, and 10% are past 3, because emails, launches and promos cause frequent spikes. For whoever builds your forecast: staff from your own historical percentiles (your 90th-percentile day, say), not from an average plus a couple of standard deviations.
How to plan for BFCM 2026
Why it matters: Half your quarter is booked by Nov 22, so a soft pre-Thanksgiving week is a real miss, and grading BFCM on Friday to Monday covers less than half the extra demand.
Put these 2026 dates on the calendar: Sun Nov 1, Wed Nov 11, Wed Nov 18, Sat Nov 21, Thu Nov 26, Mon Nov 30, Fri Dec 4, Sun Dec 13 and Thu Dec 24.
Nov 1, Dec 13 and Dec 24 are calendar dates.
The rest are three-year averages mapped onto Black Friday 2026. In any single year they moved by one to three days.
Plan budget, inventory and creative on a three-week calendar that starts around Wed Nov 11, 16 days before Black Friday.
Score the season on extra orders from Nov 1 to Dec 31, against October. Keep Black Friday as one line in that scorecard, not the headline.
Expect your own breakout around Sun Nov 22. Several days in a row above your normal October range a week earlier is a real early start. One high day isn’t.
5. Orders step up on November 1st
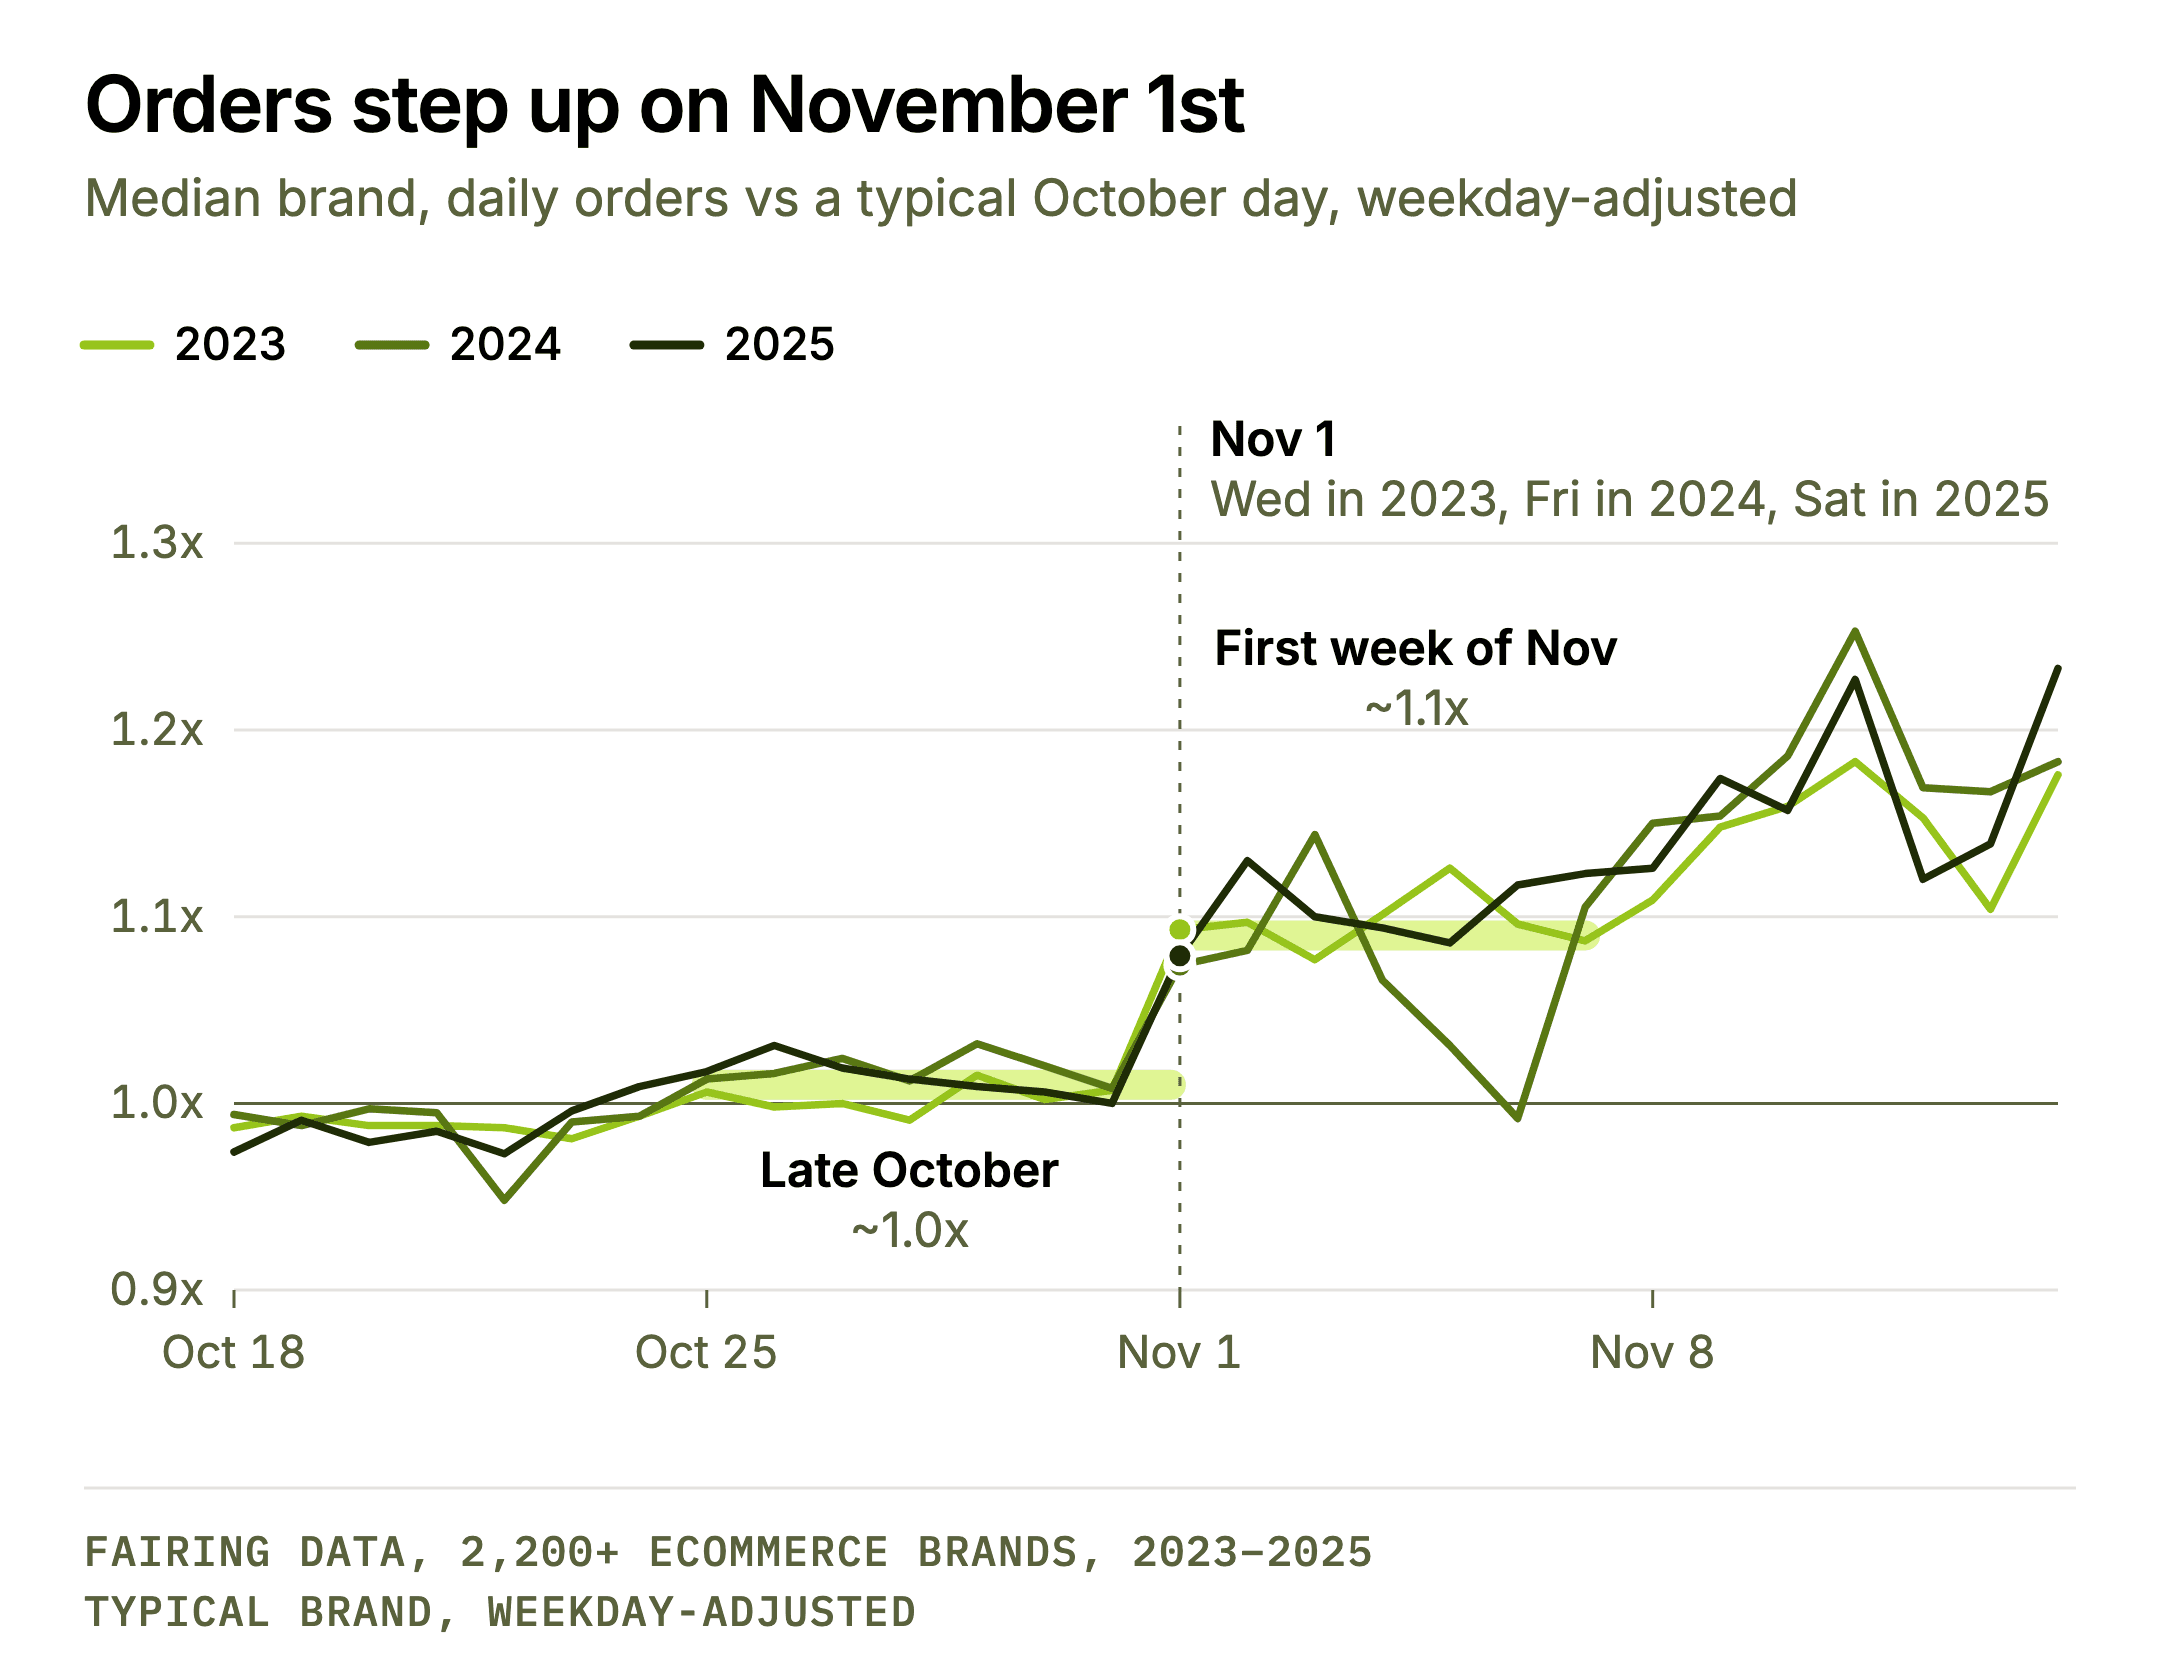
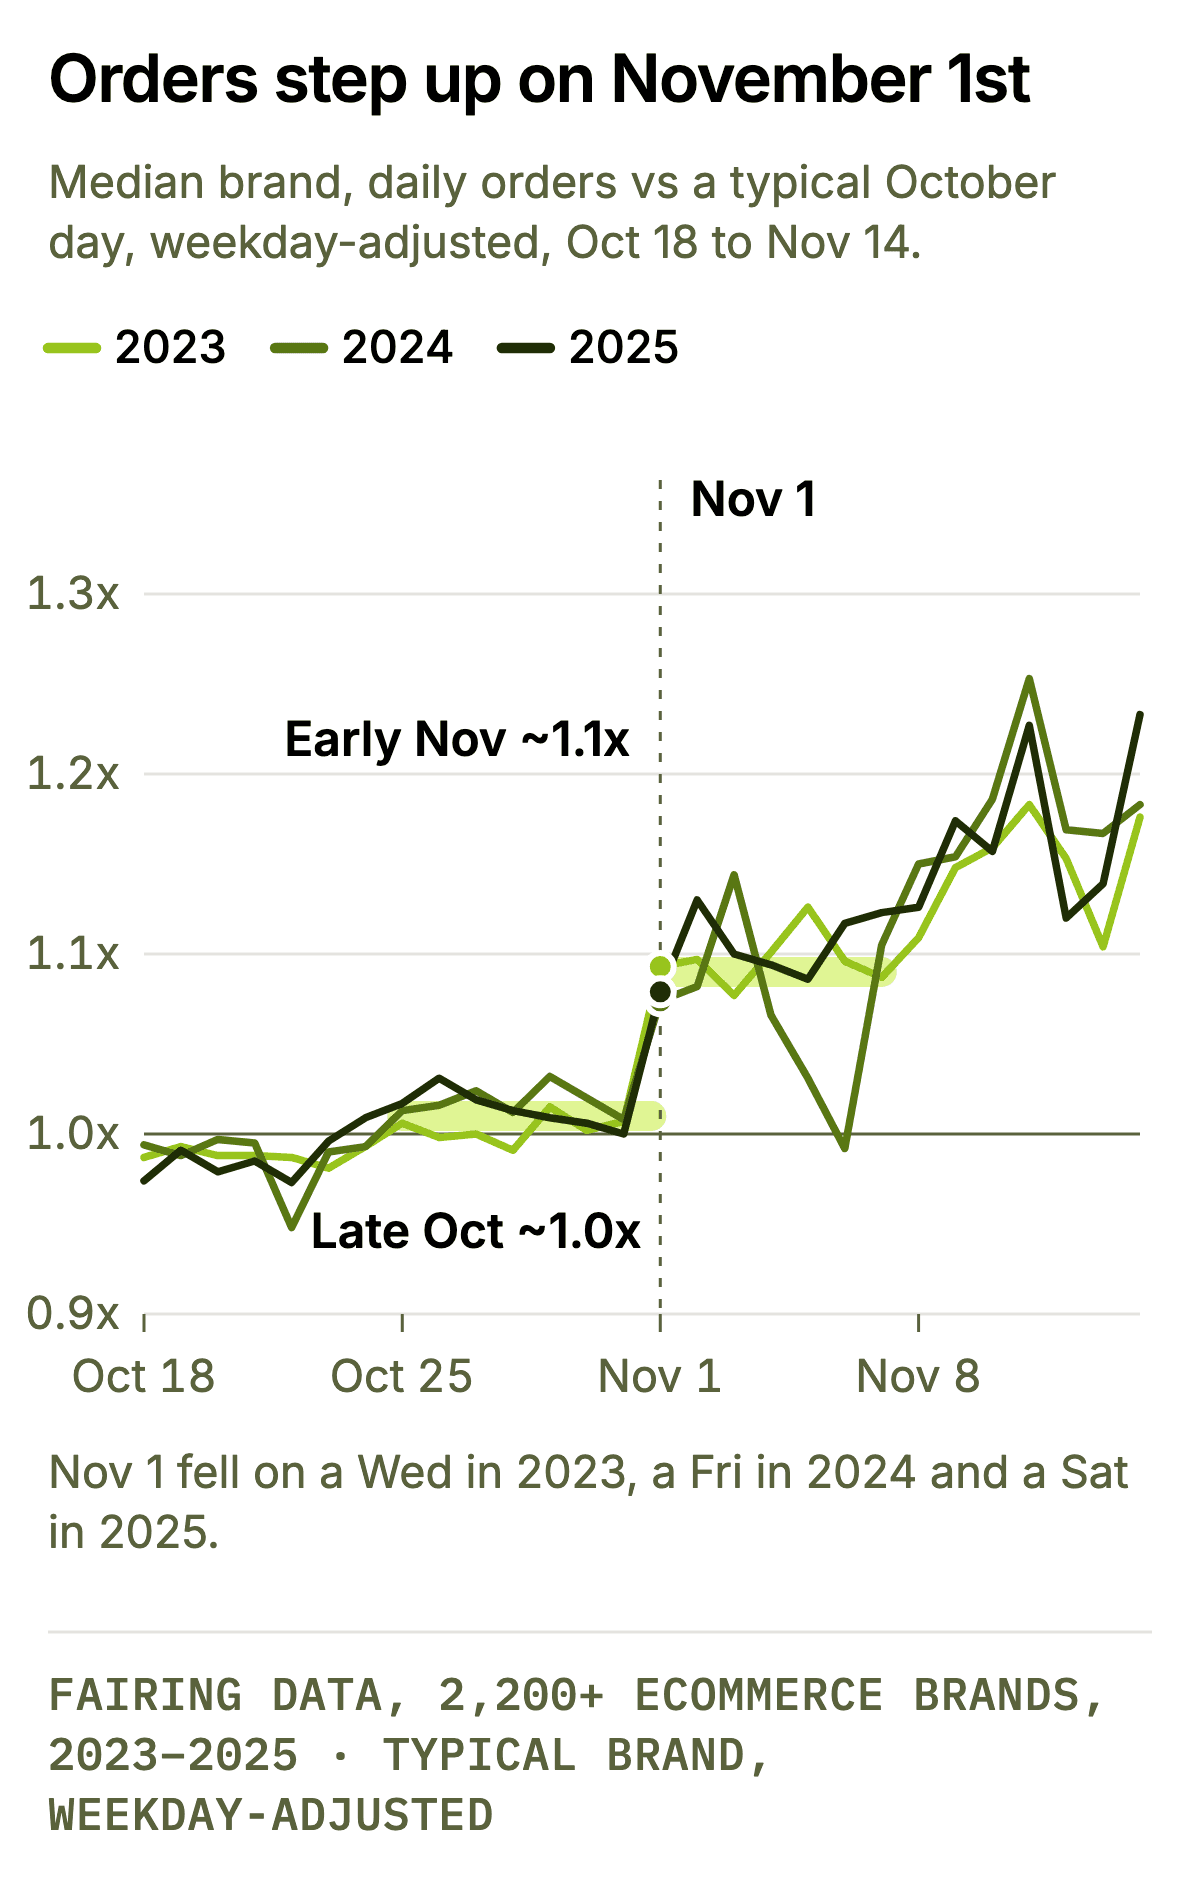
Orders step up about 10% on November 1st itself, in each of the three years.
The step lands on the date, not the weekday
November 1st was a Wednesday in 2023, a Friday in 2024 and a Saturday in 2025, and the step landed on the date each time. Orders ran at about 1.0x in the last week of October, 1.07x to 1.09x on November 1st and 1.13x to 1.15x through the first half of November.
How to plan for BFCM 2026
Why it matters: From Nov 1, your store is no longer running at normal volume, so any baseline you need for BFCM has to come from October.
Pin down your October baselines, including your October average daily orders (October orders divided by 31). That’s the denominator for the pacing table, and it stays fixed from Nov 1 on.
Get anything that needs a clean baseline live before volume steps up on Nov 1. A question about problems on the way to purchase needs weeks of normal data under it. The setup is in our BFCM checklist.
Treat Nov 1 to 14 as October plus 10 to 15%. A brand at 1.0x on Nov 10 is a little behind the median and nowhere near trouble.
6. Bigger run-ups didn’t come with smaller Black Fridays
The week before Thanksgiving is the one to watch, and a bigger run-up did not cost brands their Black Friday.
The ramp saves its biggest step for the week before Thanksgiving
The median brand’s weekly multiples, on numbers you can calculate yourself, climb slowly and then jump:
Nov 2 to 8: 1.07x.
Nov 9 to 15: 1.16x.
Nov 16 to 22: 1.40x.
That last week predicts your Black Friday
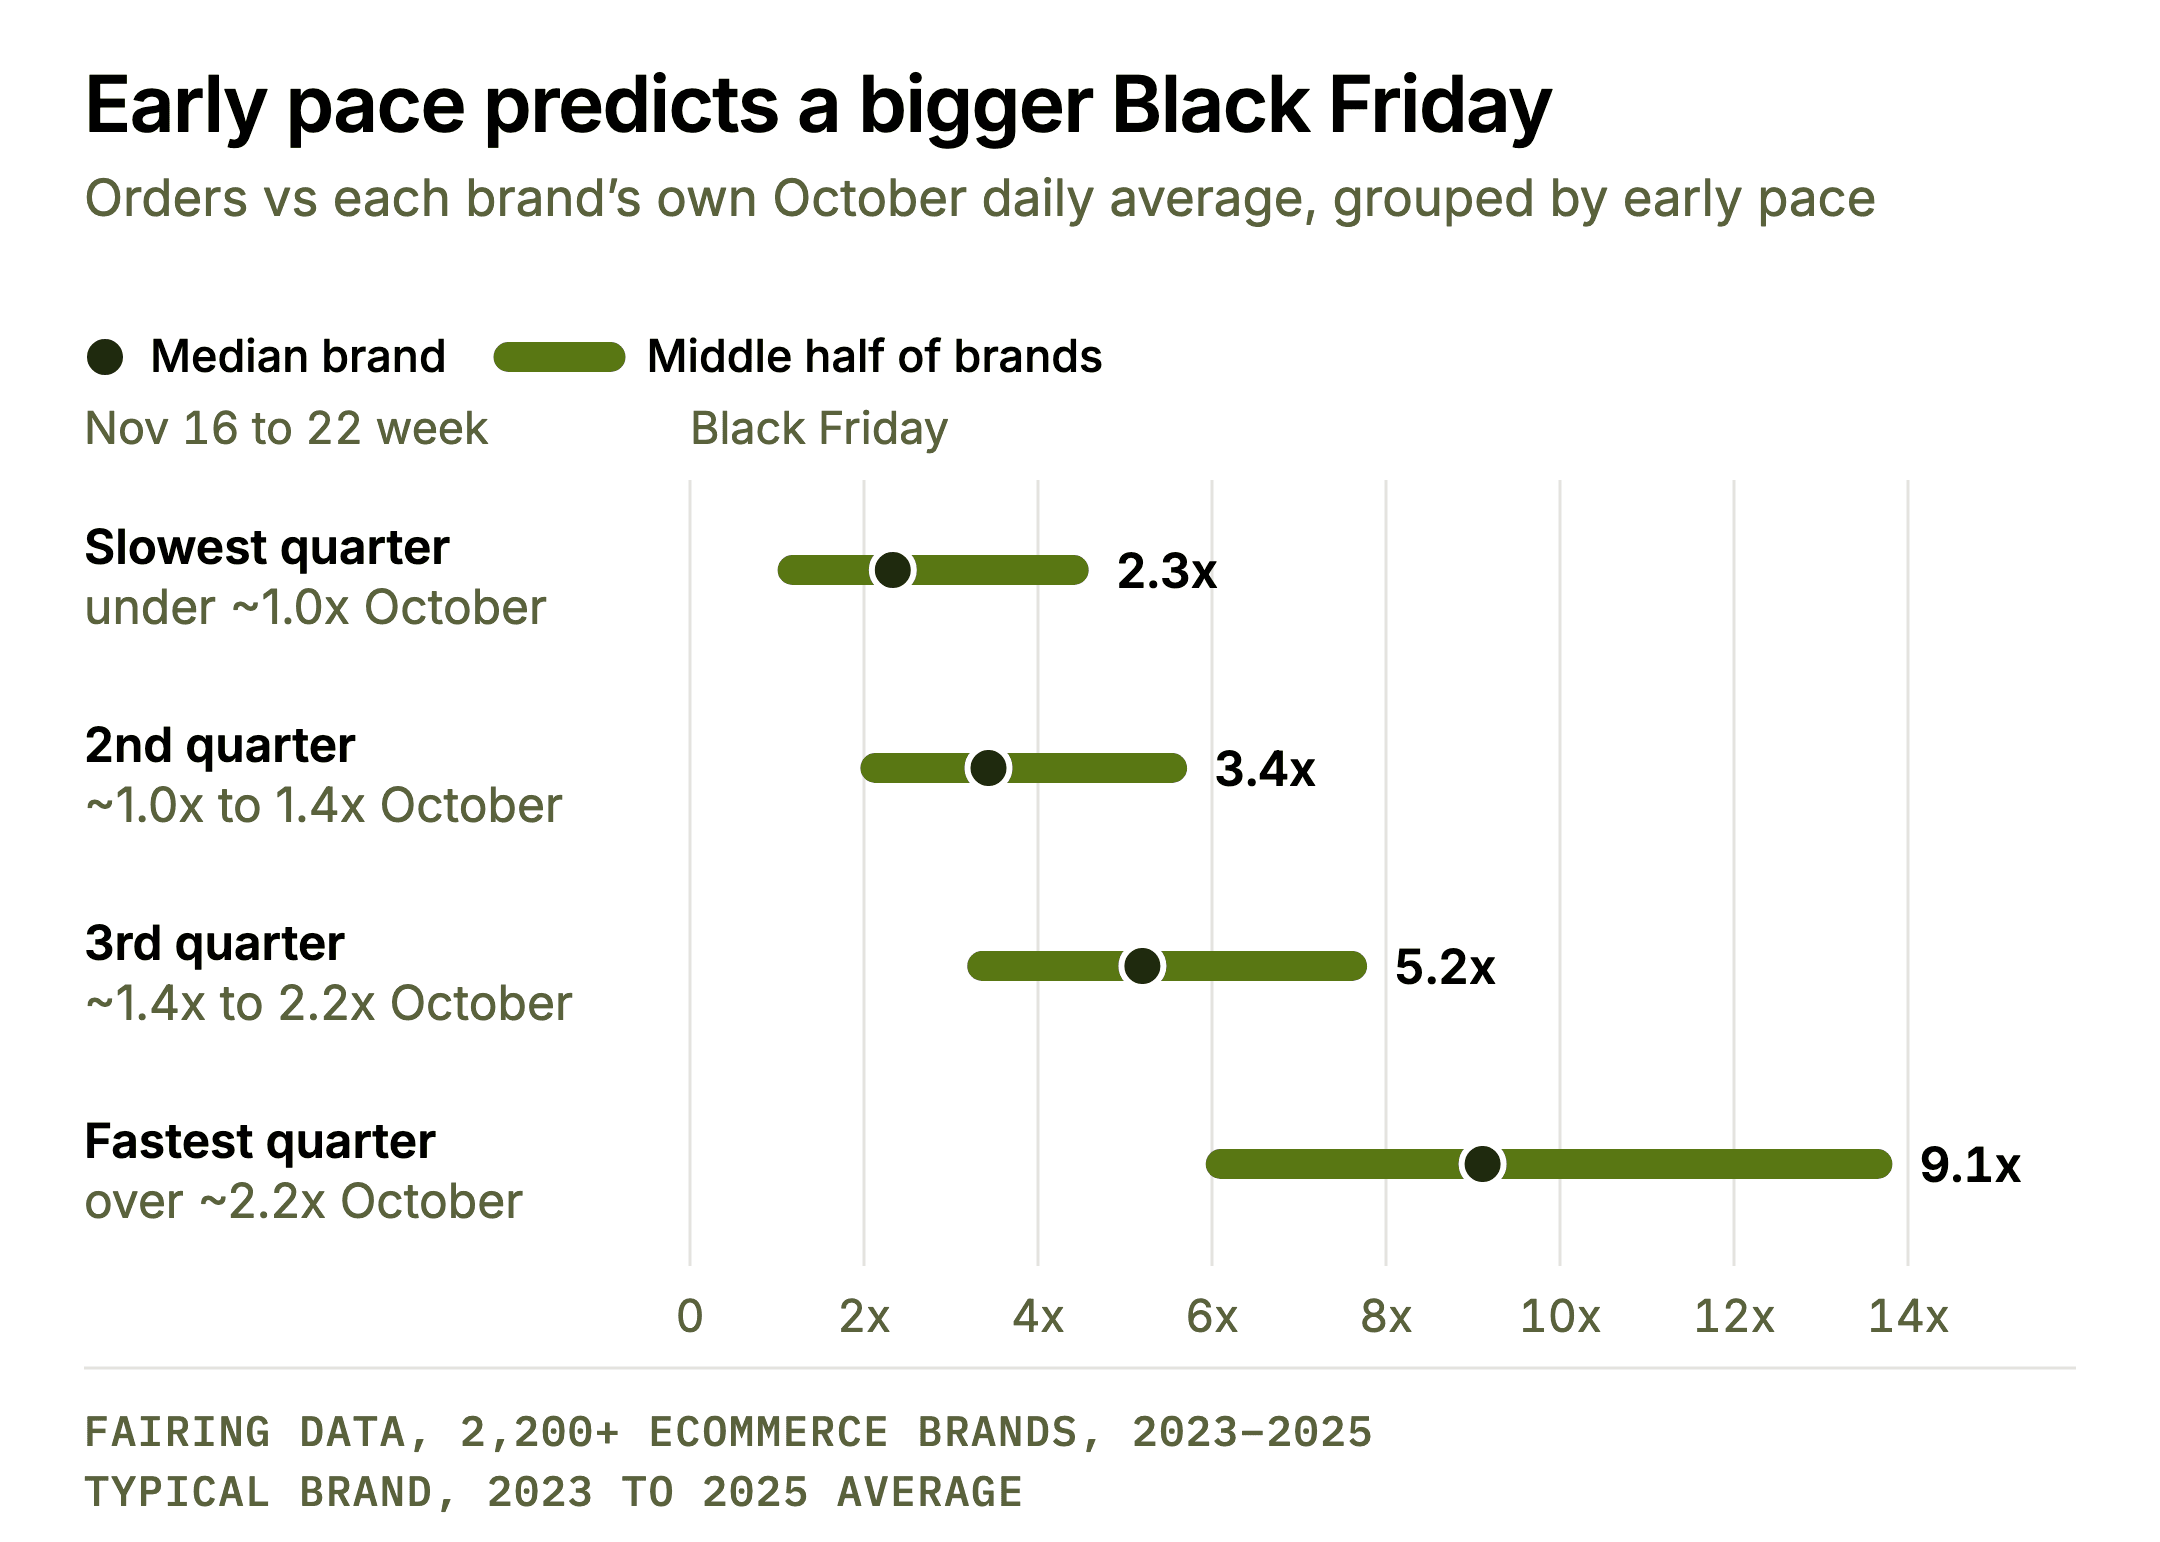
We ranked every brand by its Nov 16 to 22 multiple and again by its Black Friday multiple. The rank correlation between the two (1.0 is a perfect match, 0 is none) was 0.52 in 2023, 0.58 in 2024 and 0.63 in 2025. The week before scored only 0.34 to 0.46, so the read sharpens as Black Friday gets closer.
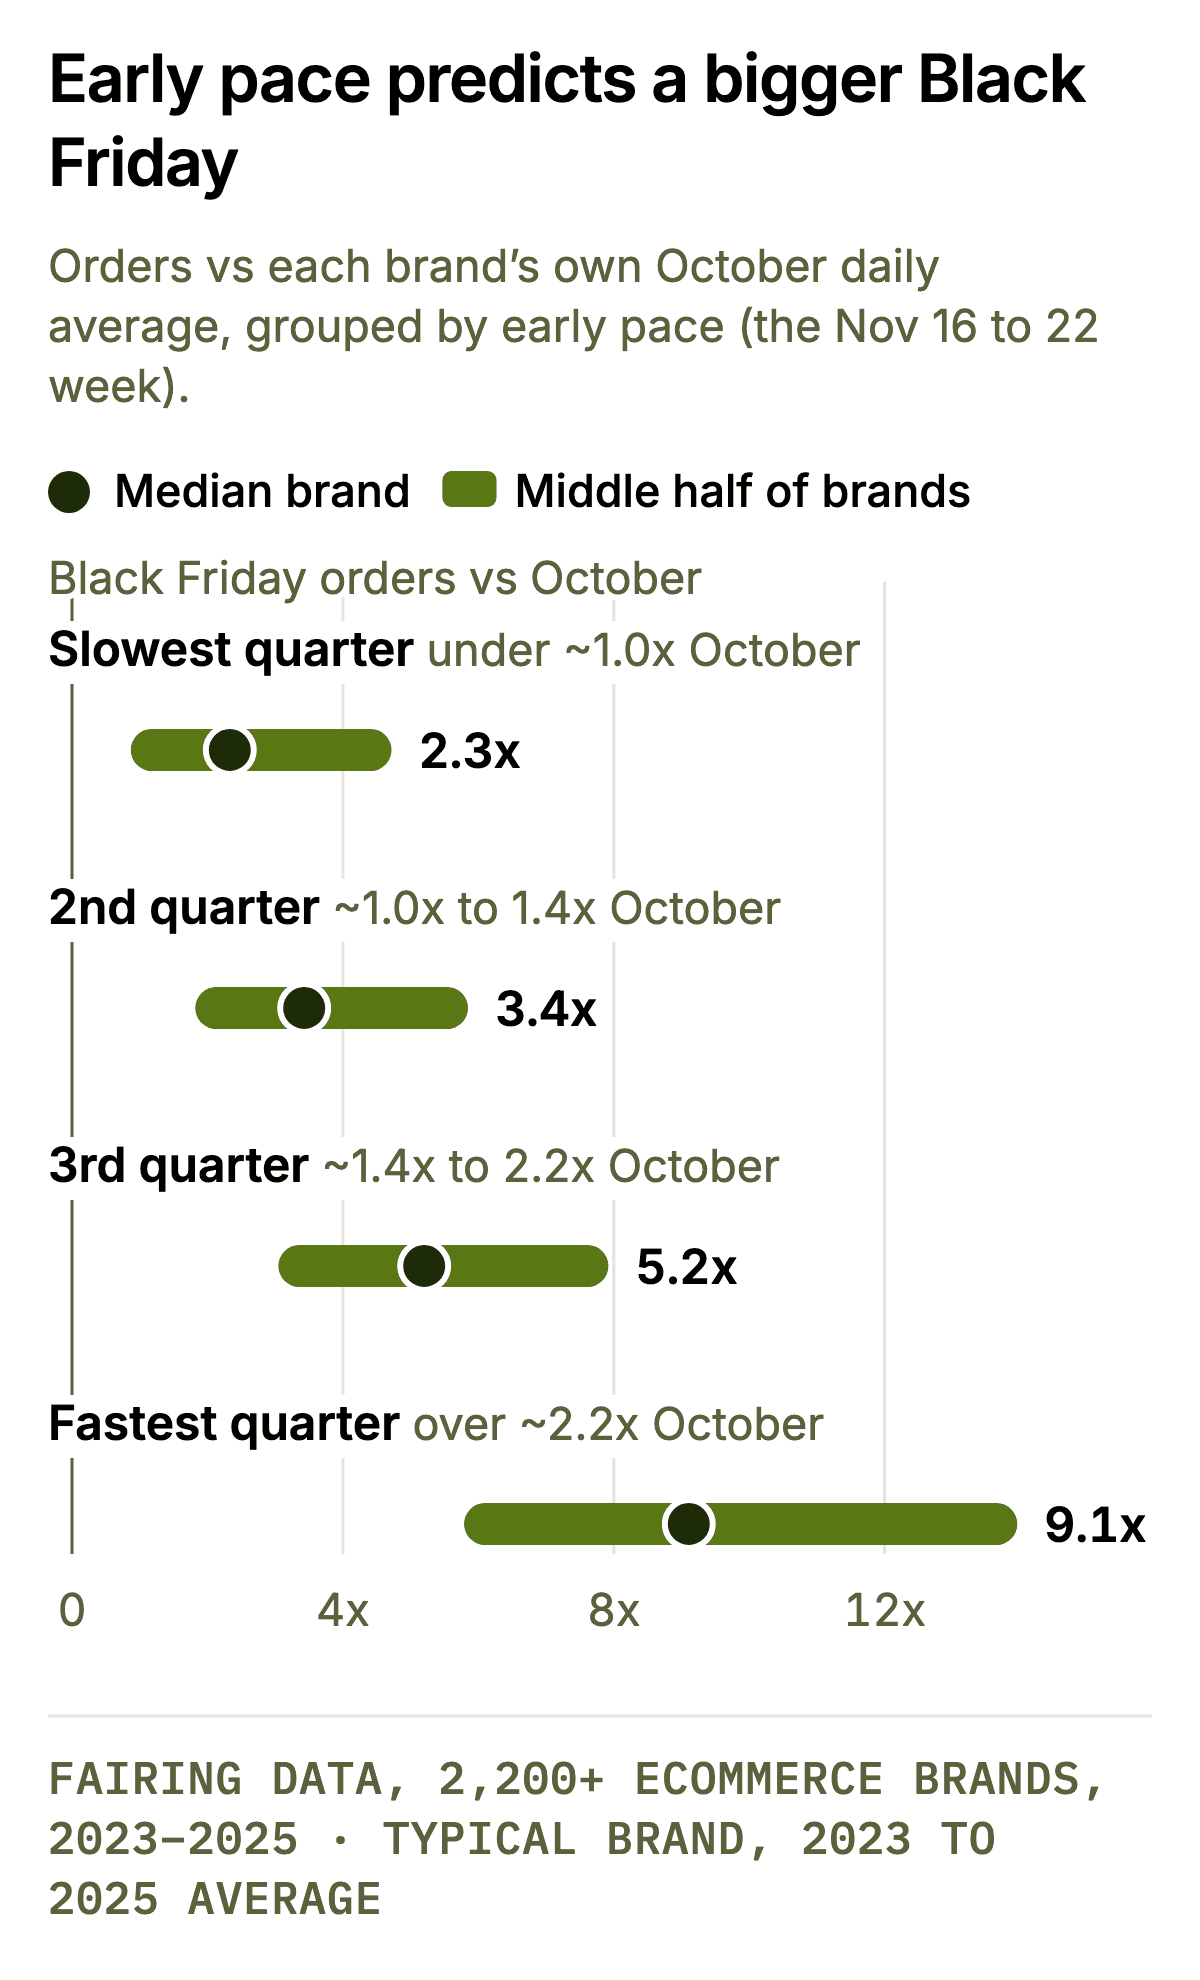
Brands that grew their run-up kept their Black Friday
That comparison is across brands, so it could just mean big brands are big all season. The stronger test compares each brand with itself: the same brands in consecutive years. When a brand grew its run-up from one year to the next, its Black Friday grew too.
If early access pulled orders forward, a bigger run-up would come with a smaller Black Friday. The changes moved together instead (correlation 0.56), after removing any change in the brand’s own October. A bigger BFCM also came with a bigger week after (0.66) and a bigger December gifting window (0.46).
| Year-over-year change, same brand | Correlation | After removing October's change |
|---|---|---|
| Run-up and Black Friday | 0.73 | 0.56 |
| BFCM and the week after | 0.79 | 0.66 |
| BFCM and December gifting | 0.64 | 0.46 |
This is observational
A brand having a good year, with better creative, more spend or a hit product, would lift every window at once, and the data measures run-up volume, not whether a brand ran an early-access offer. So it’s strong evidence against heavy cannibalization. It can’t rule out some pull-forward hidden inside a good year, or prove that early access creates demand.
How to plan for BFCM 2026
Why it matters: Brands that grew their run-up didn’t, on average, give back Black Friday to do it, and Nov 16 to 22 hands you your own data five days before the spike.
If you held back early access in 2025 to protect Black Friday, test it in 2026 on part of your existing list, so you can compare.
On Mon Nov 23, divide your Nov 16 to 22 average daily orders by your October average.
The median brand lands at 1.40x. The top quarter is above 2.17x.
If that’s you, plan Thanksgiving-to-Cyber-Monday capacity toward the top-quarter column of the pacing table in section 13.
Have peak CS staffing in place by Sat Nov 21, the typical first 1.5x day. Thanksgiving morning is late.
7. Thanksgiving to Cyber Monday, day by day
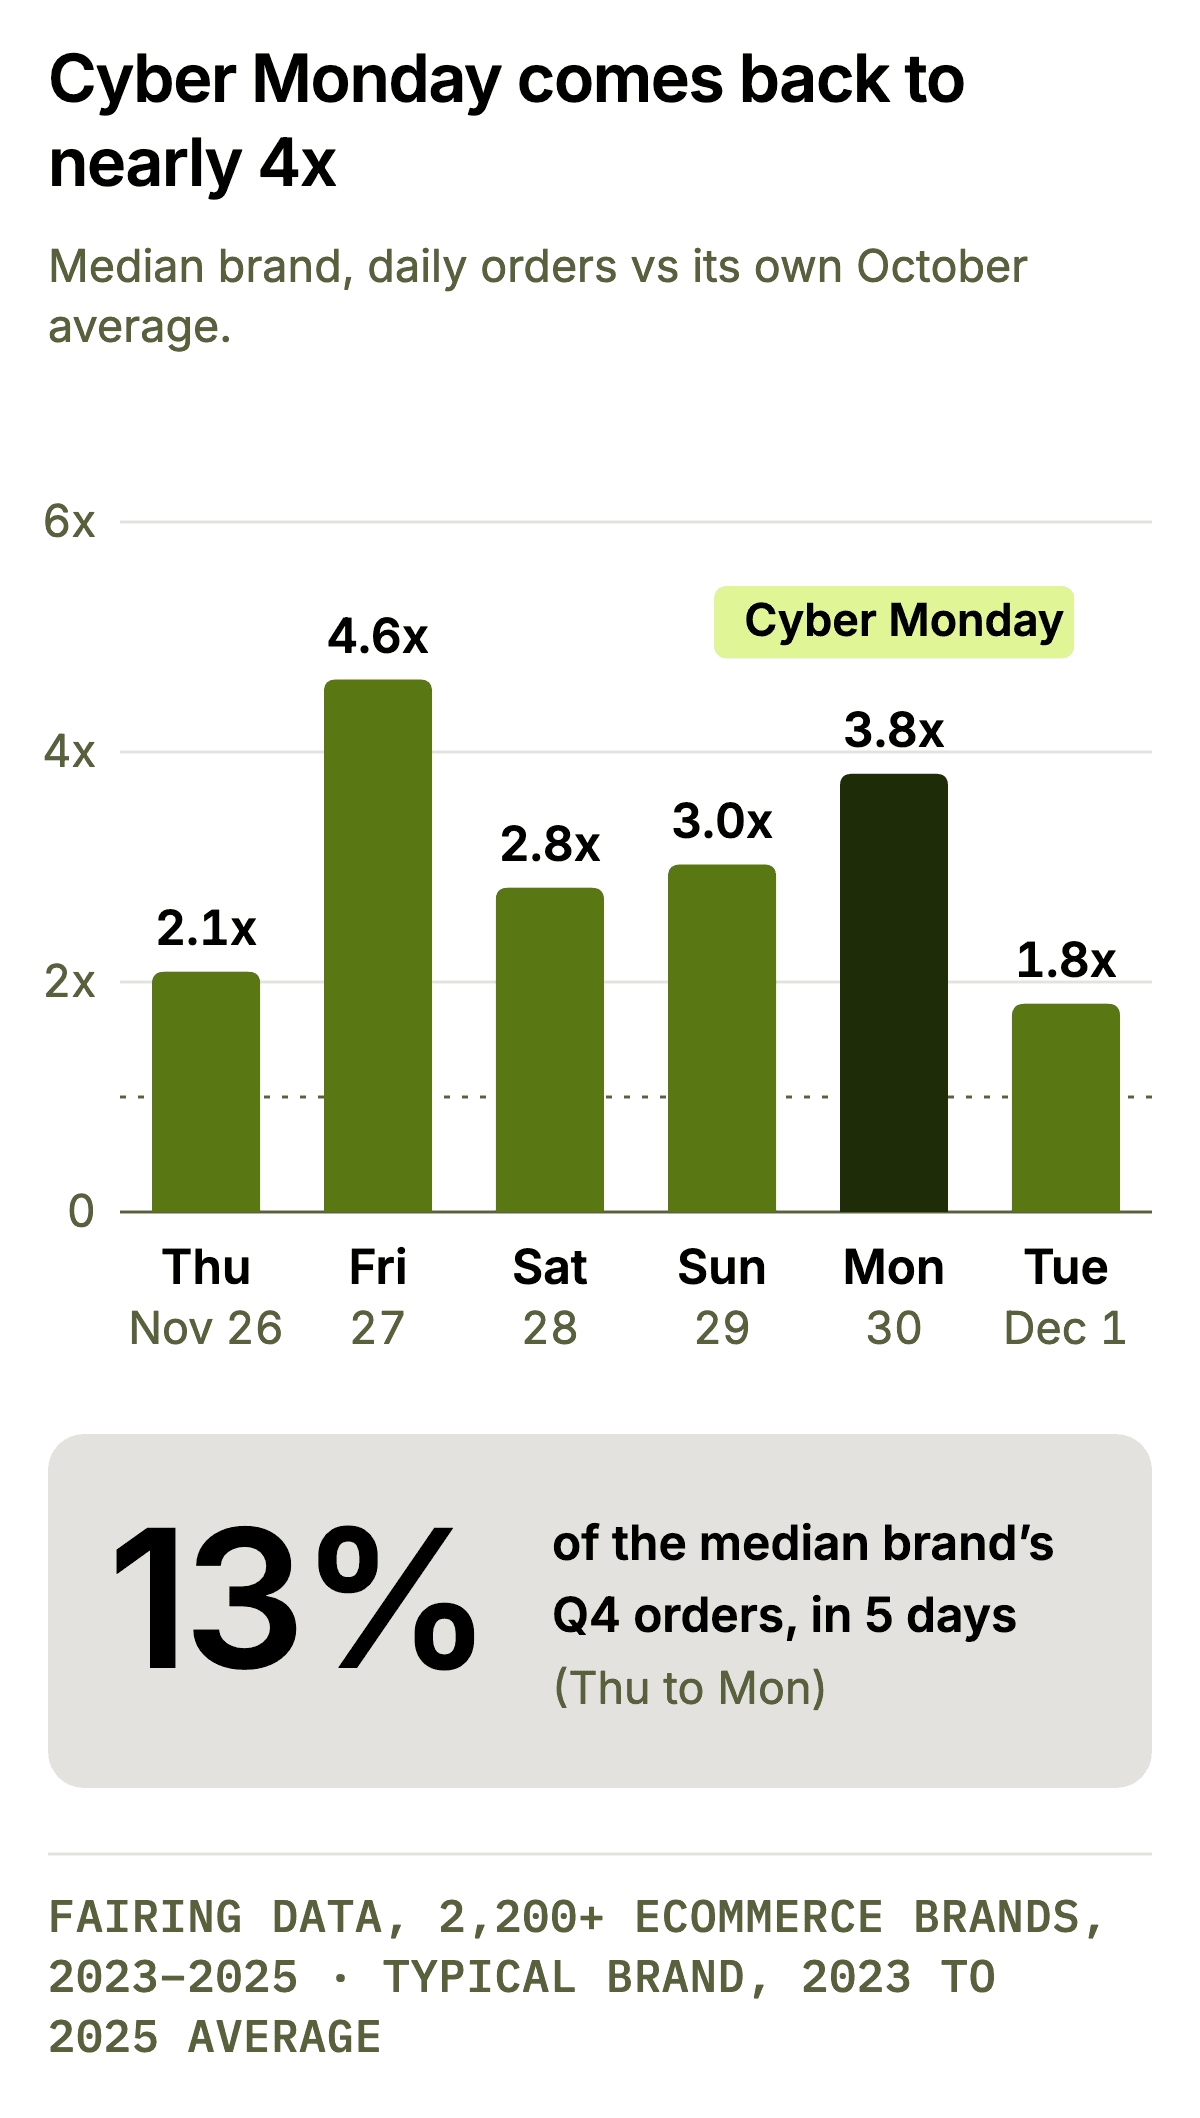
Thanksgiving is already about 2x October, Cyber Monday is nearly 4x, and the weekend between the peaks stays high.
Thanksgiving Day is already a 2x day
The median brand does about twice its October volume on Thanksgiving, about level with the Wednesday before. The middle half of brands runs 1.2x to 3.6x on the day, and about one brand in ten drops below 0.7x and goes quiet for the holiday. Order data can’t tell us whether that comes from early Black Friday offers or people shopping on their day off, so I won’t guess.
Cyber Monday is the second-biggest day
Saturday and Sunday after Black Friday each run about 3x October. Cyber Monday rebounds to nearly 4x, the median brand’s second-biggest day of the year, and Tuesday drops to about 1.8x.
Cyber Monday averages 84% to 86% of Black Friday. Black Friday is the bigger day for about 70% of brands, and Cyber Monday won for 33%, 29% and 30% of brands across the three years. The split has held every year.

Cyber Monday is an evening event
For the typical brand, 38% to 39% of Cyber Monday orders come in between 6 p.m. and midnight local time, against about 29% to 30% on a normal October Monday. 83% to 85% of brands see the shift, in both 2024 and 2025, and mornings get thinner to match.
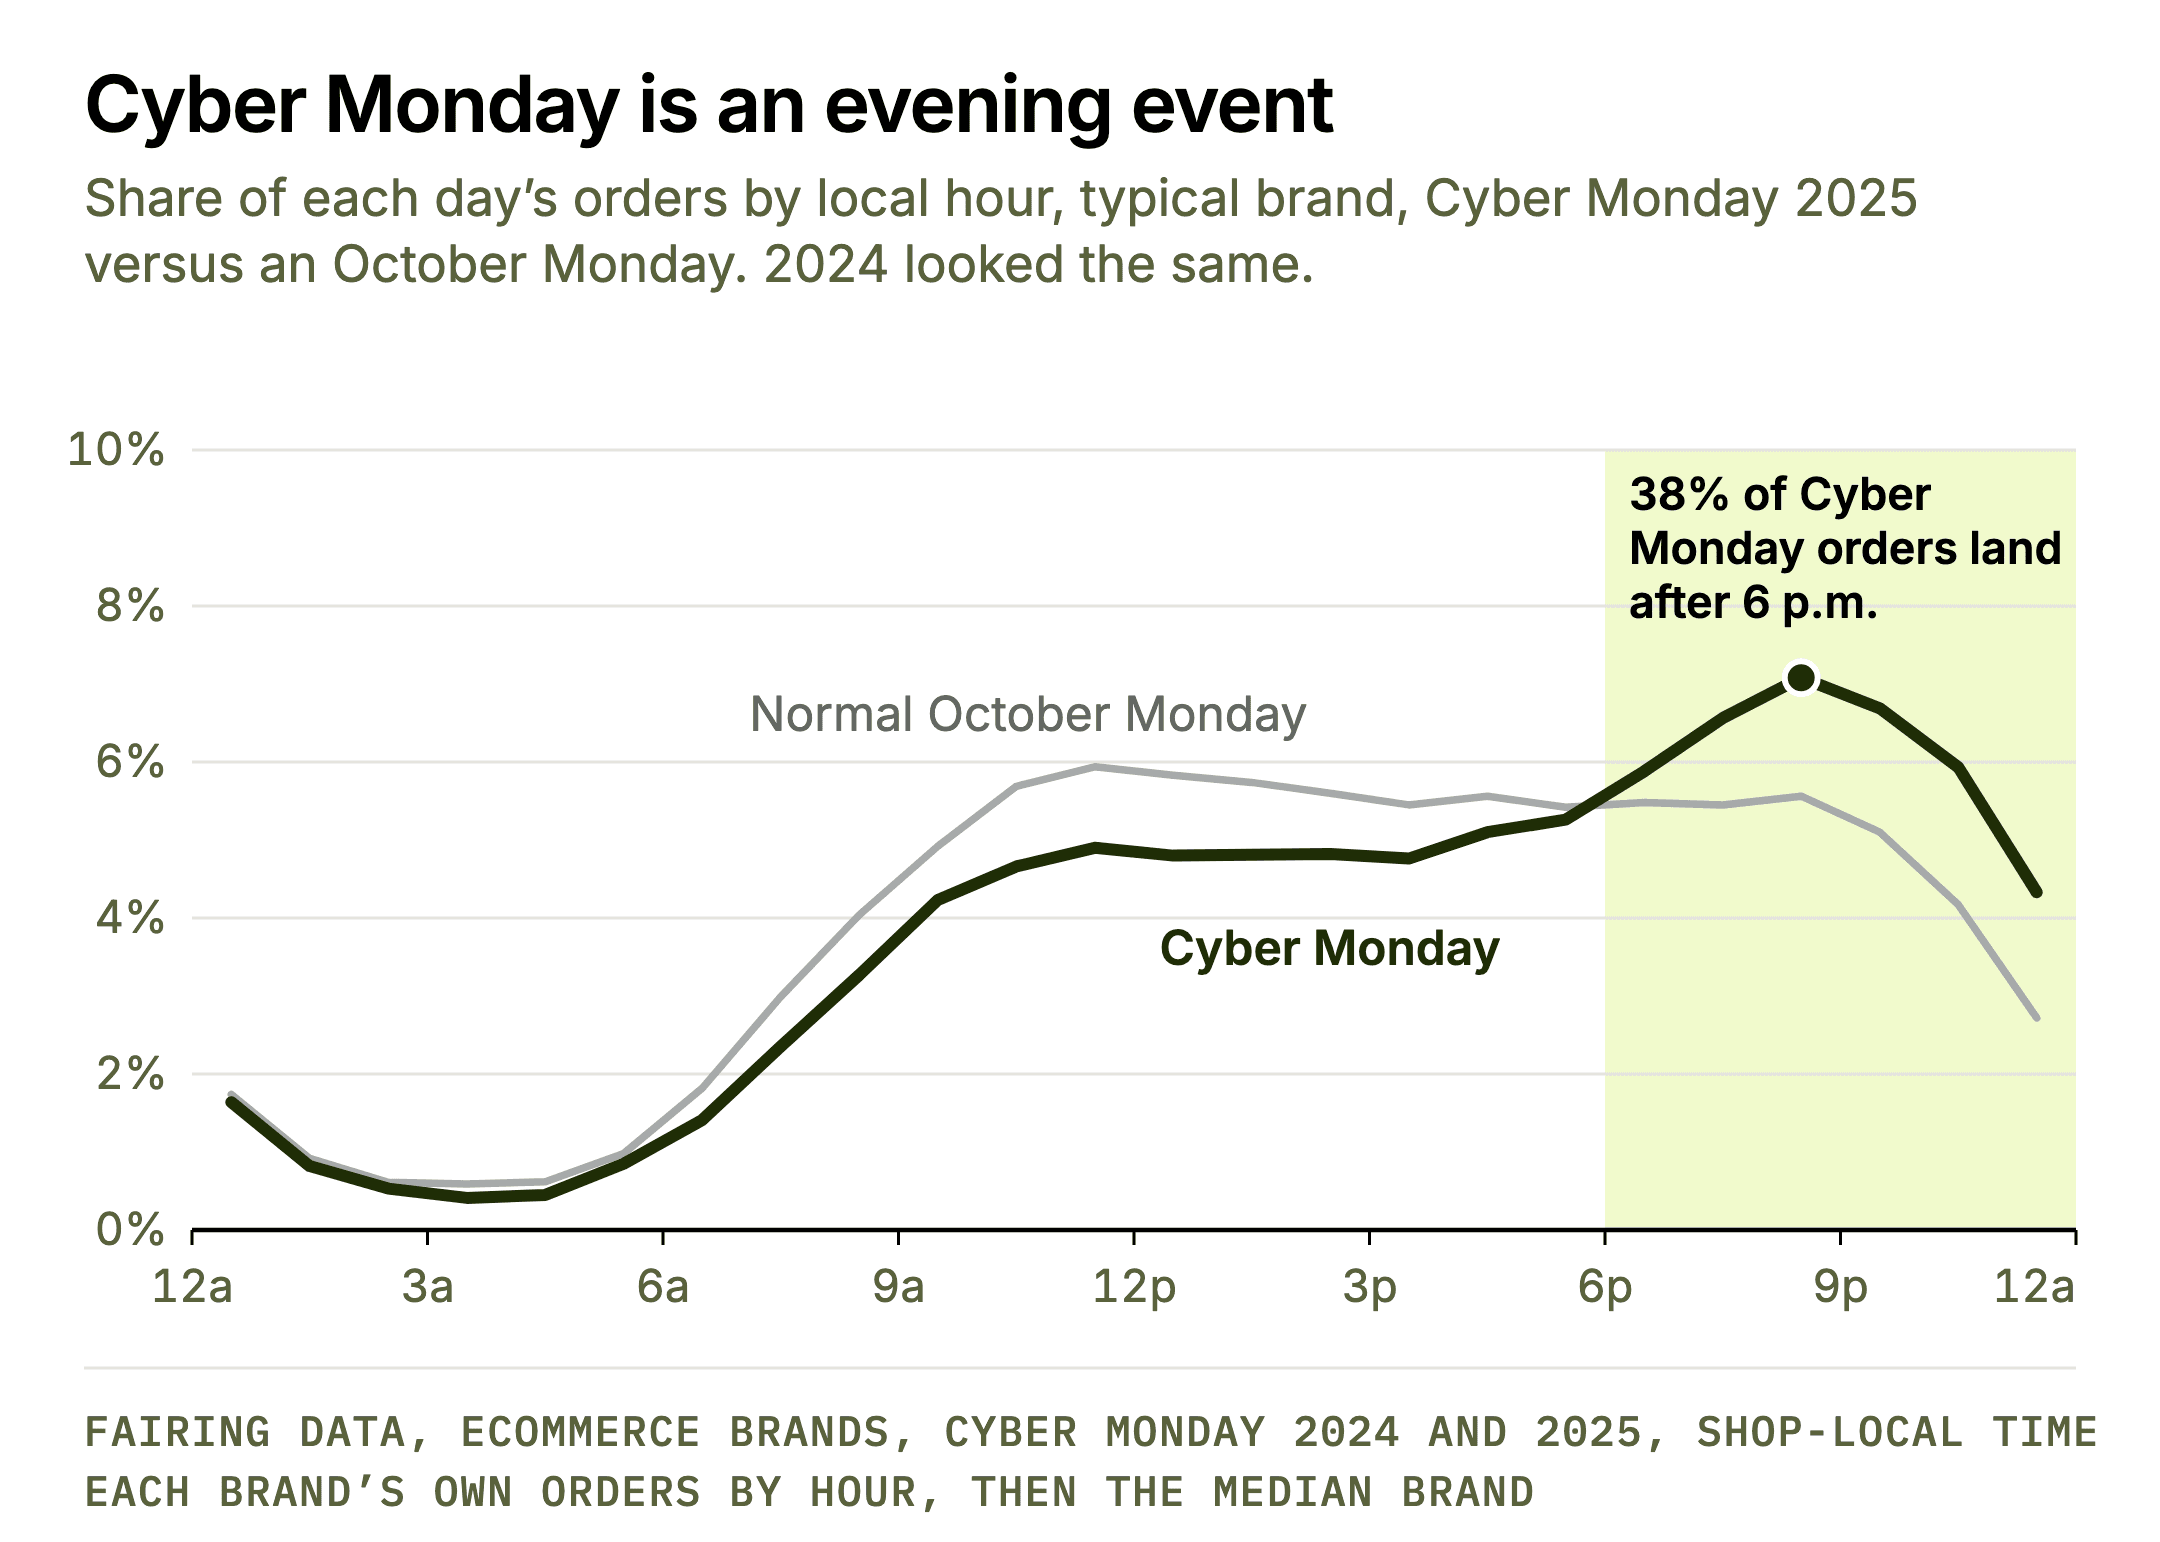
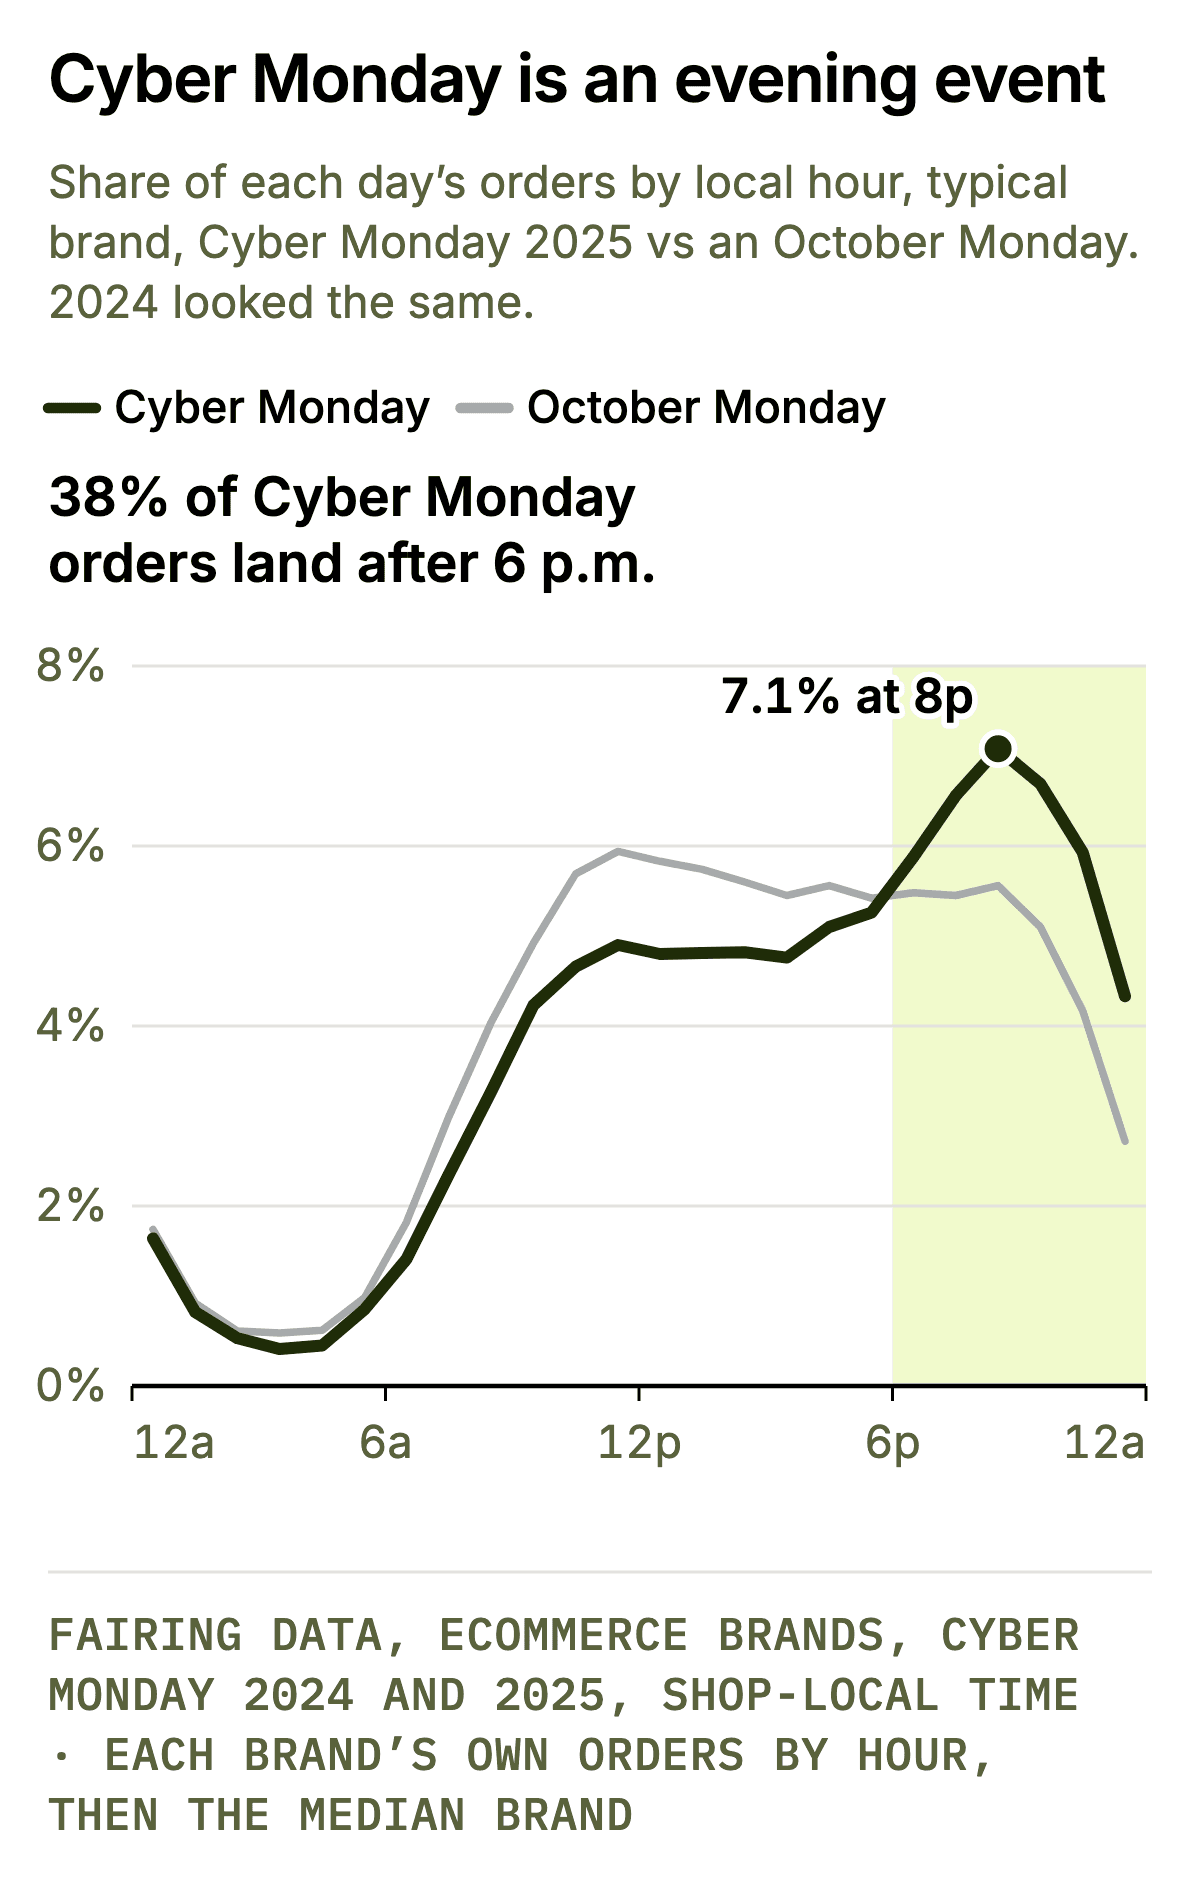
Black Friday leans to the evening far less, about 5 points over an October Friday. There’s no midnight rush either: the share of orders placed between midnight and 2 a.m. is lower than on a normal October day.
The Cyber 5 is a small slice of the calendar
Thanksgiving through Cyber Monday carries about 13% of the median brand’s Q4 orders, and it does that in about 5% of the quarter’s days. The middle half of brands ranges from 9% to 18%.
How to plan for BFCM 2026
Why it matters: If your on-call schedule or offer launch assumes the event starts at midnight on Friday, you’re already running at 2x with nobody watching.
Treat Thu Nov 26 as day one of the peak. Turn alerts and on-call on from Thursday morning, and test any Black Friday offer that goes live early at checkout before Thursday.
Keep weekend coverage close to peak on Sat Nov 28 and Sun Nov 29. A checkout or shipping bug you find Saturday morning still hits three more days at 3x to 4x.
Plan Cyber Monday (Mon Nov 30) as its own event, with its own send and creative. For about 3 brands in 10 it’s the bigger day.
Keep an evening send and support coverage in the plan. About 4 in 10 Cyber Monday orders land after 6 p.m.
Expect Tue Dec 1 at about 1.8x, and keep peak staff on through Monday night.
8. The hangover tracks who your customers are, and January stays above October
Cyber Monday runs nearly 4x and the Wednesday after about 1.4x. Live, that drop looks alarming, but the median brand bottoms out at about 1.25x and climbs back.
The post-BFCM dip is shallow
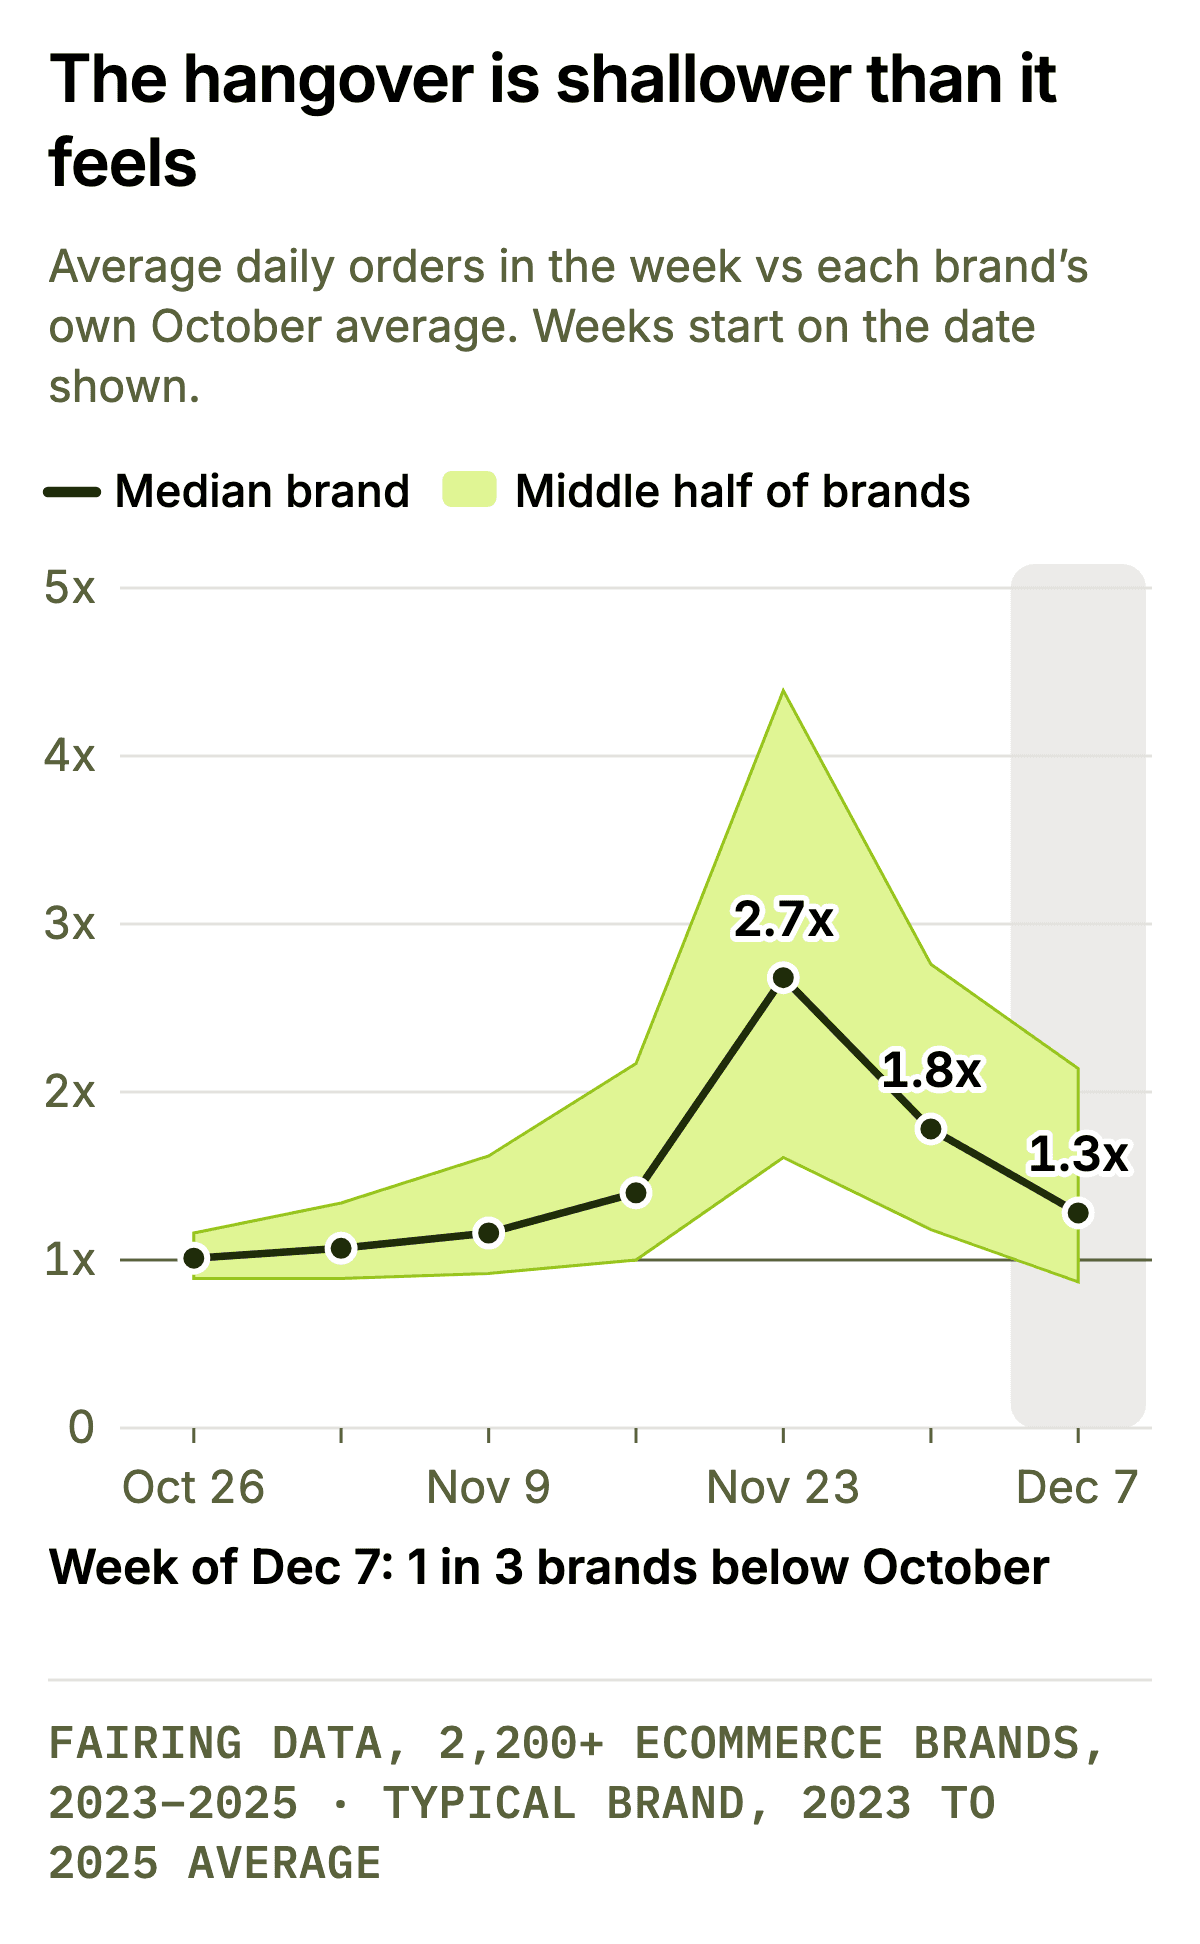
The median brand bottoms out at about 1.25x around Dec 4 and climbs from there. Weekly averages run 1.78x for Cyber week (Nov 30 to Dec 6) and 1.28x for Dec 7 to 13.
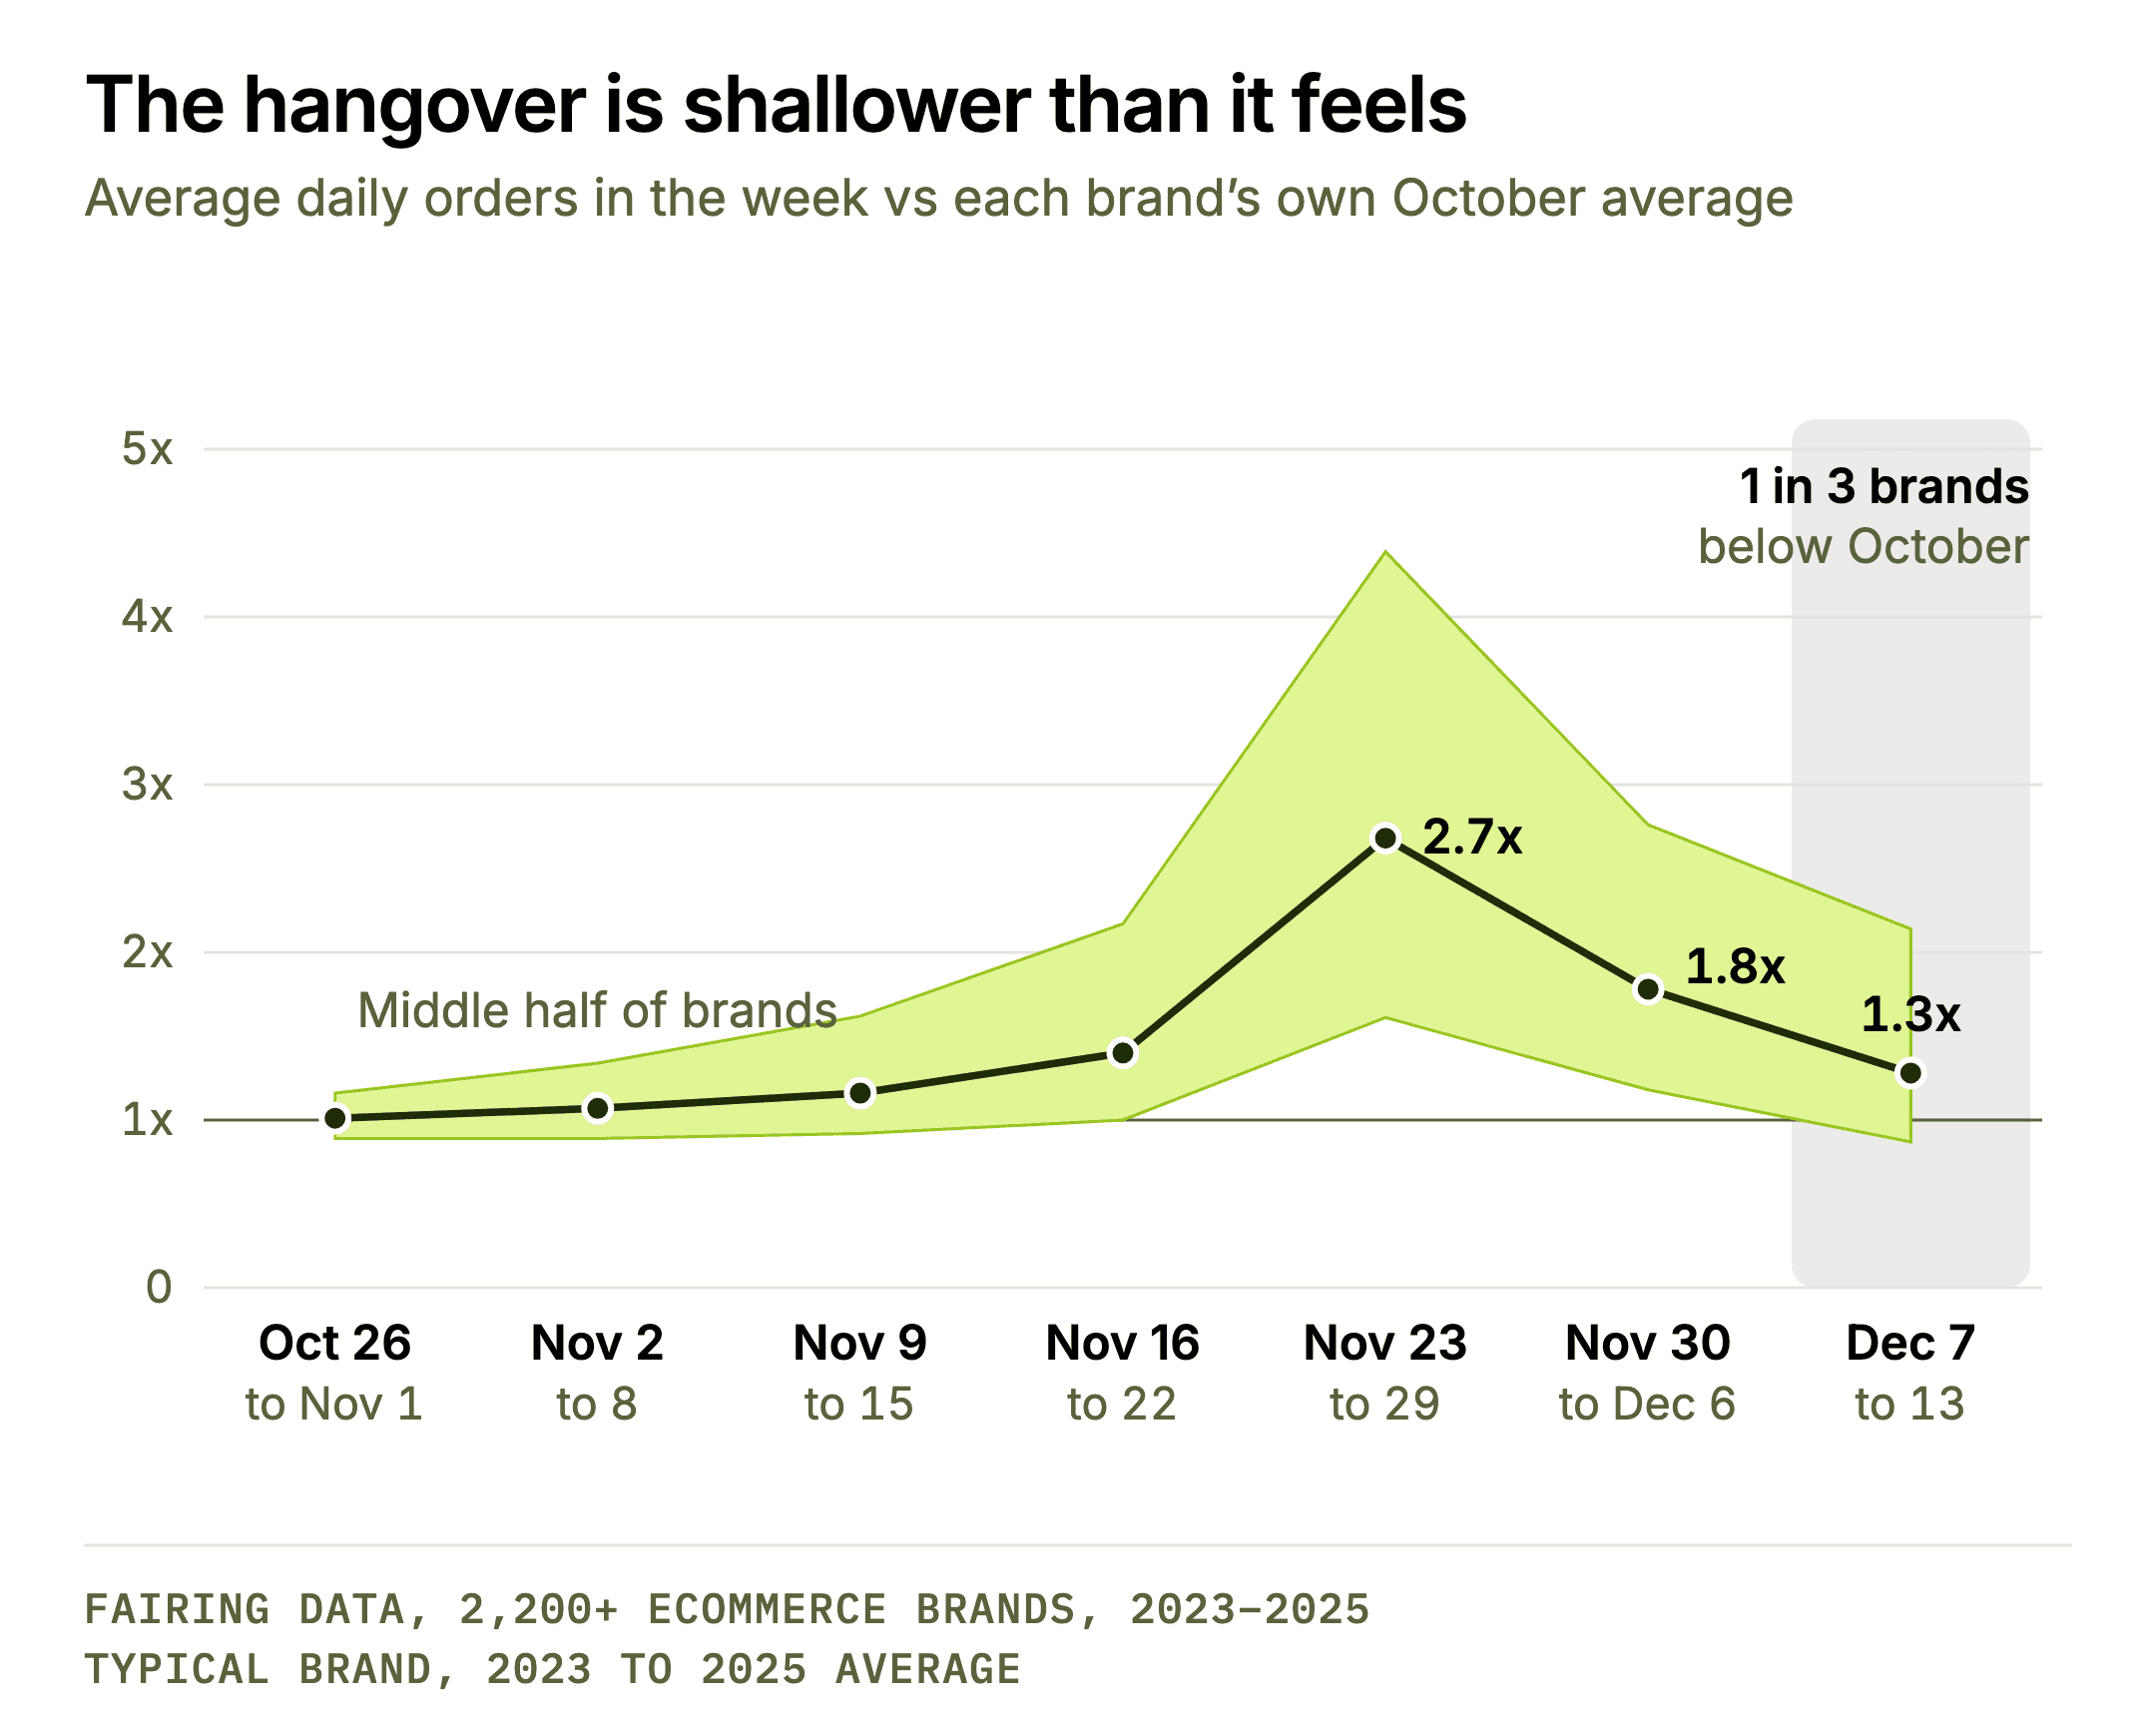
A big spike doesn’t dig a deeper hole
The tail is real: about one brand in three falls below its October level in the Dec 7 to 13 week. But brands with big BFCMs tended to hold up better afterwards (rank correlation 0.53 to 0.60), and within the same brand, a bigger BFCM came with a bigger week after (0.66). Part of the rank correlation is mechanical, because both measures use the same October as their base.
January orders stay above October
The typical brand’s January runs about 5% above its own October, in every season we have (January 2024, 2025 and 2026), and fewer than half of brands fall below October. A bigger BFCM didn’t mean a weaker January. Comparing each brand with its own prior year, with its October change held fixed:
A 10% bigger BFCM went with a 3% to 4% bigger January.
It also went with a 3% to 4% stronger February and March.
There’s no sign BFCM pulls first-quarter sales forward.
January is a normal level, not a strong one
October is a soft month to begin with, so read January as normal, not strong. This is also a correlation, and it likely reflects brands having a good year.
Customer mix shapes the afterglow
Split brands by their normal share of new customers and the Black Friday spike is the same size in every group: 4.8x, 4.9x and 4.8x. The week after differs. Mostly repeat-customer brands fall back to 1.16x October, while mostly new-customer brands hold 1.54x. Through mid-December, new-customer-heavy brands stay higher (1.36x against 1.10x).
Repeat-heavy brands look like they use up their loyal demand at BFCM. New-customer-heavy brands keep finding buyers. Consumables lean repeat-heavy, so read this alongside section 2.
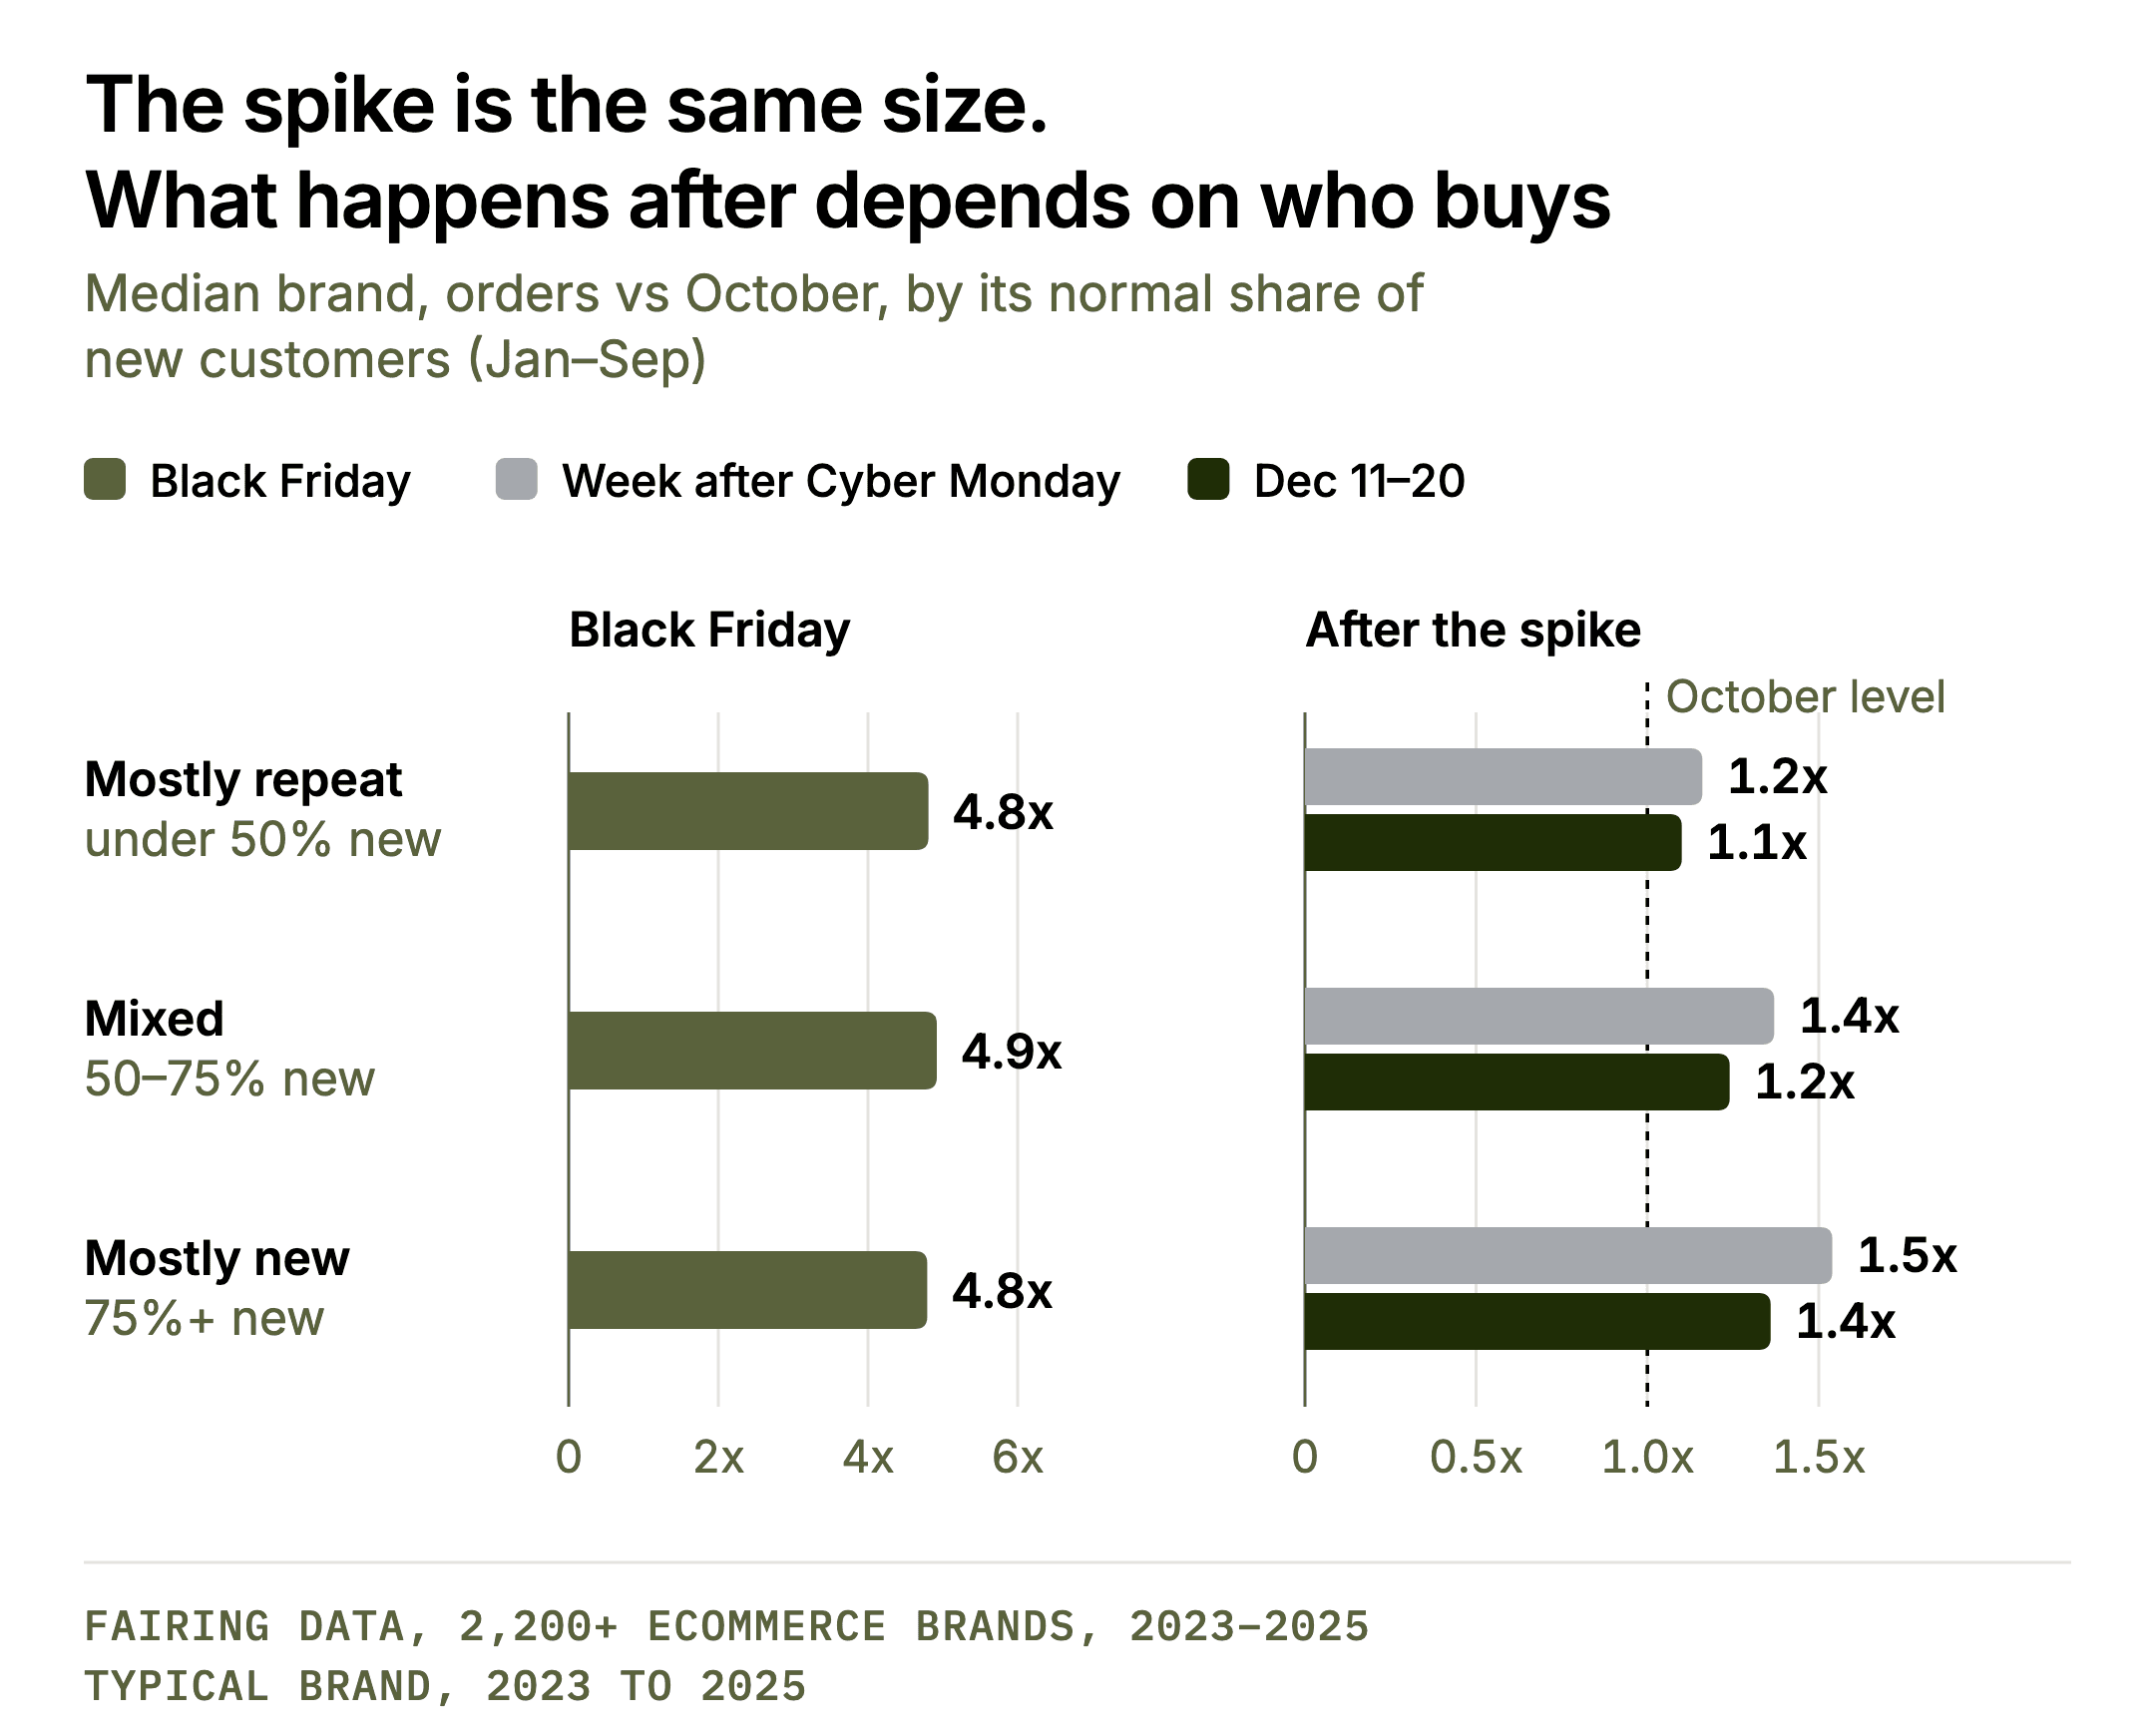
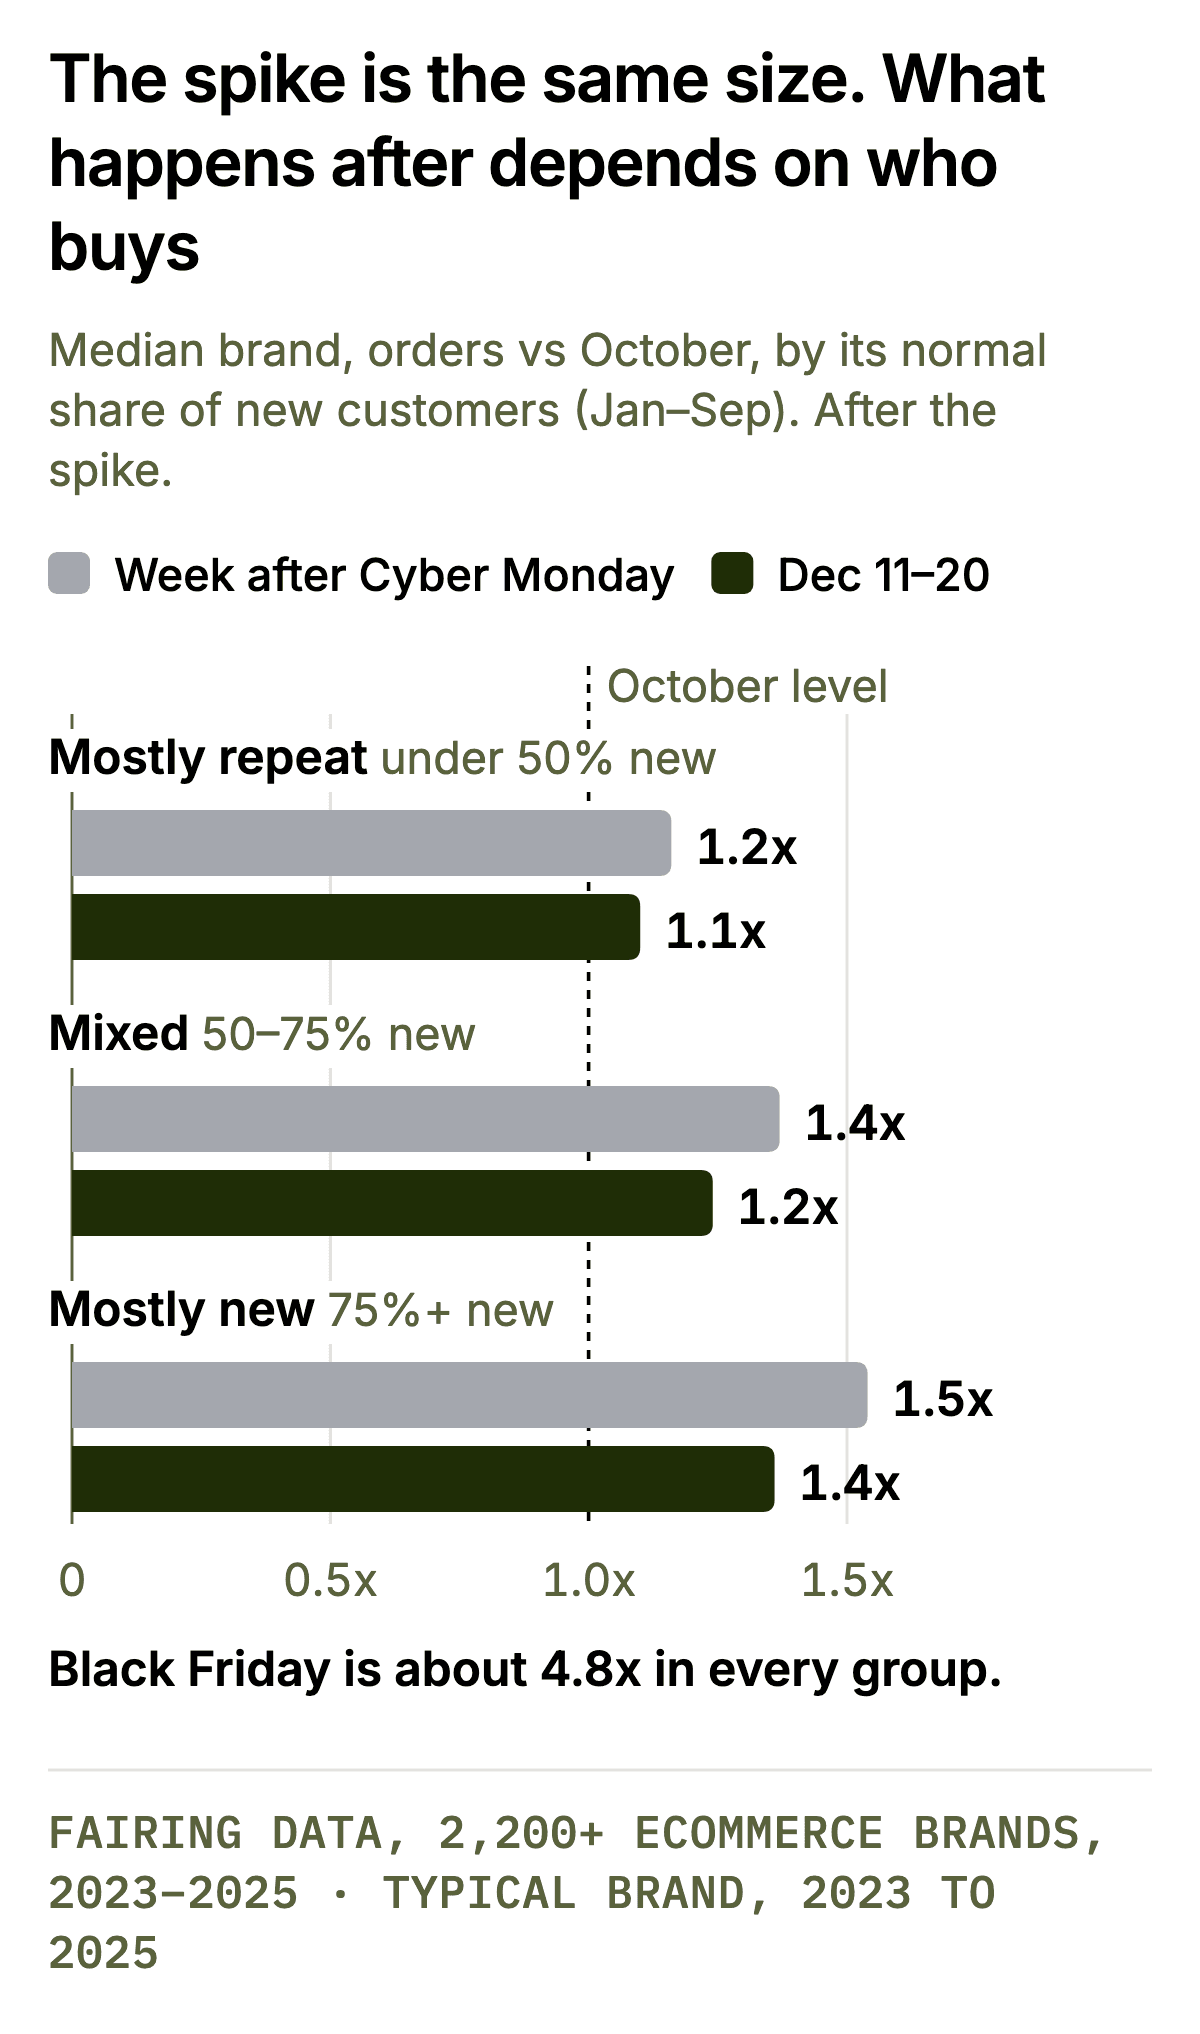
How to plan for BFCM 2026
Why it matters: Cutting prospecting on Tuesday pulls you back while acquisition-led brands still run half again above October, and a big BFCM isn’t a reason to cut the Q1 forecast.
Keep acquisition running on Tue Dec 1. Judge the hangover on the Dec 7 to 13 week instead: median 1.28x, middle half 0.87x to 2.14x.
Check that week on Mon Dec 14. Below 1.0x puts you in the bottom third. That’s the day to act with gifting creative and shipping-deadline messaging. Dec 20 is too late.
Repeat-heavy brands (under half new customers): expect a fast drop after Cyber Monday. Plan December offers aimed at people who didn’t buy at BFCM, such as gifting and new products.
New-customer-heavy brands: keep prospecting spend running after Cyber Monday. Demand holds at about 1.5x October.
Don’t cut your first-quarter forecast because BFCM went big. In this data, a bigger BFCM came with a stronger January to March, not a weaker one.
9. December’s second peak, then the Christmas Eve cliff
December has a real second peak in mid-month, then falls off a cliff on Christmas Eve.
Mid-December is the last real peak
Demand picks up again and peaks at about 1.4x in mid-December, around Sun Dec 13 in 2026. Single-year peaks fell between Dec 12 and 14. From Dec 21 the median brand runs below October and bottoms out at about 0.65x on Christmas Eve. The Christmas dip follows the calendar, so it doesn’t move with Black Friday.
Dec 26 is a one-day bump
Dec 26 bumps for a day, but Dec 26 to 31 as a whole runs only 1.04x to 1.09x October. That week carries about 2% of the season’s extra orders.

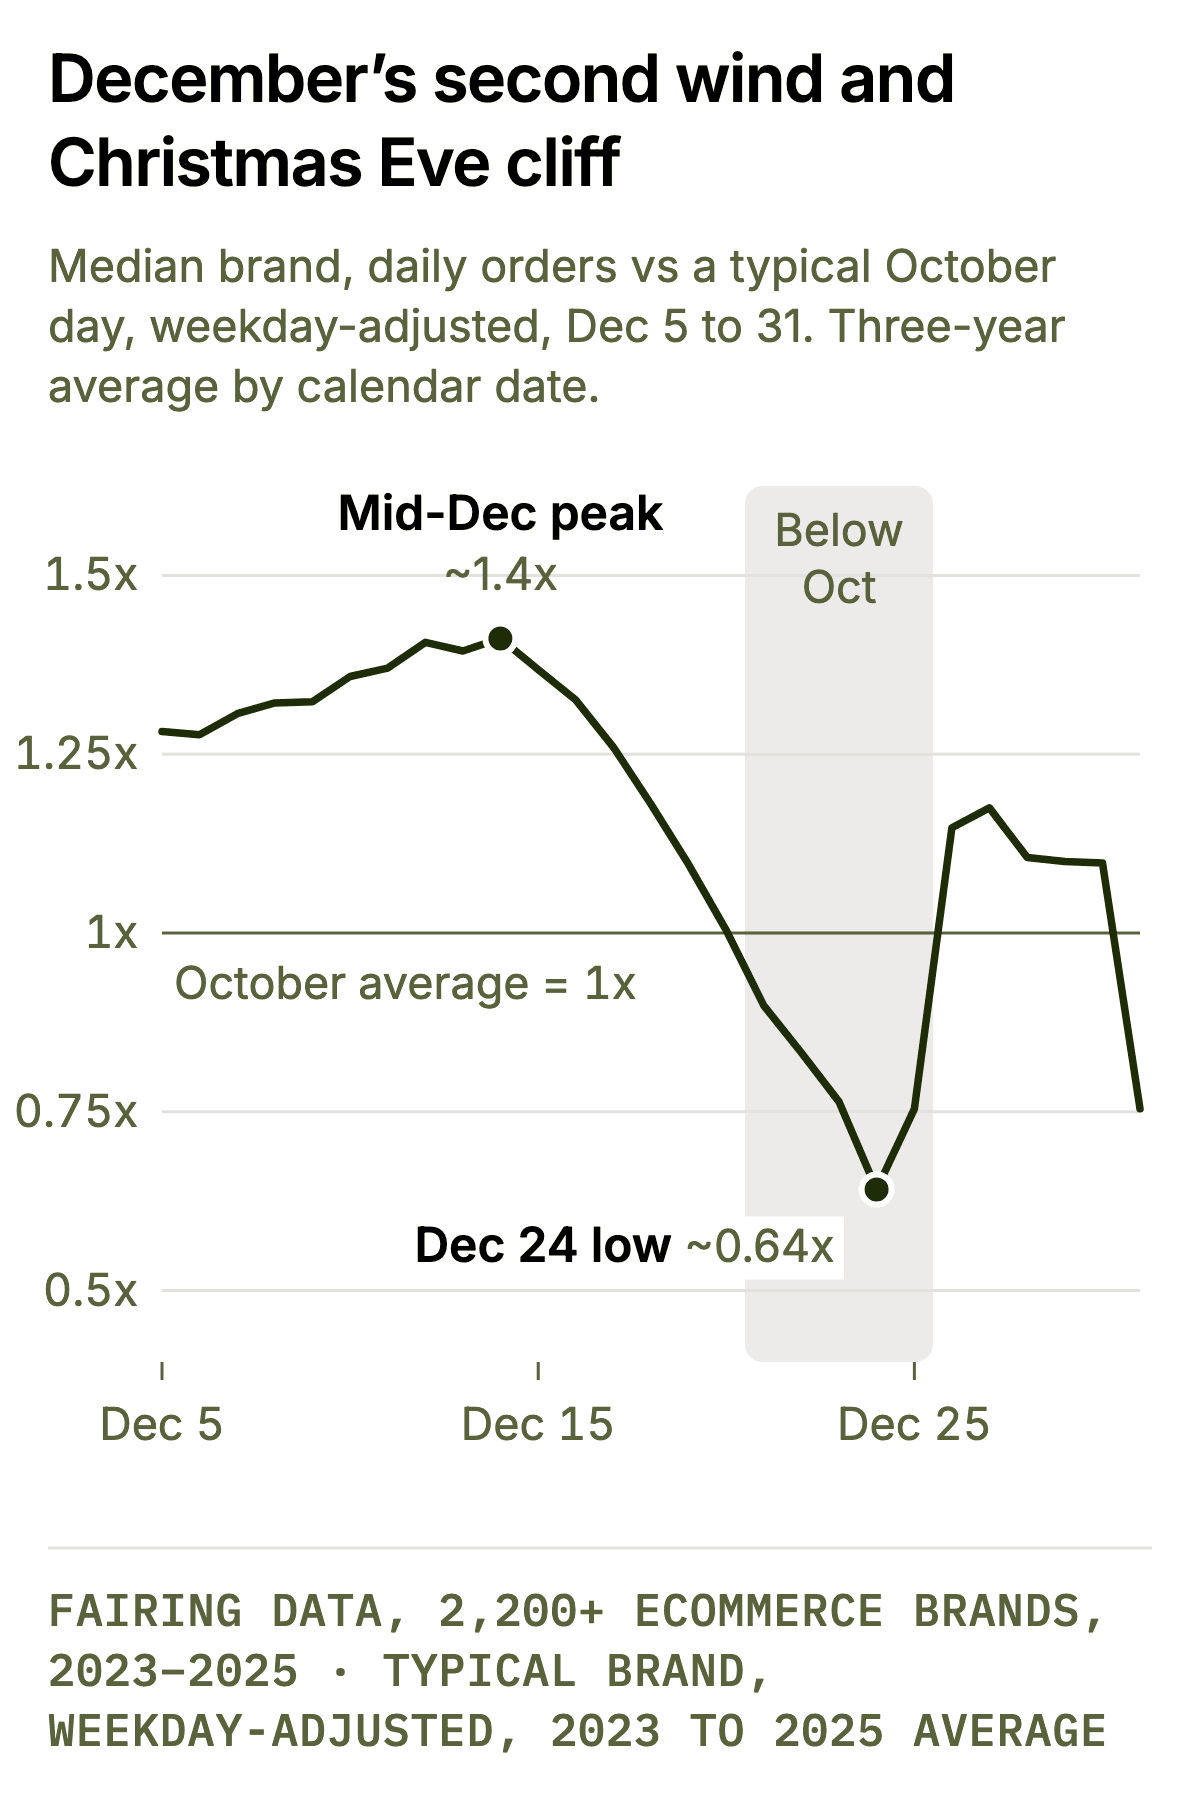
December’s share swings with calendar length
The year-to-year swing in December’s share of extra orders is mostly calendar length. Per day it held at about 1% each year (see the table in section 4). Black Friday 2026, on Nov 27, leaves an 18-day stretch to Christmas, close to 2025.
How to plan for BFCM 2026
Why it matters: Mid-December is the season’s last real peak, and the week after Christmas won’t make up for a soft December.
Plan a second push for Dec 7 to 20, with the peak expected around Sun Dec 13. Get your shipping cutoff date into creative by Mon Dec 14.
Expect Dec 21 to 25 to run below October. Shift spend to gift cards or digital products, or pause.
Don’t plan a post-Christmas sale expecting a second spike. The week after Christmas runs at about October level.
10. Holiday customers skew new, and come back less
December has the biggest share of new customers all year (see the table in section 2). BFCM brings in the most by count. Holiday buyers also come back less.
Count peaks at BFCM, share peaks in December
New-customer orders per day run about 3.3x October at BFCM for the typical brand, against about 1.4x on Dec 5 to 20. BFCM wins on count simply because it is the most orders.
New-customer share climbs after BFCM
At BFCM the median brand’s share of first-time buyers moves less than a point from October (−0.7, +0.2 and +0.8 points across the three years). It starts climbing the week after, about 3 points above October.
Dec 5 to 20 runs 3.5, 3.7 and 4.5 points above October. That held every year, including for the same brands tracked across the years, and 57% to 64% of brands saw their December share rise above their own October.

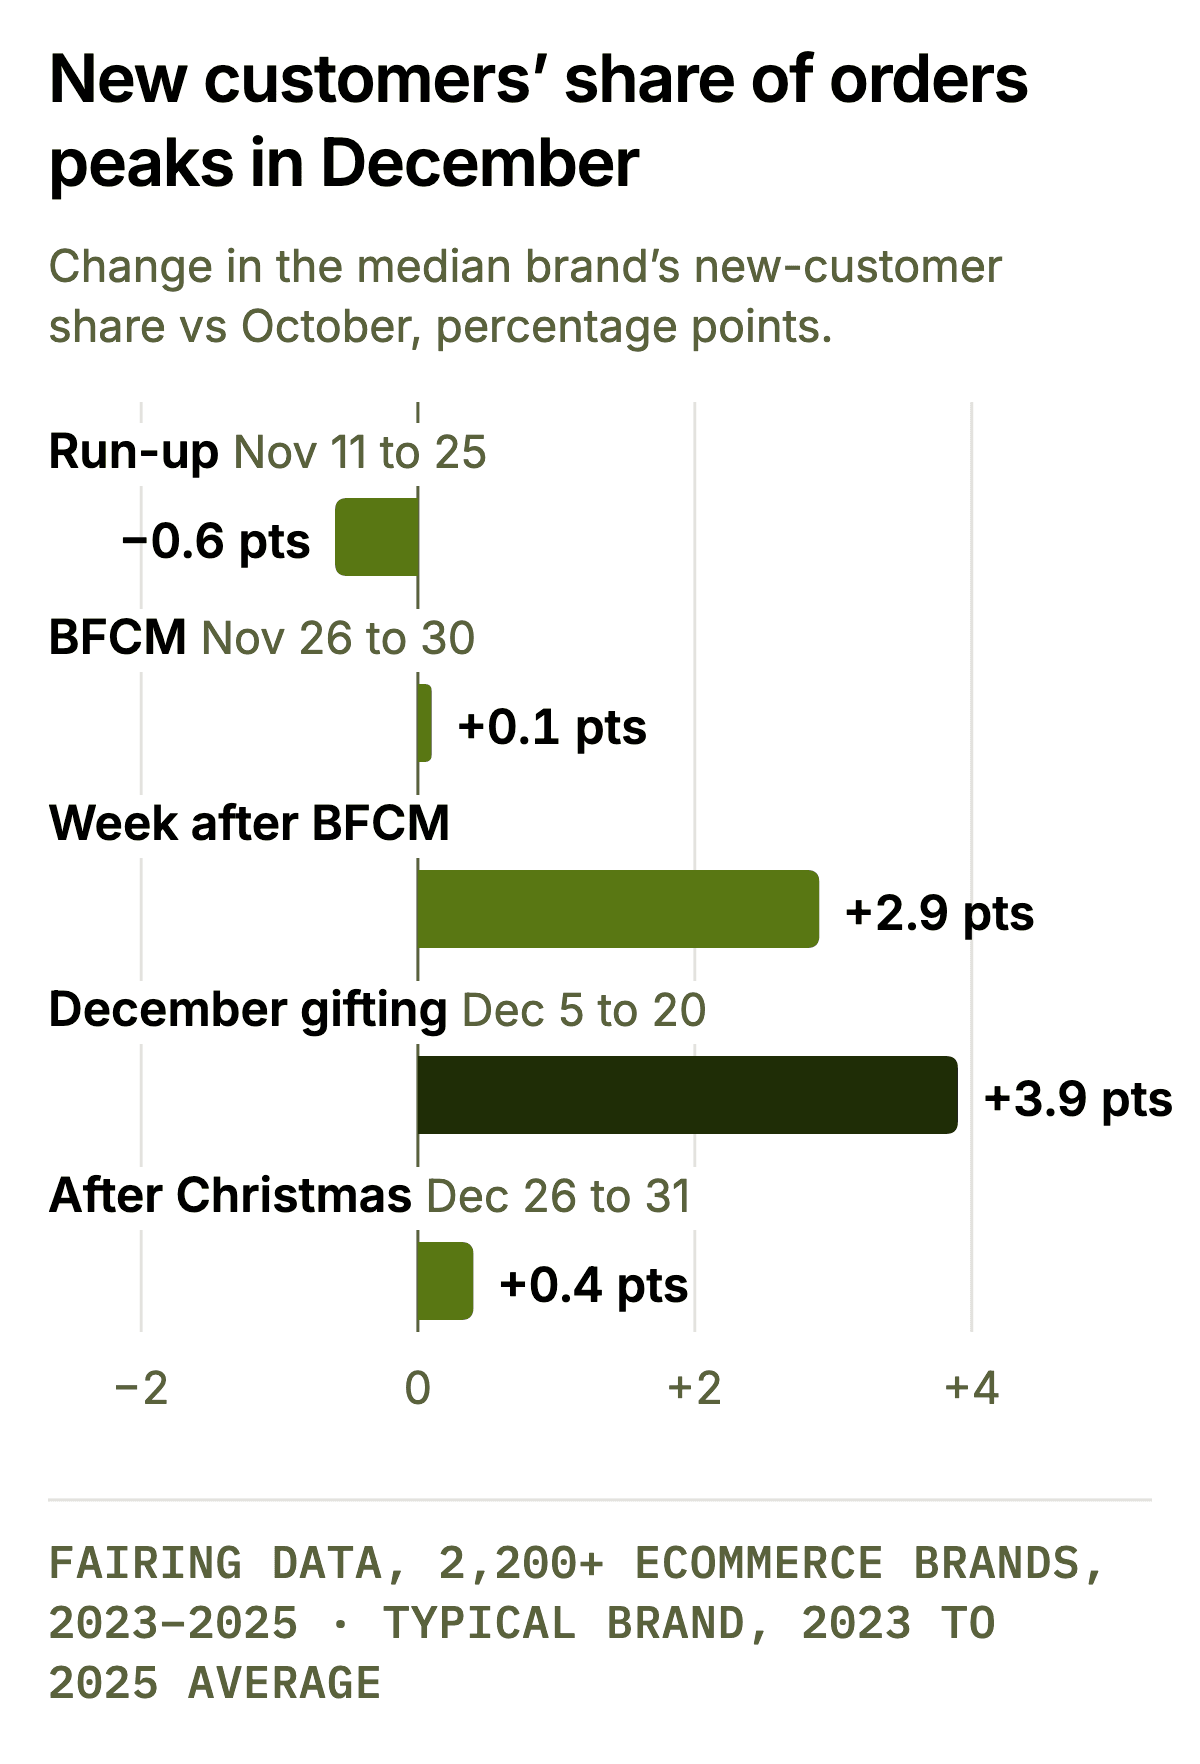
New customers per day follow the calendar
Dec 21 to 24 runs about 0.8x October. Dec 26 to 31 is back to about October level (1.07x to 1.09x), in both 2024 and 2025.
Holiday first-time buyers come back less
We followed first-time buyers from the 2024 season for 90 days. The share who ordered again, for the typical brand:
October’s first-time buyers: 10.0%.
BFCM’s: 6.8%.
Dec 5 to 20: 7.1%.
Within the same brand, BFCM buyers reordered at about 70% of October buyers’ rate, and 77% of brands saw a lower rate. A 30-day check mostly avoids the BFCM overlap and still shows the gap: 3.9% against 3.0%. It held in the 2023 season too: 9.5% against 6.5%.
Read the reorder numbers with care
Part of October’s edge is that its 90 days include BFCM itself.
We only see a reorder when our survey appeared on it.
Guest checkouts undercount repeats.
90 days isn’t lifetime value.
How to plan for BFCM 2026
Why it matters: BFCM brings in the most new customers and December skews most toward first-time buyers, but those buyers are about 30% less likely to come back, so the holiday cohort needs more work after the first order.
Keep prospecting on through BFCM.
Add new-customer creative and budget for Dec 5 to 20: gift guides, bundles, gift cards.
Build a second-order flow for BFCM and December first-time buyers before your first BFCM offer goes live.
Judge that flow against your October buyers’ reorder rate. Expect the holiday cohort to start about 30% lower.
11. The share of orders with a code halves at BFCM, and code-based attribution undercounts
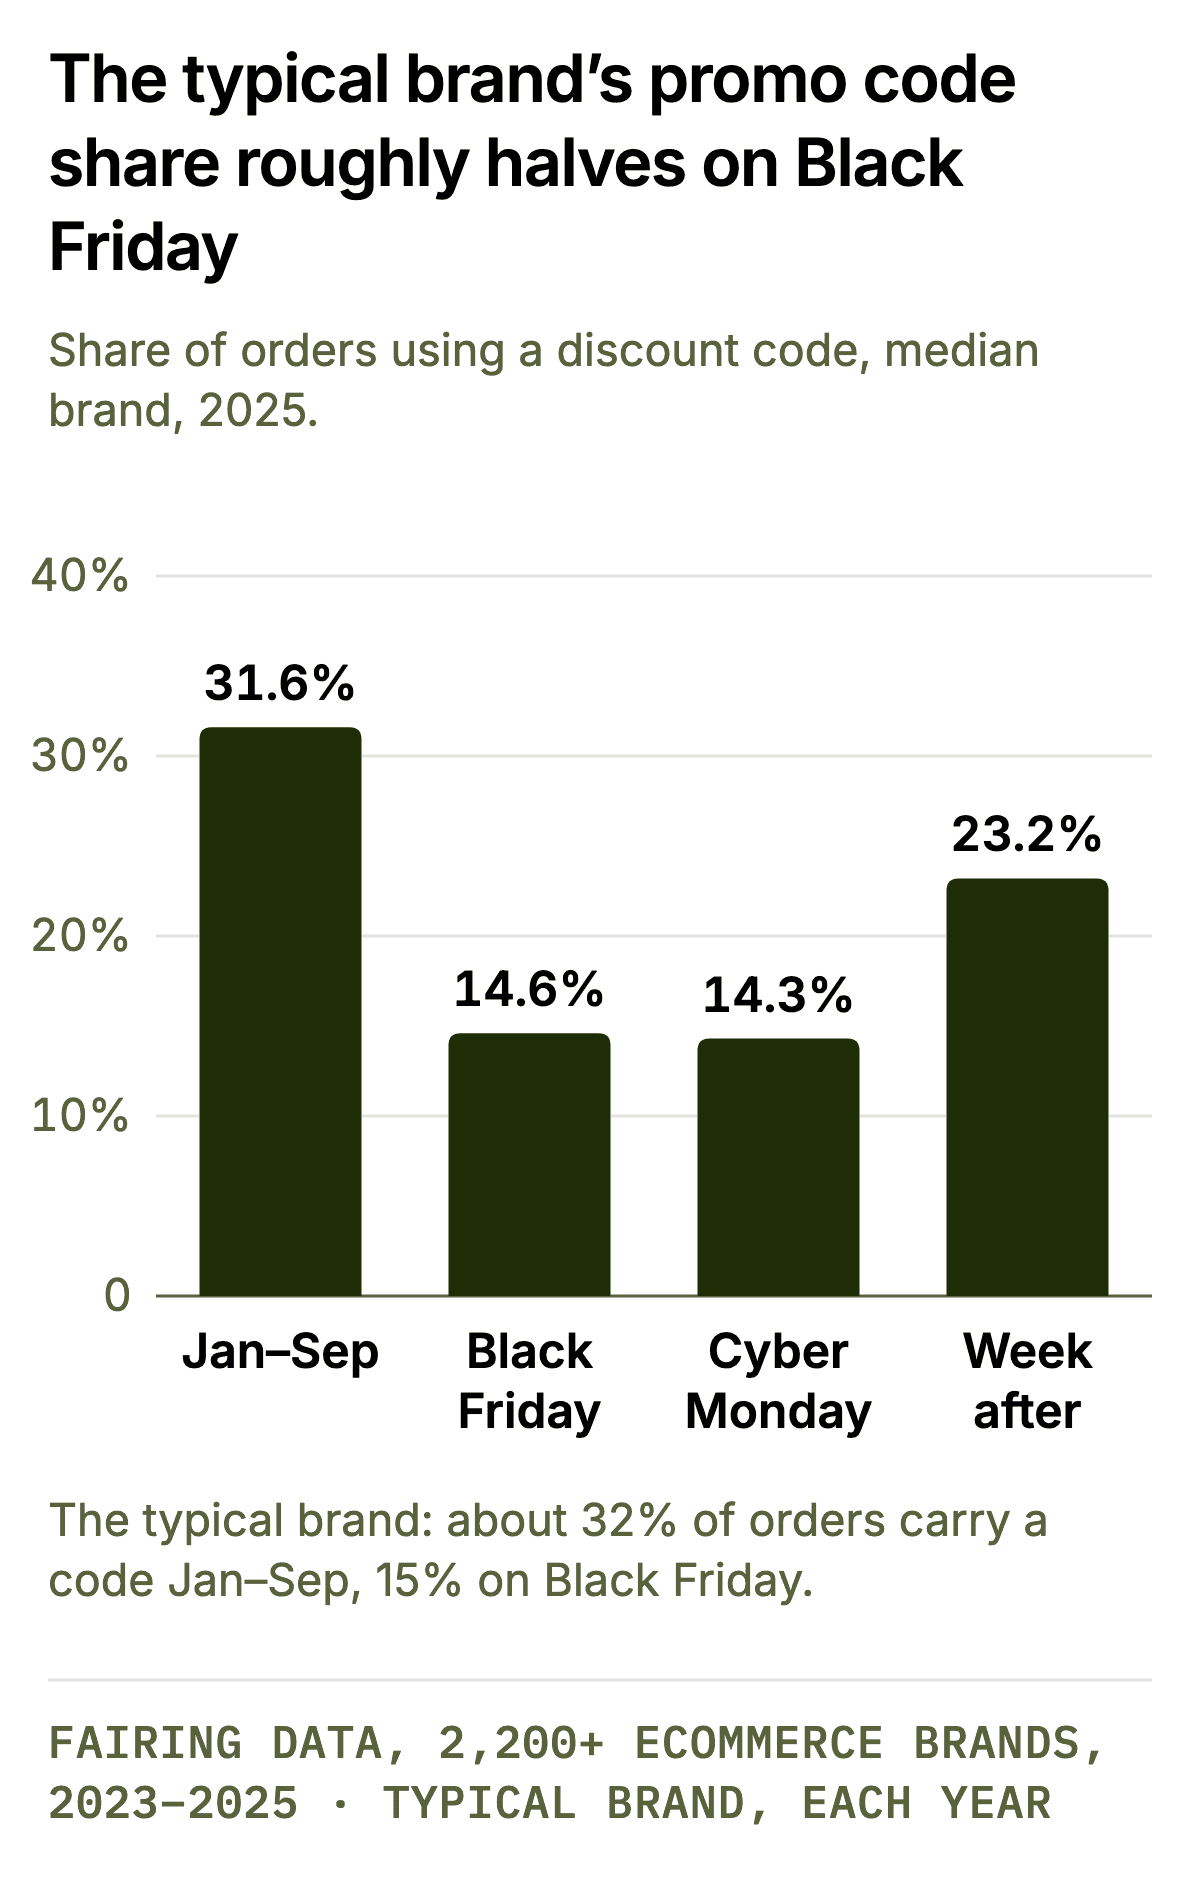
Codes grow far less than everything else at BFCM. Code-based credit breaks just when volume peaks.
Code share halves on Black Friday
For the typical brand, about a third of orders use a discount code from January to September. On Black Friday that roughly halves, to 18.8% of orders in 2023, 15.4% in 2024 and 14.6% in 2025.
For the same brands tracked across the years, that is one step down after 2023 and no further drop since. A week later, code share is back to about a quarter of orders. The count of code orders still rises, to 2.3 to 2.65 times a normal October’s.

First-time buyers drop codes the most
In October, first-time buyers use a code more often than returning customers: on about 35% to 37% of their orders, against 28% to 30%. On Black Friday, first-time buyers’ code use falls about 22 points and returning customers’ about 14 to 16, so both groups land at about 13% to 15% (2024 and 2025). First-time buyers are the customers creators, affiliates and podcasts are paid to bring in, and they’re the ones who stop typing codes at BFCM.
Codes don’t vanish, and it depends on your baseline
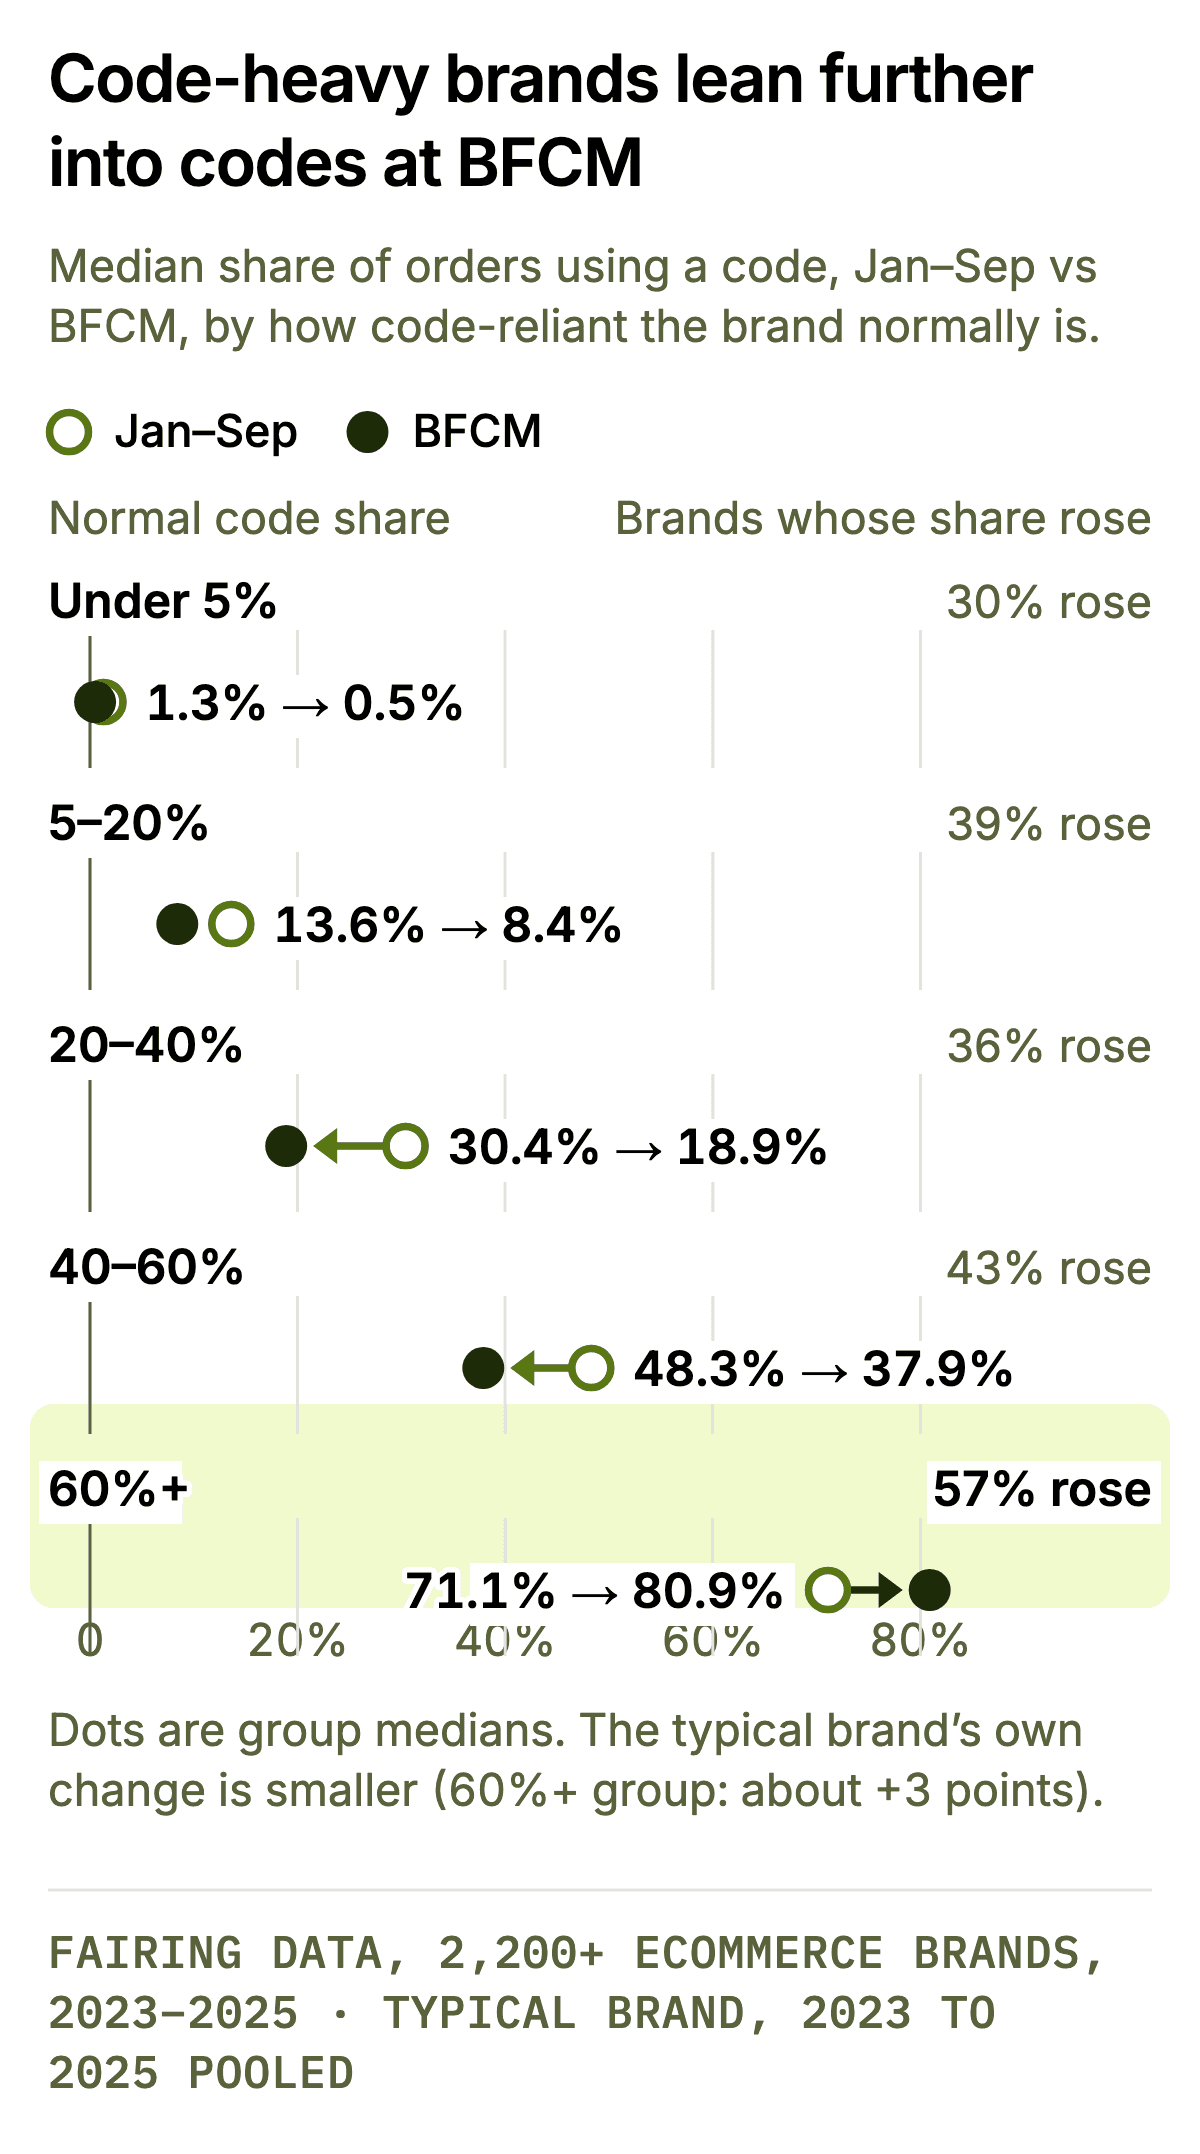
Across all orders pooled, about 3 in 10 BFCM orders still carry a code. The typical brand’s code share held flat at about a third from January to September in each of the three years. Overall, 40% of brands increase their code share at BFCM.
How it moves depends on where you start:
Brands with 20% to 60% code share drop about 10 points at BFCM. That fits a switch to automatic sitewide discounts.
Brands at 60% or more of orders on codes go the other way. The typical one rises about 3 points, and 57% of them rise. They are likely affiliate-, influencer- or subscription-led.
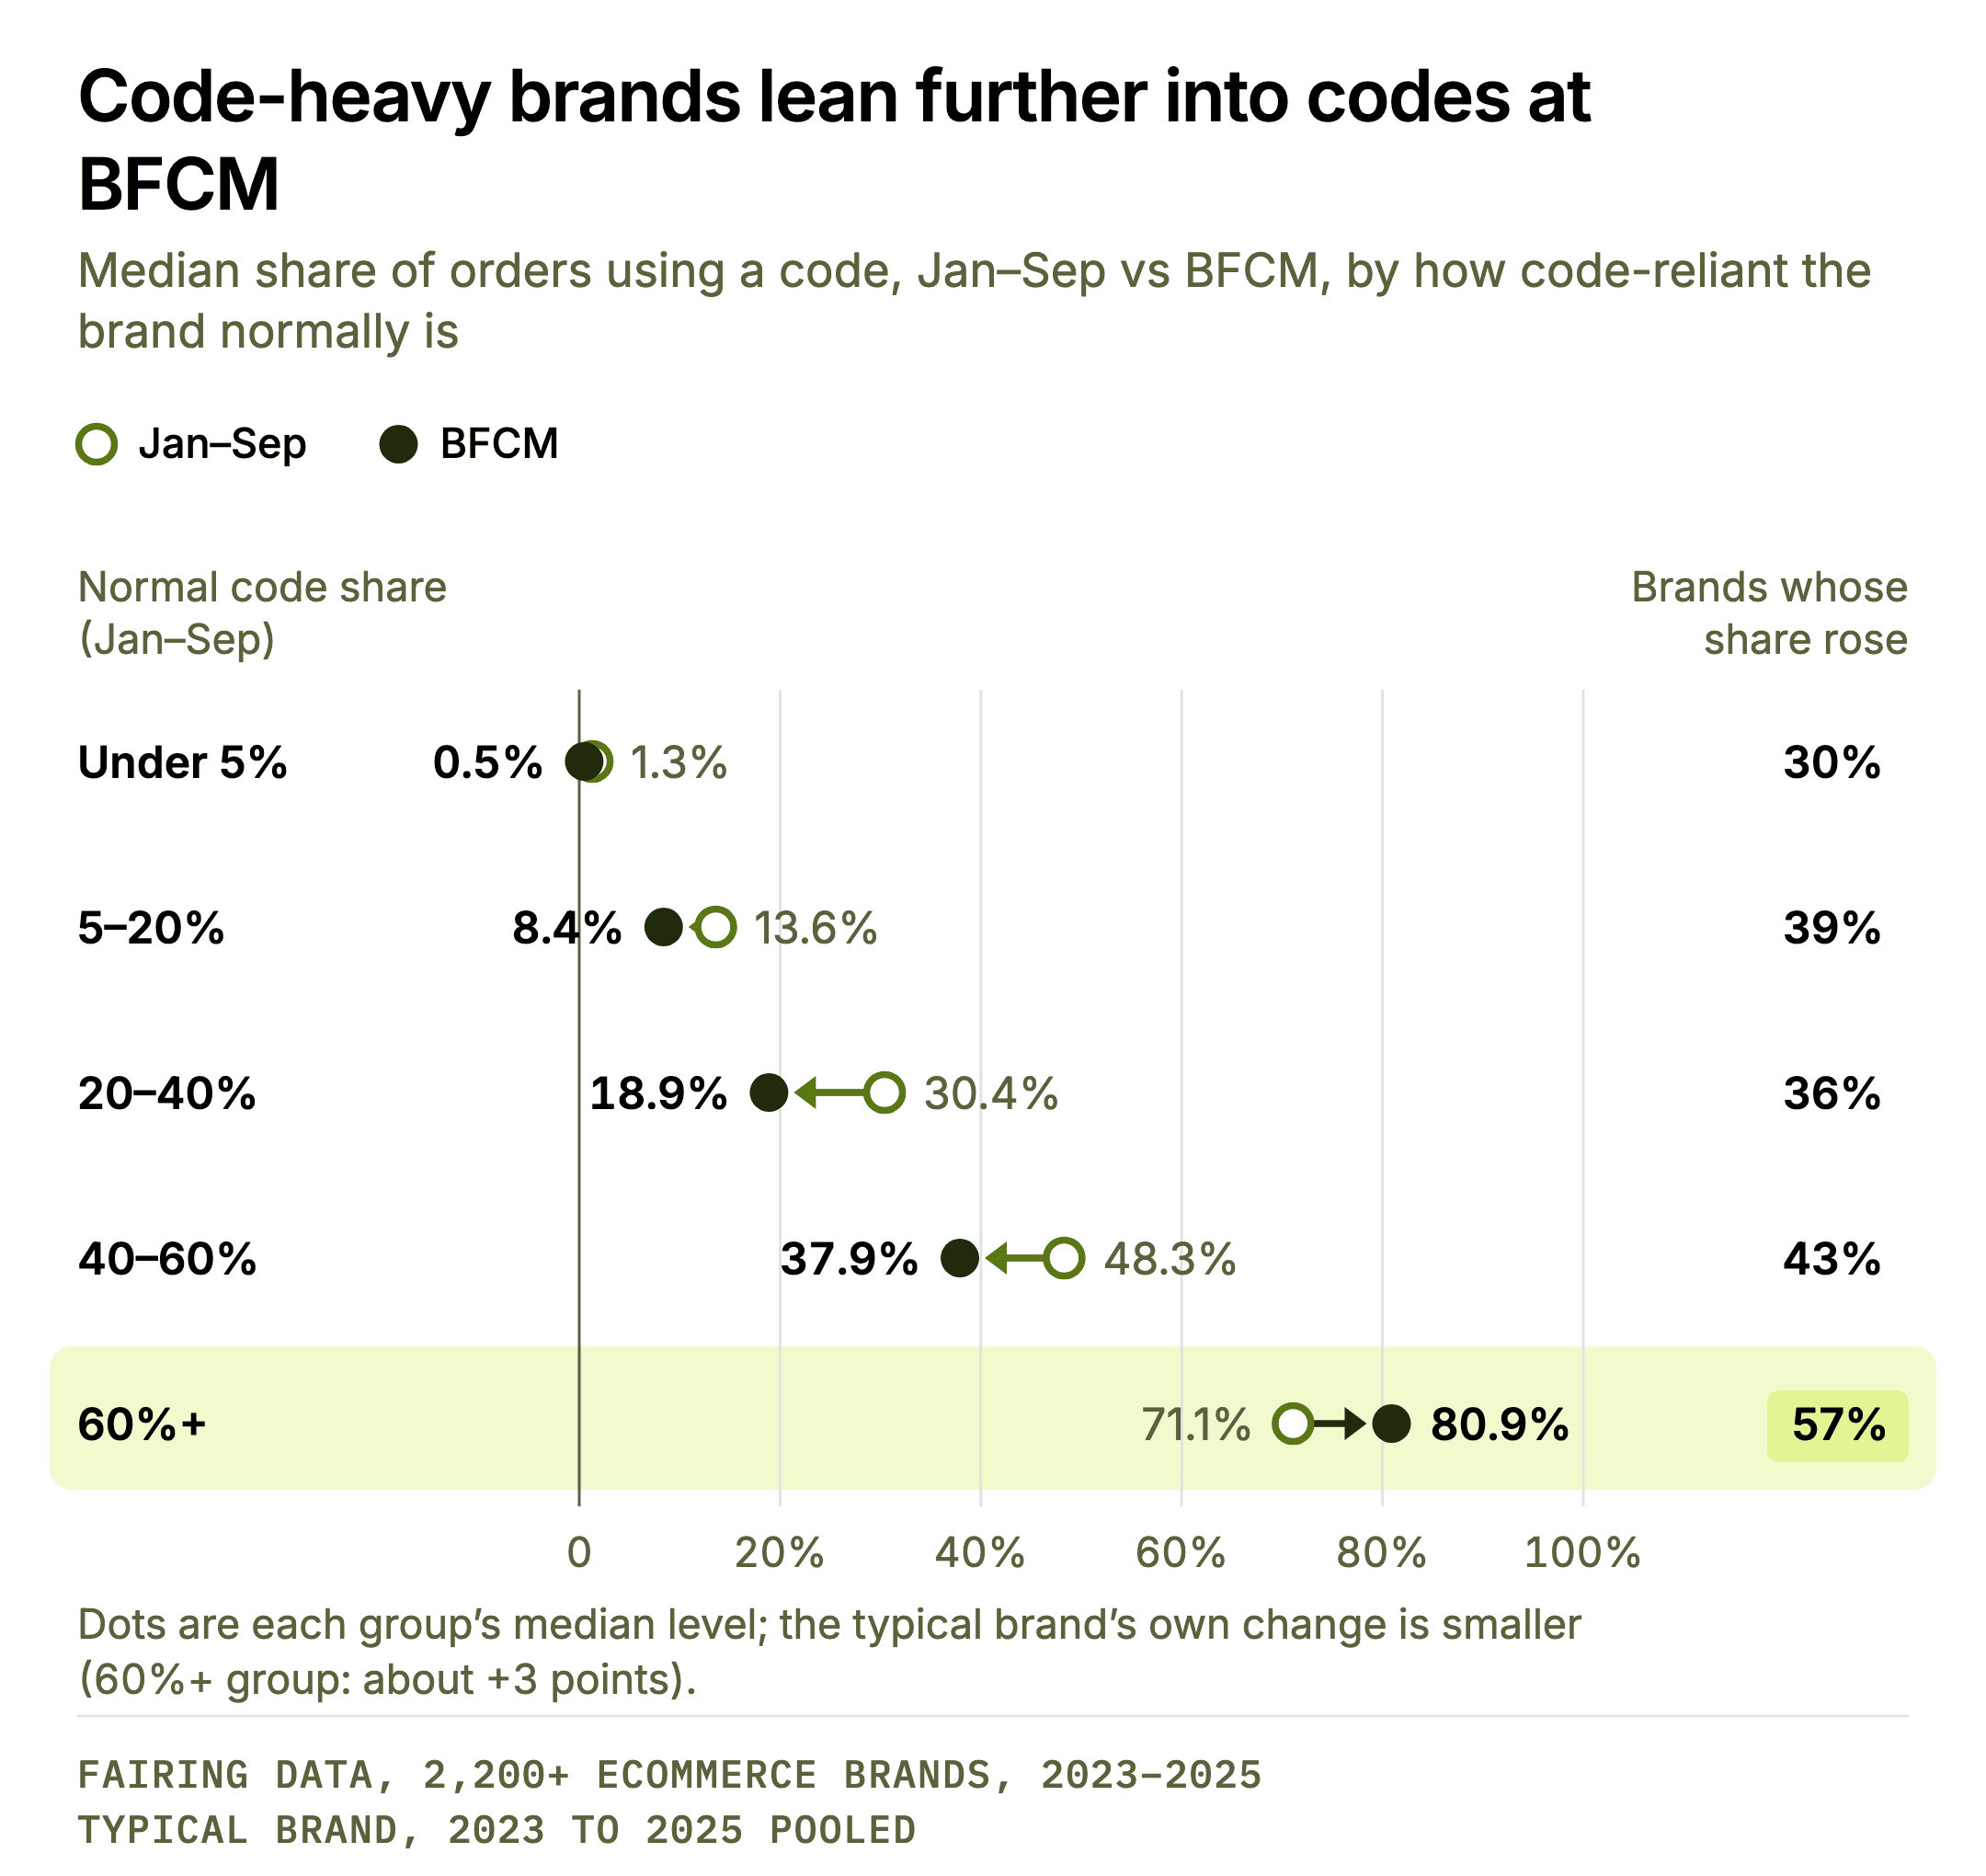
Brands that drop codes at BFCM lift more
| Change in code share at BFCM | Share of brand-seasons | Black Friday | Run-up | Week after |
|---|---|---|---|---|
| Dropped 10+ points | 39% | 6.05x | 1.69x | 1.50x |
| Dropped 2 to 10 points | 13% | 4.51x | 1.45x | 1.43x |
| Flat (within 2 points) | 12% | 3.07x | 1.29x | 1.31x |
| Rose 2+ points | 36% | 3.79x | 1.35x | 1.28x |
Within one brand, no link
Year over year, changing code reliance had no relationship with changing lift (correlation 0.01). The brands that run code-free sitewide sales, more often apparel, are the ones that spike hardest, but brands that cut their own code use didn’t see their lift rise on average.
Email and SMS drive a bigger share of Black Friday orders
In October, orders tagged as coming from email or SMS are 6% to 8% of the typical brand’s orders. On Black Friday they’re 10% to 12%, a share about 40% bigger, in both 2024 and 2025. Paid social goes the other way, from 4% to 5% of orders in October to 3% to 4% on Black Friday, down about a third. These are shares: with total orders at 4 to 5 times October, paid social orders still rise in number, just more slowly than everything else. About half of orders carry no UTM tag at all, so this is the tagged half of the picture.
Asking holds up better than codes
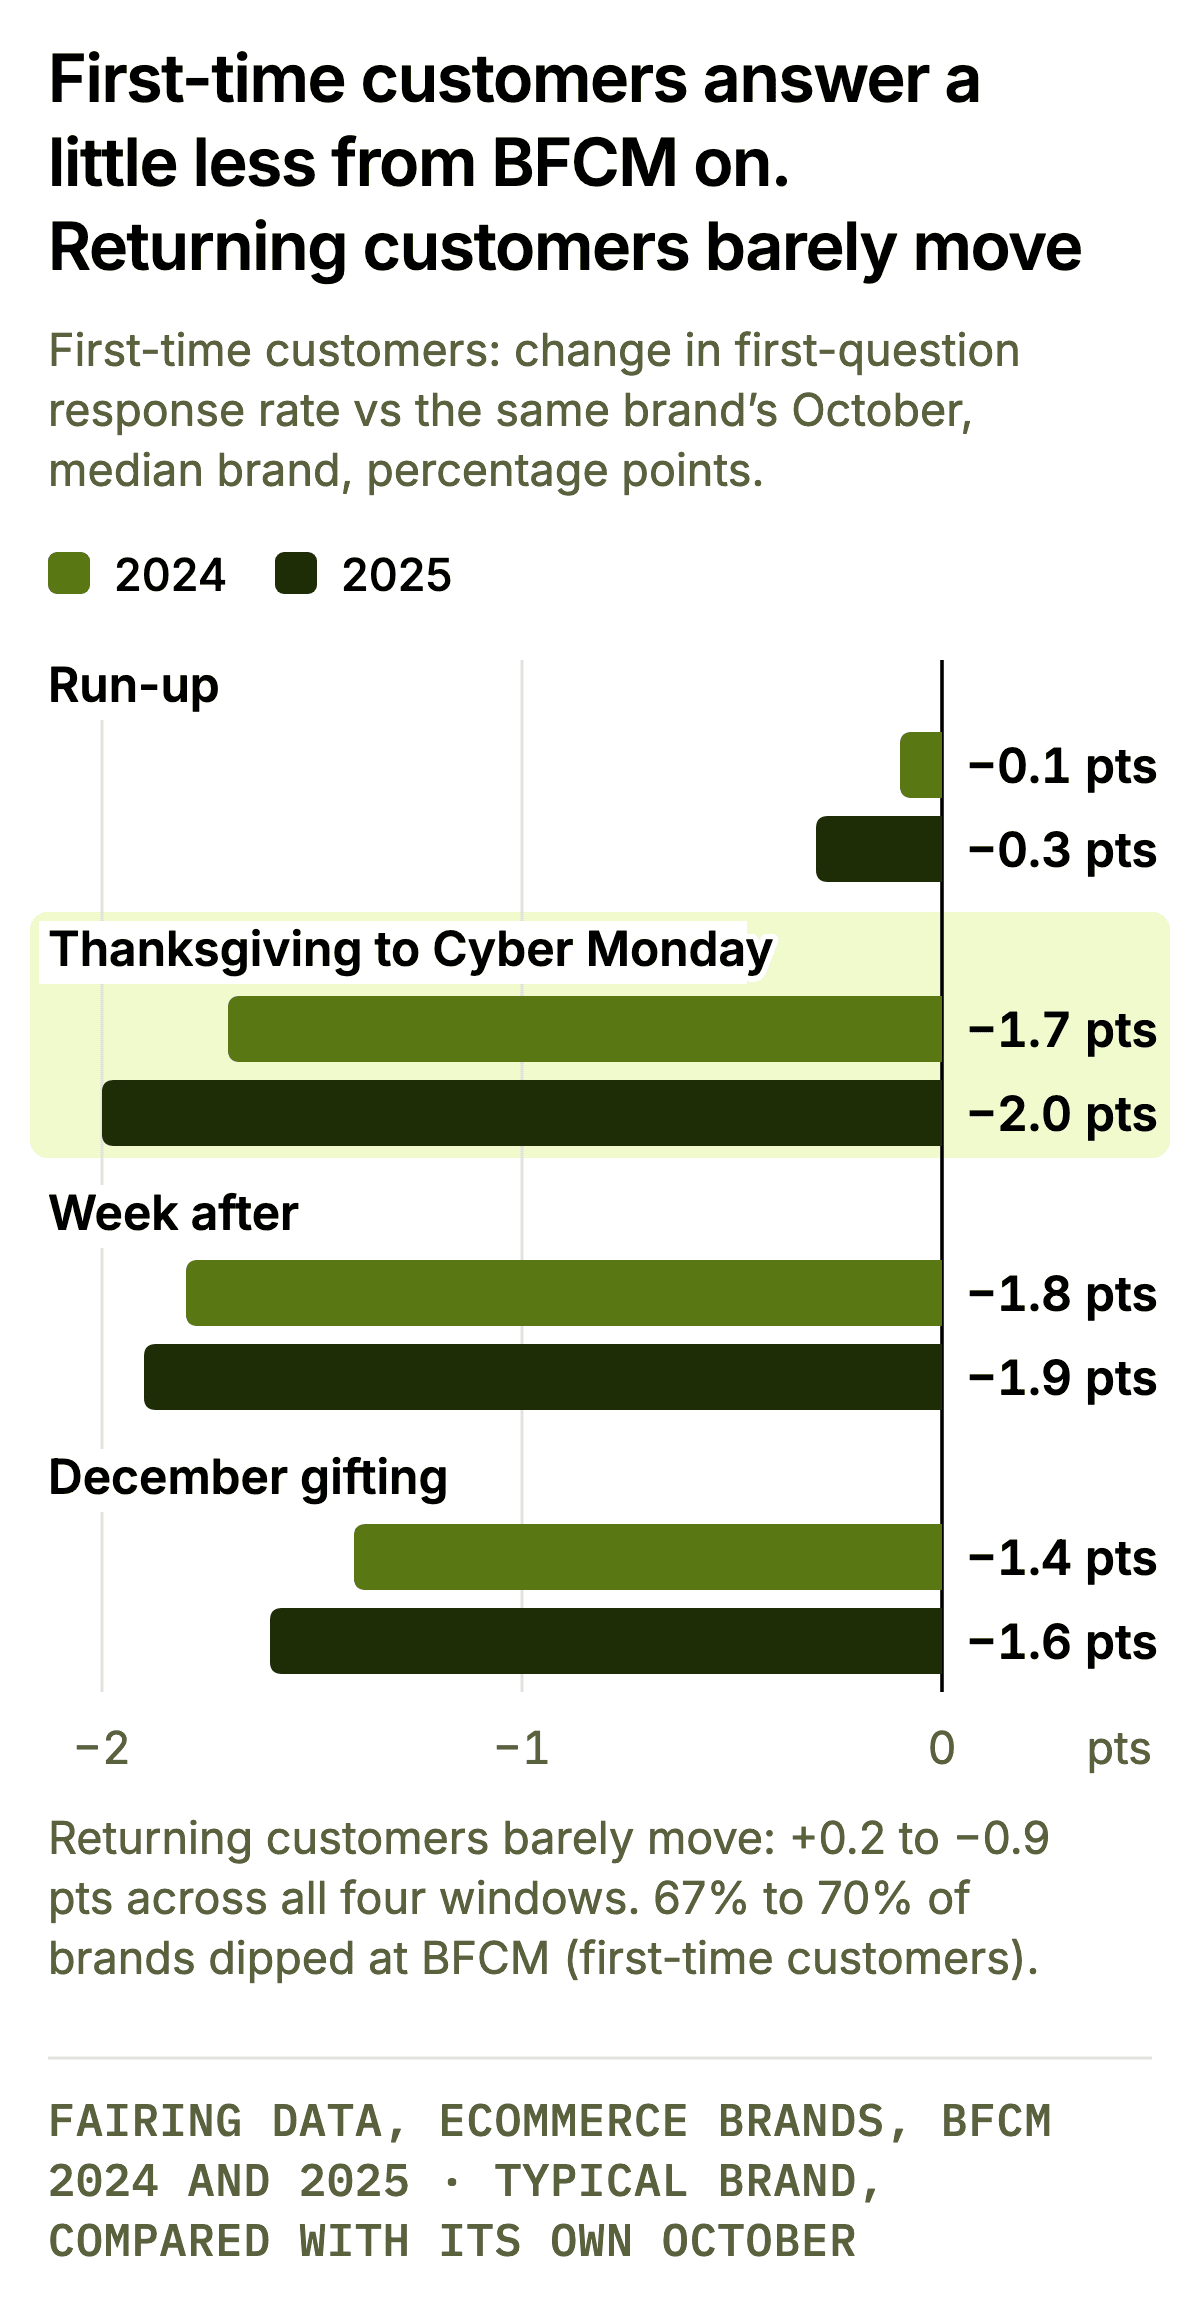
We checked how often first-time customers answer the first question of a post-purchase survey, against each brand’s own October rate. This covers the 2024 and 2025 seasons. The run-up is flat.
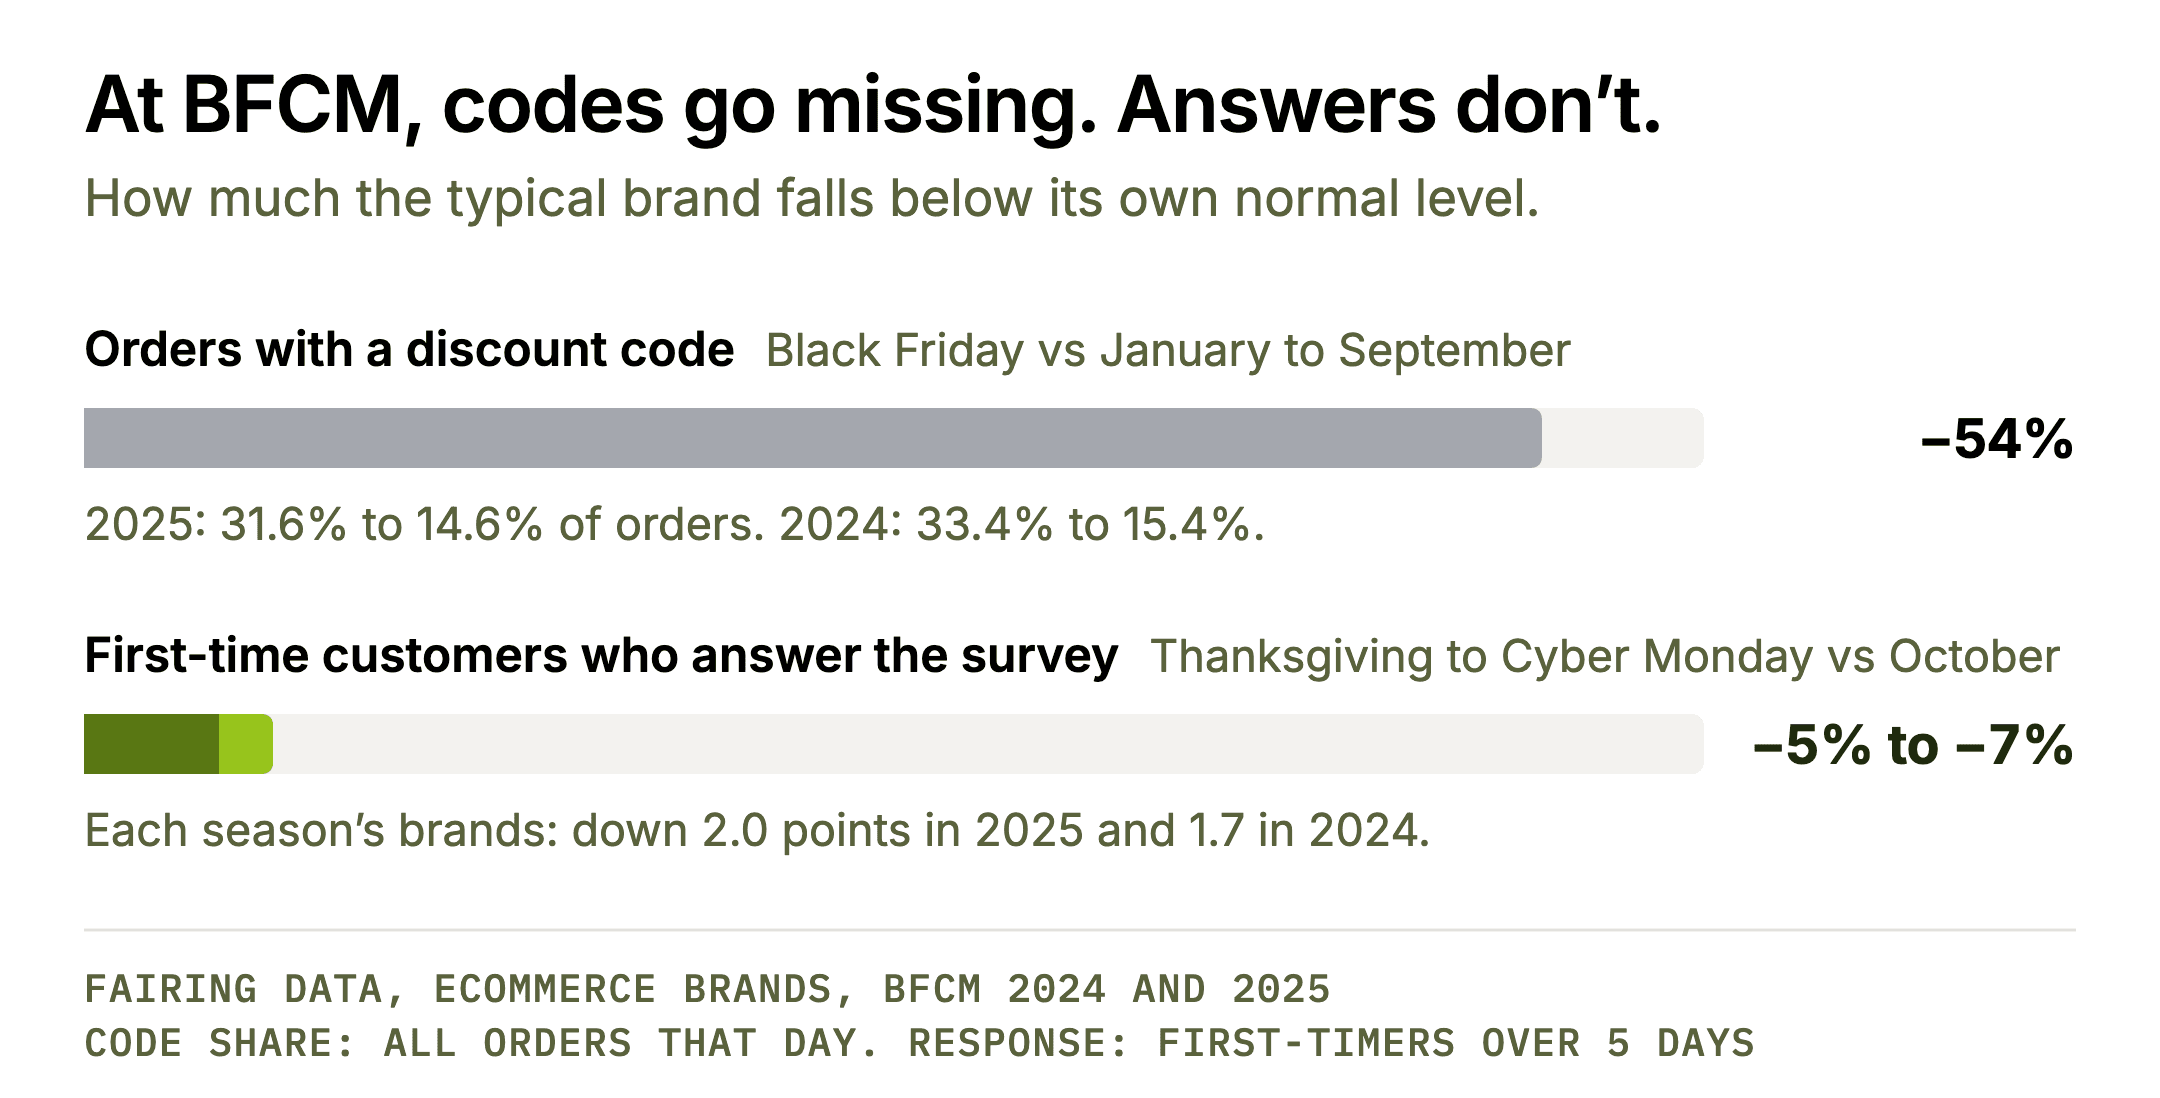
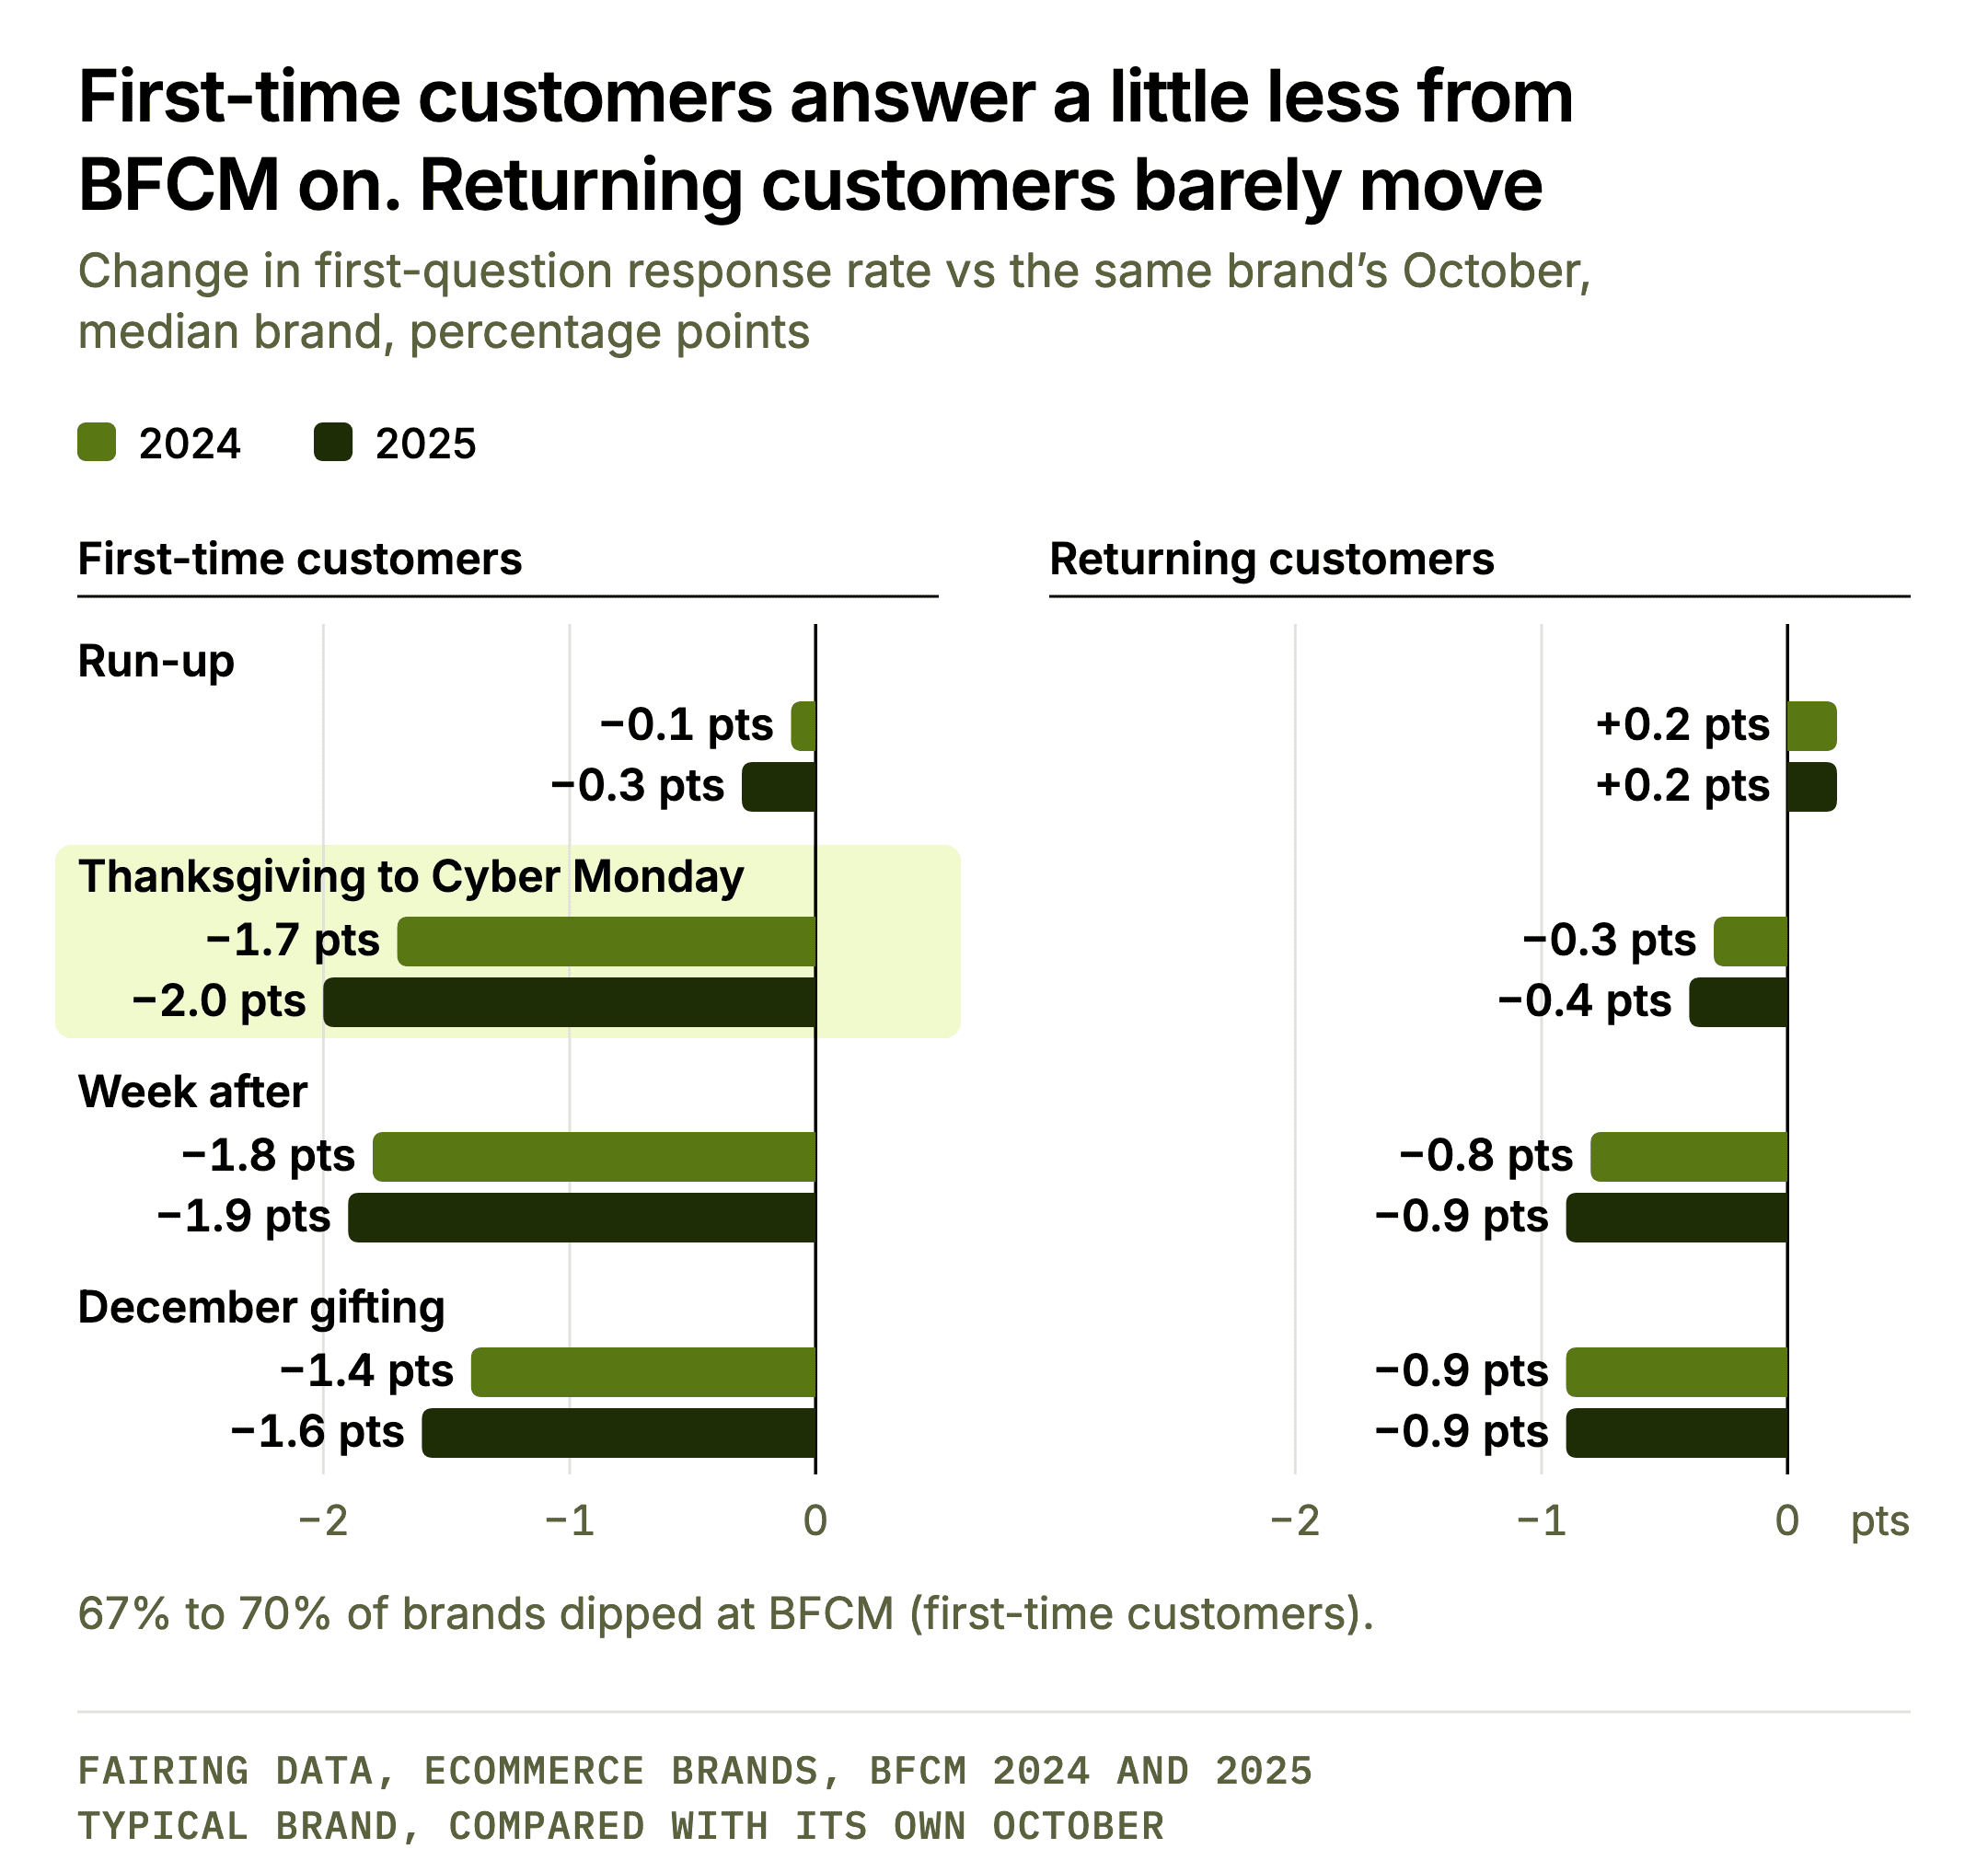
From Thanksgiving through Cyber Monday, the typical brand’s first-time response rate runs about 2 points below October: 1.7 in 2024 and 2.0 in 2025, across each season’s brands. 67% to 70% of brands see a dip. For the same brands followed through both seasons, it is 2.0 points in 2024 and 2.4 in 2025. It stays about that much lower through December, while returning customers barely move at BFCM.
The contrast with codes is stark. Code share falls by about half, while the share of first-time customers who answer slips about 2 points, roughly 5% to 7% in relative terms.
How to plan for BFCM 2026
Why it matters: With a sitewide discount live, a creator’s customer has no reason to type the code, so the order lands uncredited at peak, while a post-purchase “How did you hear about us?“ answer doesn’t depend on a code and dips only slightly.
If you run a sitewide offer, expect the share of orders with a code to fall by about half on Black Friday and Cyber Monday, even as code orders rise in number.
Agree with creators and affiliates paid on redemptions how BFCM credit will be handled before your first sitewide offer goes live.
Don’t read a BFCM drop in the share of revenue attributed to codes as a channel getting worse. Compare against what customers say brought them in.
Don’t drop codes expecting a bigger Black Friday. Brands that cut their code use didn’t see their lift rise on average.
If codes carry 60% or more of your orders, there’s about an even chance they carry more at BFCM. Budget partner payouts for it.
Expect email and SMS to carry a bigger share of Black Friday than usual. If paid social’s share of orders falls, that’s your list growing faster, not paid social failing.
12. The playbook
| If you are... | Do this |
|---|---|
| Any brand | Plan BFCM as a three-week season starting around Nov 11. Judge it on November and December extra orders against October, not on Black Friday alone. |
| A consumables brand | Build the basket with bundles, multi-packs and spend thresholds. Expect December a little below October level, and use it for subscription conversion. |
| An apparel or home brand | Treat BFCM as acquisition. Keep spend on through the December peak. |
| Under $73 AOV | Judge BFCM on revenue and basket size, not order count. |
| Building the forecast | Start from your own 2025 curve, mapped onto the 2026 calendar. Use a 25% band as the central case, stress-test at 50%, and don't plan on repeating a breakout year. |
| Worried early access hurts Black Friday | Test it on part of your list. Brands that grew their run-up grew their Black Friday, the week after and December too. |
| Planning the budget | Keep prospecting on through BFCM, and add new-customer creative and budget for Dec 5 to 20. |
| Repeat-heavy | Expect a fast drop after Cyber Monday. Plan December offers that reach people who didn't buy at BFCM. |
| Acquisition-led | Keep prospecting after Cyber Monday. Demand holds at about 1.5x October. |
| Acquiring at BFCM and in December | Expect those first-time buyers to reorder about 30% less often than October's within 90 days. Build the second-order flow before your first BFCM offer goes live. |
| Crediting creators, affiliates or podcasts by code | Expect the share of orders with a code to roughly halve at BFCM if you run sitewide offers. Ask customers where they heard about you to fill the gap. |
| Planning Q1 | Don't cut the forecast because BFCM was big. A bigger BFCM came with a stronger January to March. |
13. Are you on pace? The benchmark
Average daily orders in each week vs your own October daily average. Ranges are across brands, each measured against its own October.
Your October 2026 orders ÷ 31 = your October daily average.
Each Monday, take last week’s orders (Mon to Sun) ÷ 7 ÷ your October daily average.
Find your row. Below the bottom-quarter number puts you in the bottom quarter of brands that week; above the top-quarter number puts you in the top quarter.
| Week (2026) | Bottom 10% | Bottom quarter | Median | Top quarter | Top 10% |
|---|---|---|---|---|---|
| Oct 26 to Nov 1 | 0.77x | 0.89x | 1.01x | 1.16x | 1.42x |
| Nov 2 to 8 | 0.74x | 0.89x | 1.07x | 1.34x | 1.85x |
| Nov 9 to 15 | 0.75x | 0.92x | 1.16x | 1.62x | 2.44x |
| Nov 16 to 22Check Mon Nov 23 | 0.76x | 1.00x | 1.40x | 2.17x | 3.35x |
| Nov 23 to 29Thanksgiving, Black Friday, weekend | 1.02x | 1.61x | 2.68x | 4.39x | 6.78x |
| Nov 30 to Dec 6Cyber week | 0.85x | 1.18x | 1.78x | 2.76x | 4.38x |
| Dec 7 to 13Check Mon Dec 14 | 0.63x | 0.87x | 1.28x | 2.14x | 3.73x |
| Dec 14 to 20 | 0.60x | 0.83x | 1.19x | 1.97x | 3.31x |
| Dec 21 to 23 | 0.39x | 0.57x | 0.80x | 1.15x | 1.75x |
| Dec 24 to 25 | 0.28x | 0.44x | 0.68x | 1.06x | 1.63x |
| Dec 26 to 31 | 0.51x | 0.75x | 1.05x | 1.48x | 2.15x |
October = 1.00x by definition. November weeks line up with Black Friday (Nov 27, 2026). Rows from Dec 14 on are calendar dates, because Christmas doesn’t move. These are ranges across brands, not targets: a brand that sits in the bottom quarter every week, the same as last year, is on pace for itself.
Key days
| Day (2026) | Bottom 10% | Bottom quarter | Median | Top quarter | Top 10% |
|---|---|---|---|---|---|
| ThanksgivingThu Nov 26 | 0.69x | 1.19x | 2.09x | 3.55x | 5.84x |
| Black FridayFri Nov 27 | 1.27x | 2.47x | 4.63x | 8.27x | 13.42x |
| SaturdaySat Nov 28 | 0.94x | 1.62x | 2.82x | 4.69x | 7.53x |
| SundaySun Nov 29 | 1.02x | 1.73x | 3.02x | 5.04x | 7.92x |
| Cyber MondayMon Nov 30 | 1.20x | 2.05x | 3.81x | 6.45x | 10.76x |
| Tuesday afterTue Dec 1 | 0.71x | 1.10x | 1.81x | 3.05x | 4.99x |
| Cyber 5 averageThu to Mon | 1.13x | 1.92x | 3.38x | 5.61x | 8.84x |
Fairing data, 2,200+ Shopify and ecommerce brands, 2023–2025 · Brand-level, 3-yr mean of percentiles
This table uses the plain ratio you get on your own store. The daily charts above are adjusted for day of the week, so on peak days they read up to about 10% higher than this table.
These are ranges across brands, and none of them is a target. A brand that sits at p25 every week of the season, with the same shape as last year, is on pace for itself. Consumables brand? Expect to sit lower on the peak rows and the December rows (section 2).
Two Mondays give you time to act:
Mon Nov 23: read the Nov 16 to 22 week. Above p75, plan Thanksgiving-to-Cyber-Monday inventory, staffing and fulfillment toward the top-quarter numbers.
Mon Dec 14: read the Dec 7 to 13 week. Below 1.0x, send the gifting push and shipping-deadline messaging that day.
Write your October number down. Everything else in this post divides by it.
14. What we checked that didn’t change much
Here are the other questions operators ask us, where the data showed little or no change.
How deep code discounts go. Only 1 to 2 points deeper on Black Friday than in October (about 16% of the order against 14%). Percentage codes were already about 90% of code orders in October, 97% on Black Friday.
Basket size, new vs returning. Neither moves more than a few dollars on Black Friday. New customers’ usual small discount to returning customers’ order value widens by about 3 points.
Phone vs desktop. About 72% of Black Friday orders come from phones, the same as October. Cyber Monday leans 1 to 2 points toward desktop against a normal Monday, and phone orders run about 7% smaller than desktop all season.
Where shoppers land. The split between home page, product pages and collection pages barely moves. About 2 points shift from product pages to collection pages. (2025 only)
Untagged traffic. The share of orders with no UTM tag and no referrer moved about a point, in opposite directions in 2024 and 2025.
Cross-border orders. For US brands, about 0.9% of orders are billed outside the US, in October and at BFCM alike. (2025 only)
Early access and who buys. Brands with the biggest run-ups don’t skew more toward returning customers during the run-up.
Survey speed at peak. The 2-point BFCM dip in first-time customers’ response rate is the same whether the survey loads in under a second or takes more than two.
About the data
Who’s in it. Orders from more than 2,200 established Shopify and ecommerce brands running Fairing’s post-purchase survey, October to December in 2023, 2024 and 2025. “Established” means steady orders all quarter and at least 10 orders a day in October. A brand qualifies one season at a time, so the group differs from year to year. The typical brand does about 64 orders a day in October, and most do between 25 and 200.
How we measure. Every brand is measured against itself: its orders on a day, divided by its own average daily orders in October. That puts a 20-order-a-day brand and a 2,000-order-a-day brand on the same scale. Basket size and code share are compared with the brand’s own January to September. We report the median brand, with the middle half of brands as the range. Figures for all three years average the three yearly medians. A few numbers pool every brand’s orders, and we label those “across all orders”.
Comparing years. The mix of brands changes each season, so a yearly median can move just from who’s in it. Every year-over-year trend on this page (the 2025 Black Friday drop, the run-up, the week after, code share, December’s new customers) was checked on the same brands across years.
Charts vs tables. The daily charts in sections 4, 5 and 9 are set so a typical October day is 1.0 and are adjusted for weekday, so they read up to about 10% higher on peak days. The tables and the pacing benchmark use the plain ratio you’d get on your own store.
Limits. Three seasons are three data points. These are established, active Shopify and ecommerce brands on Fairing, not a random sample of all online stores. Order counts include only orders where our survey appeared. Correlations don’t prove cause.
Full methodology
Definitions. Extra orders: orders above the brand's October daily average, summed over a window (days below October count as negative). A new customer is someone placing their first order with the brand (customer order count of 0 or 1). Code share counts discount codes entered at checkout, not automatic discounts. Days use each shop's local time. Currency is the shop's currency, a stand-in for its main market. Category is the merchant's self-reported product category, collected when the brand set up its Fairing profile. AOV groups are USD brands only, split into four equal groups by January-to-September AOV, 2023 to 2025 pooled. Orders count only where Fairing's survey rendered, so headless storefronts and stores with the checkout extension off aren't included. If that share changes at peak, the multiples move with it.
Windows. Run-up = 16 to 2 days before Black Friday. Week after = the 7 days after Cyber Monday. December gifting = Dec 5 to 20 (new customers) or Dec 11 to 20 (orders), and the category December view runs from the end of Cyber week to Dec 25. After Christmas = Dec 26 to 31. Black Friday fell on Nov 24, Nov 29 and Nov 28, so calendar-date windows change length. Compare those per day. In 2024 and 2025 the Dec 5 to 20 window overlaps the last few days of the week after Cyber Monday. 2026 dates map the three-year average distance from Black Friday onto Black Friday, Nov 27. They're typical dates, not forecasts. January to March of the following year, and reorders up to 90 days into the new year, follow the same brands past December.
Response rate. The share of first-time customers shown the survey's first question who answered it (usually, but not always, the "How did you hear about us?" question), against the same brand's October. Covers 2024 and 2025, for brands with steady survey traffic.
Code share vs response rate. The two bars in that chart use different baselines (code share against January to September, response rate against October) and different windows (one day against five days).
Reorders. Each first-time buyer, followed by customer ID within the same shop, for 30, 60 and 90 days. Brands need at least 50 first-time buyers in the window.
Channel mix and device. Channel mix buckets each order's UTM source and medium (email and SMS, paid social, paid search). Hour of day and device use each shop's local time and the browser's user agent.
Breakout days. Standard deviations above the brand's October average, measured on October's daily ups and downs.
Stats. Same-brand tests compare year-over-year changes on a log scale and hold the brand's October change fixed. Confidence intervals on medians are 95% and rank-based. A brand can appear in up to three seasons, so the intervals run a little narrow.
Which brands each number uses.
| Kind of finding | Brands | Why |
|---|---|---|
| A brand against its own baseline in one season (Black Friday multiple, pacing table, code share, basket, new-customer share, response-rate change) | Every brand that qualified that season | Each brand is measured against itself, so size doesn't skew it. The group changes each year, so we don't compare these across years without the same-brand check. |
| Splits by size, category, price point or customer mix | All brand-seasons, 2023 to 2025 pooled | No comparison across time, so it describes the typical brand-season |
| Trends from one year to the next (the 2025 Black Friday drop, the week after, run-up share, the code-share step, December's new-customer lift, extra-order shares) | Checked on one fixed group of brands tracked across the years. The Black Friday drop was also tested brand by brand against each brand's own prior year, overall and by category | Each year's group is different, so a shift in the median could come from who's in it |
| Forecasting from last year (correlations) | The same brand in consecutive years | Built on matched brands |
| Response-rate dip | Brands with steady October survey traffic, re-checked on the brands present in both seasons | Same reason as the trends |
More limits. Single-year dates vary by a few days, and year-over-year trends rest on three points. The Black Friday median carries a 95% interval of roughly ±0.3 to 0.4x in any one year. The within-brand tests control for October but can't rule out a brand simply having a good year. Brands need steady Q4 activity to be included, so the results describe established, active brands.